Daily Research
Read More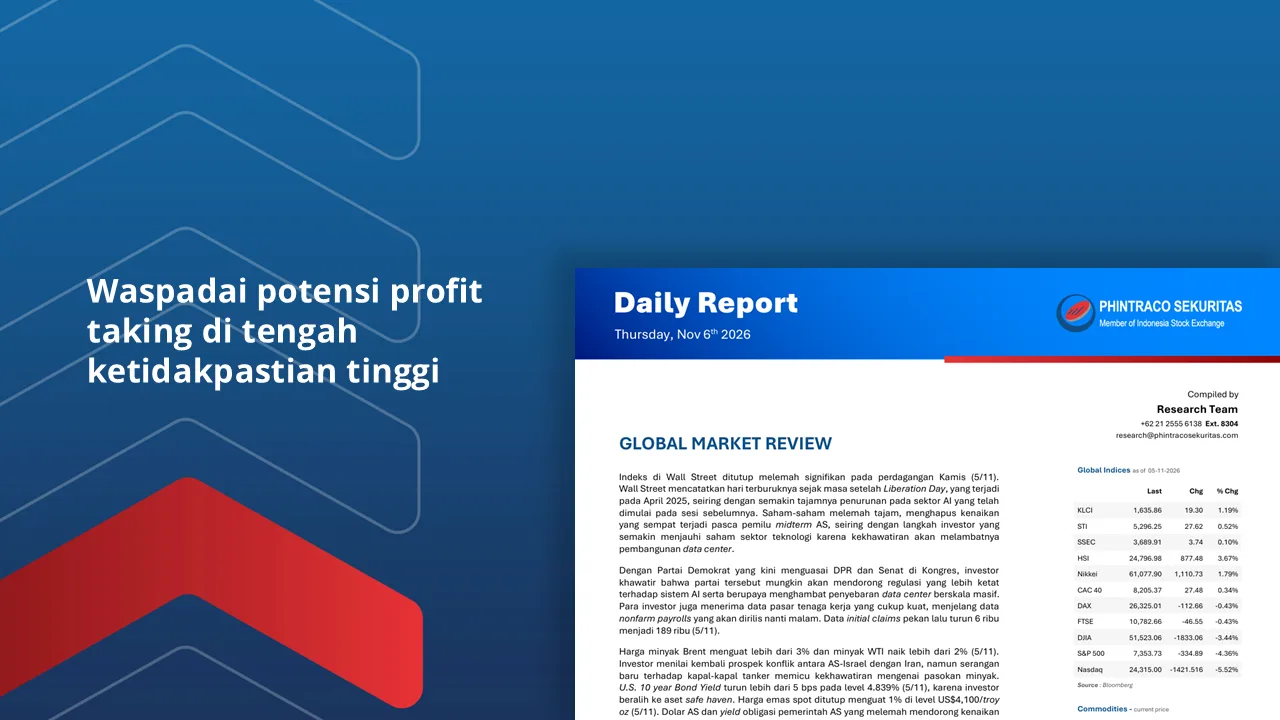
Waspadai potensi profit taking di tengah ketidakpastian tinggi

Indeks di bursa Wall Street ditutup melemah signifikan pada Kamis (5/11).
Wall Street mencatatkan hari terburuknya sejak masa setelah Liberation Day.
Investor melepas saham sektor teknologi karena kekhawatiran akan melambatnya pembangunan data center.
Data initial claims pekan lalu turun 6 ribu menjadi 189 ribu (5/11).
Investor menantikan data nonfarm payrolls (6/11).
Harga minyak Brent menguat lebih dari 3% (5/11).
U.S. 10-year Bond Yield turun lebih dari 5 bps pada level 4.839% (5/11).
Harga emas spot ditutup menguat 1% di level US$4,100/troy oz (5/11).
Ekonomi Indonesia tumbuh 5.47% YoY pada 3Q26 (5/11).
IHSG berpeluang menguji level resistance di 5,100-5,125, namun perlu diwaspadai potensi profit taking.
Top picks (6/11): BBCA, BBRI, AMMN, EMAS dan INDF.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
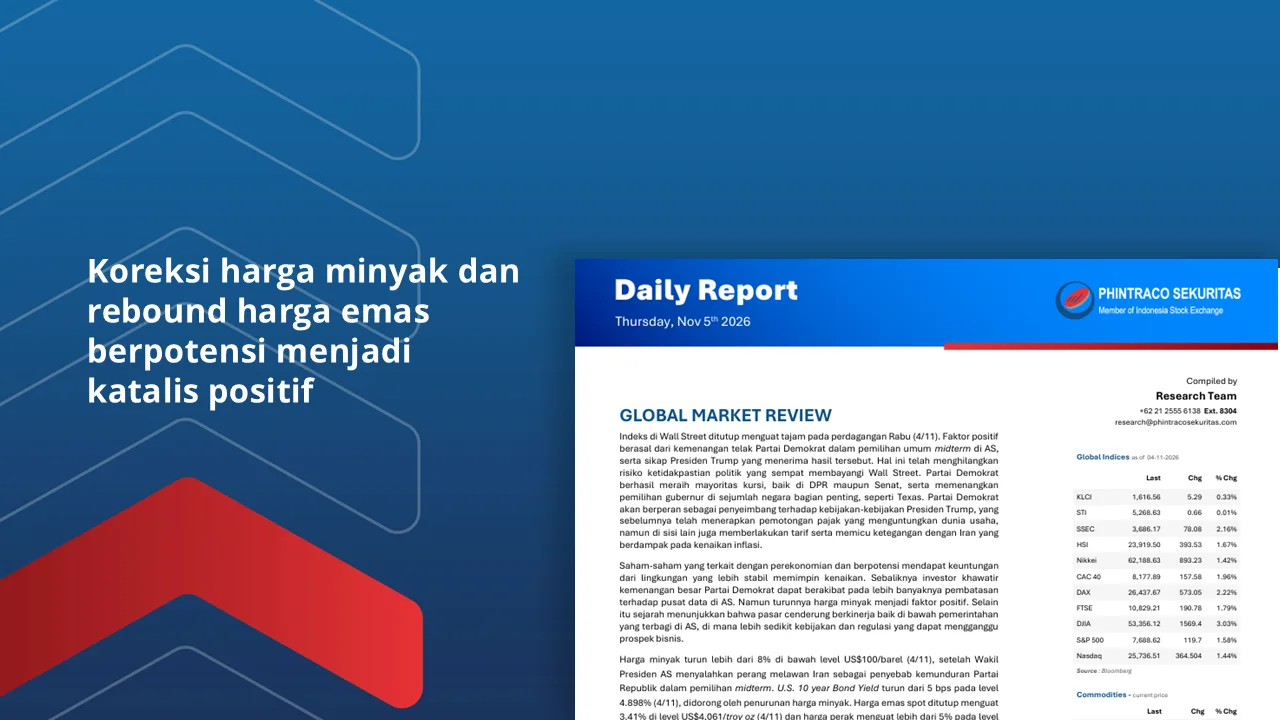
Koreksi harga minyak dan rebound harga emas berpotensi menjadi katalis positif
Indeks di bursa Wall Street ditutup menguat signifikan pada Rabu (4/11).
Kemenangan Partai Demokrat dalam pemilu midterm di AS dan Presiden Trump yang menerima hasil itu menjadi katalis positif.
Partai Demokrat berhasil meraih mayoritas kursi, baik di DPR maupun Senat, serta memenangkan pemilihan gubernur di sejumlah negara bagian.
Harga minyak turun lebih dari 8% di bawah level US$100/barel (4/11).
U.S. 10-year Bond Yield turun dari 5 bps pada level 4.898% (4/11).
Harga emas spot ditutup menguat 3.41% di level US$4,061/troy oz (4/11).
Ekonomi Indonesia diperkirakan tumbuh 1.3% QoQ pada 3Q26 dari 3.73% QoQ pada 2Q26 (5/11).
Penguatan signifikan indeks di Wall Street, koreksi harga minyak mentah dan dolar AS, serta reboundnya harga emas, berpotensi menjadi sentimen positif.
Secara teknikal diperkirakan IHSG bergerak sideways pada kisaran 4,800-5,000.
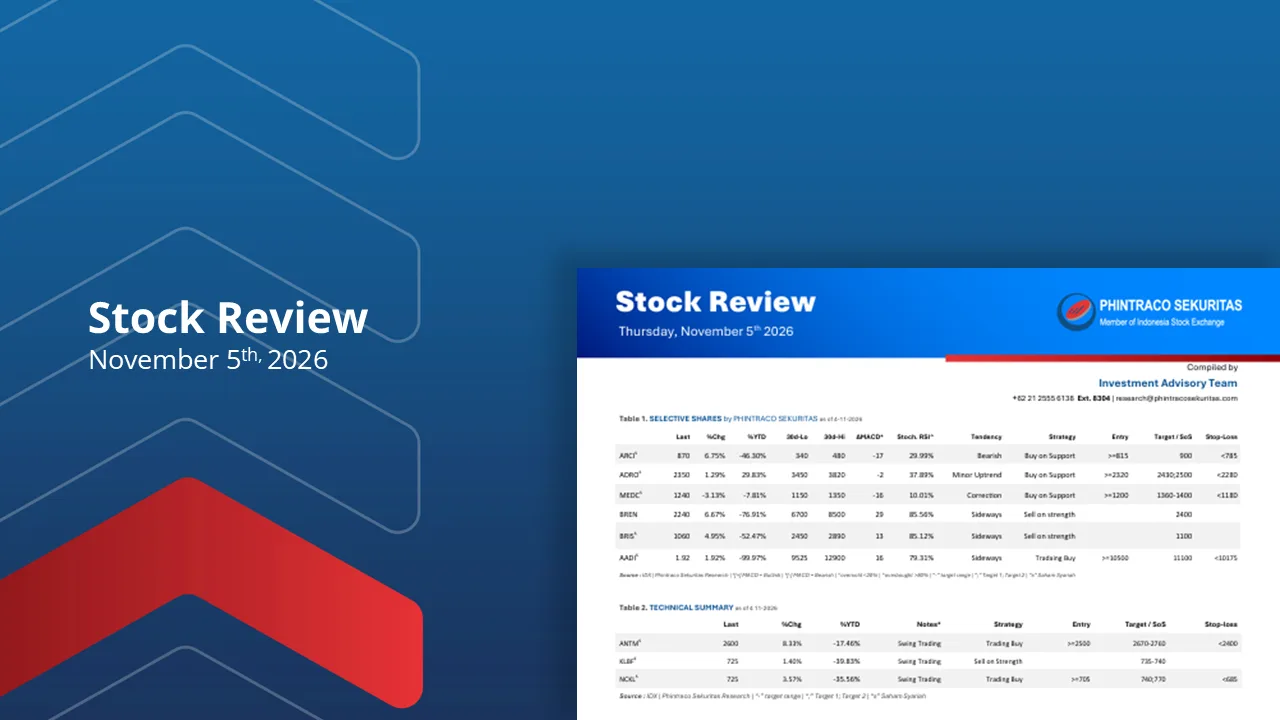
Top picks (5/11): ANTM, AADI, ARCI, ADRO dan BREN.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
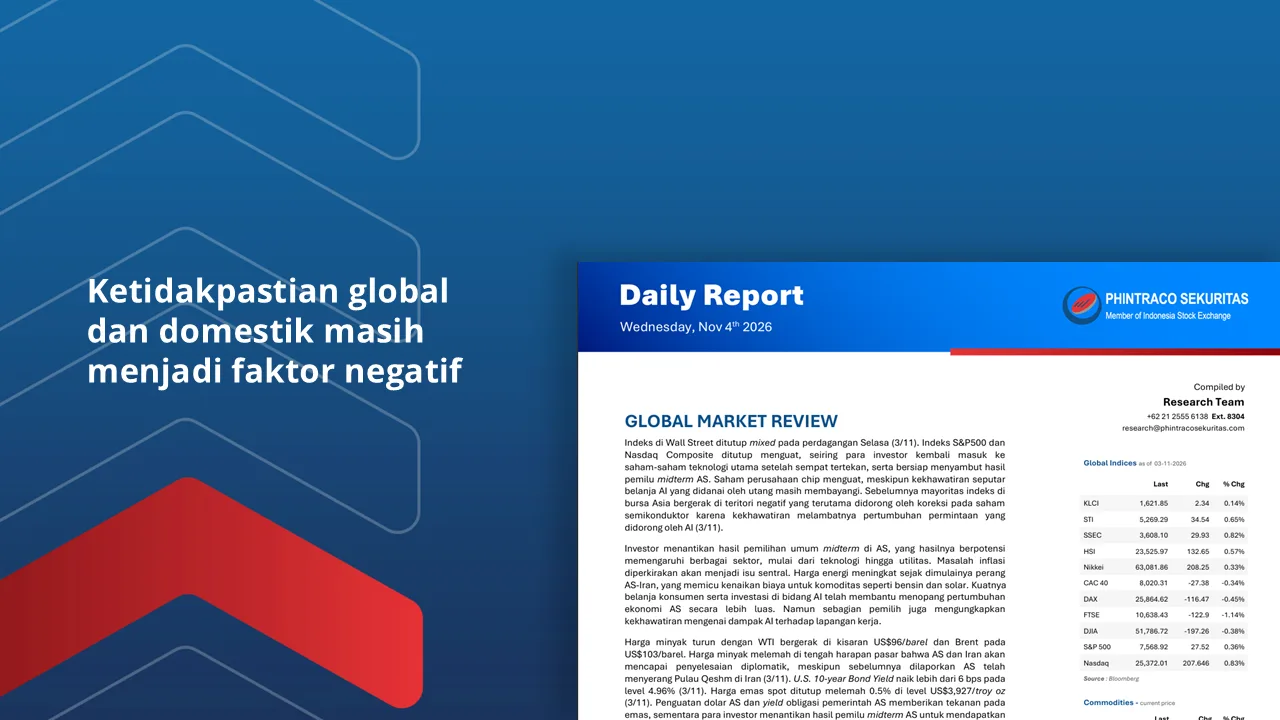
Ketidakpastian global dan domestik masih menjadi faktor negatif
Indeks di bursa Wall Street ditutup mixed pada Selasa (3/11).
Investor kembali masuk ke saham-saham teknologi utama setelah sempat tertekan.
Investor menantikan hasil pemilu midterm AS.
KSSK menurunkan proyeksi pertumbuhan ekonomi Indonesia tahun 2026 menjadi 5.4%–5.5%.
Menkeu menegaskan Pemerintah tidak akan memberlakukan skema pungutan pajak baru pada 9 November 2026.
Pemerintah tengah merancang perubahan aturan DHE SDA.
Harga minyak melemah karena harapan akan tercapai kesepakatan AS dan Iran (3/11).
U.S. 10-year Bond Yield naik lebih dari 6 bps pada level 4.96% (3/11).
Harga emas spot ditutup melemah 0.5% di level US$3,927/troy oz (3/11).
IHSG berpotensi uji level 4,650-4,750 jika support di 4,900 tidak mampu menahan penurunan lebih lanjut.
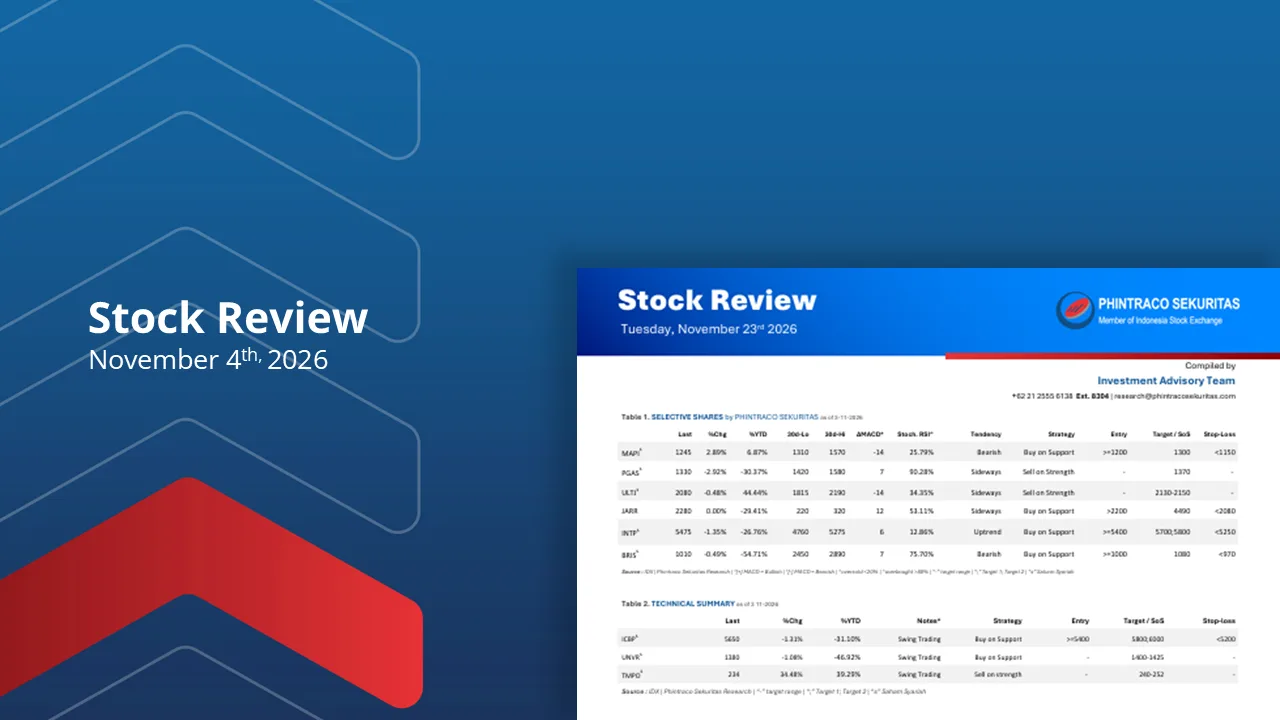
Top picks (4/11): MAPI, ICBP, UNVR, PGAS dan ULTJ.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Technical Research
Read More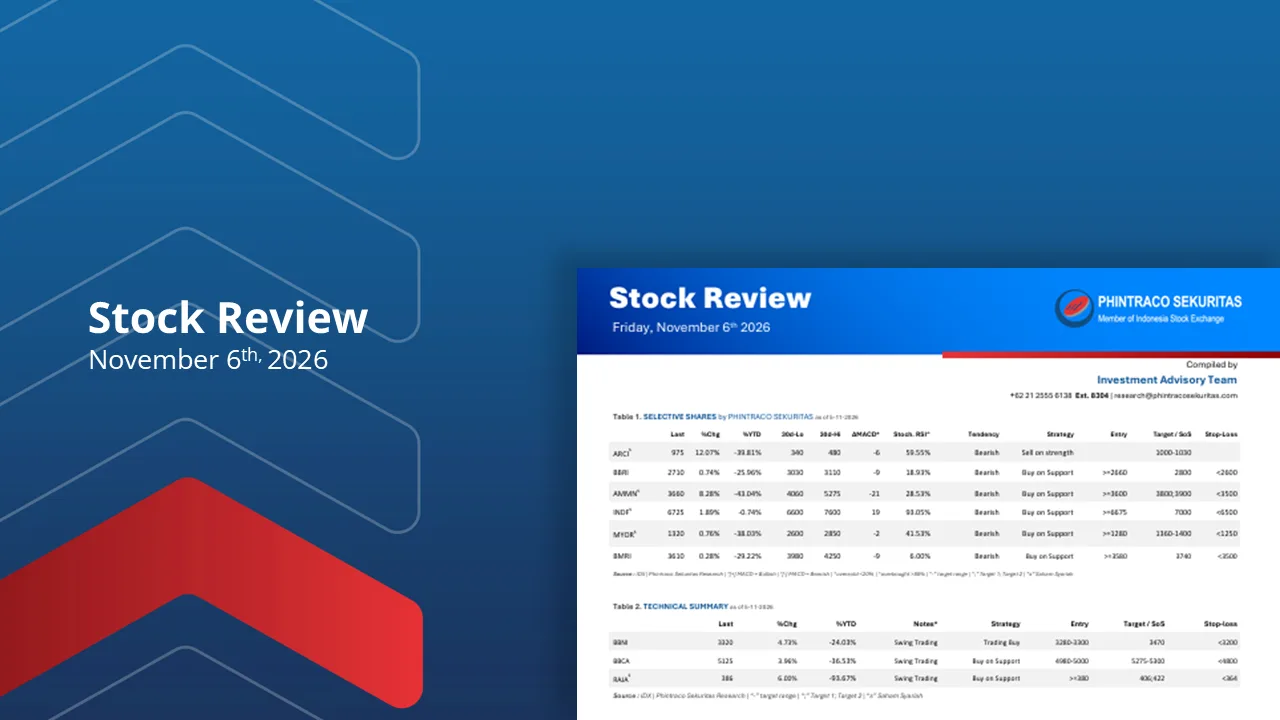
Weekly Research
Read More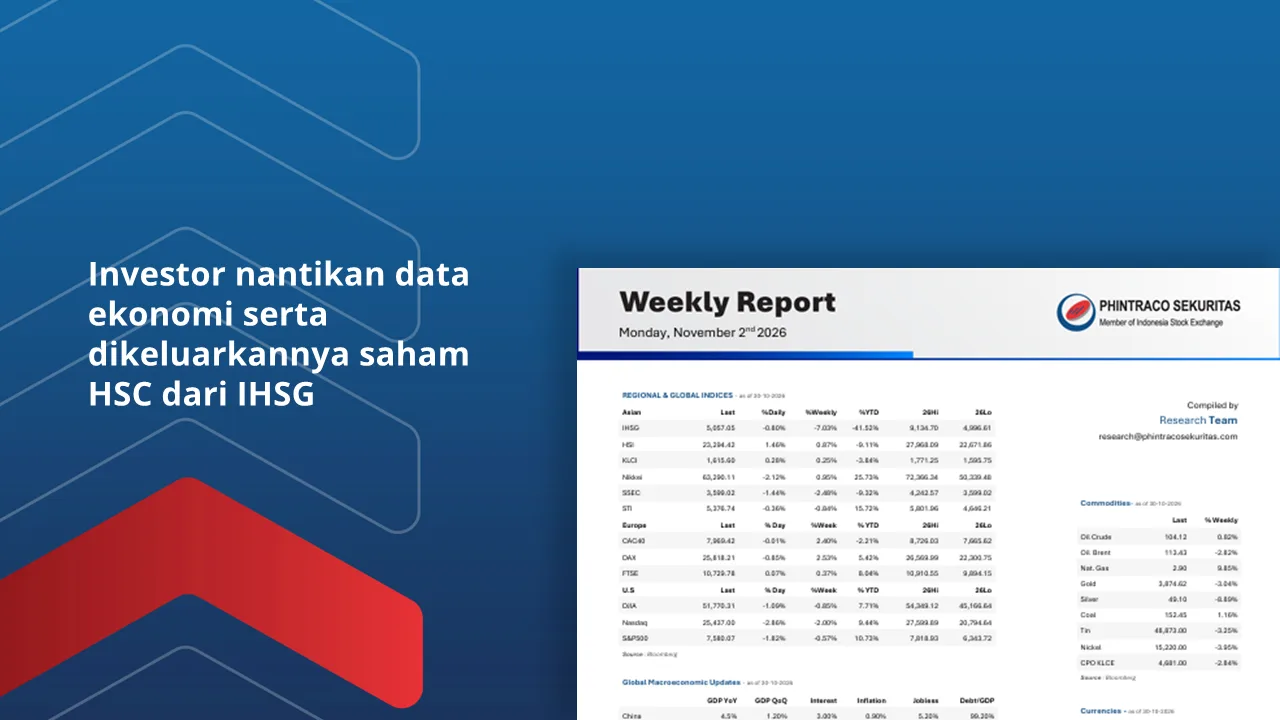
Investor nantikan data ekonomi serta dikeluarkannya saham HSC dari IHSG
Indeks di bursa Wall Street ditutup melemah signifikan pada Jumat (30/10).
Pelemahan indeks akibat koreksi saham AI dan antisipasi pemilu midterm di AS.
Harga minyak naik lebih dari 2%, ditutup pada level tertinggi sejak akhir April (30/10).
Harga emas spot melemah 2.7% pada level US$3,910/troy oz (30/10).
Investor akan mencermati pemilu midterm di AS pada pekan ini (3/11).
Dari domestik akan dirilis data Manufacturing PMI, neraca perdagangan, inflasi, pertumbuhan ekonomi 3Q26, cadangan devisa, serta indeks harga rumah di pekan ini.
Saham-saham HSC akan dikeluarkan dari perhitungan IHSG mulai Senin (2/11).
Secara teknikal IHSG diperkirakan bergerak pada kisaran 4,900-5,200 pekan ini.
Top picks pekan ini: LSIP, ASII, HMSP, ADRO dan INDF.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
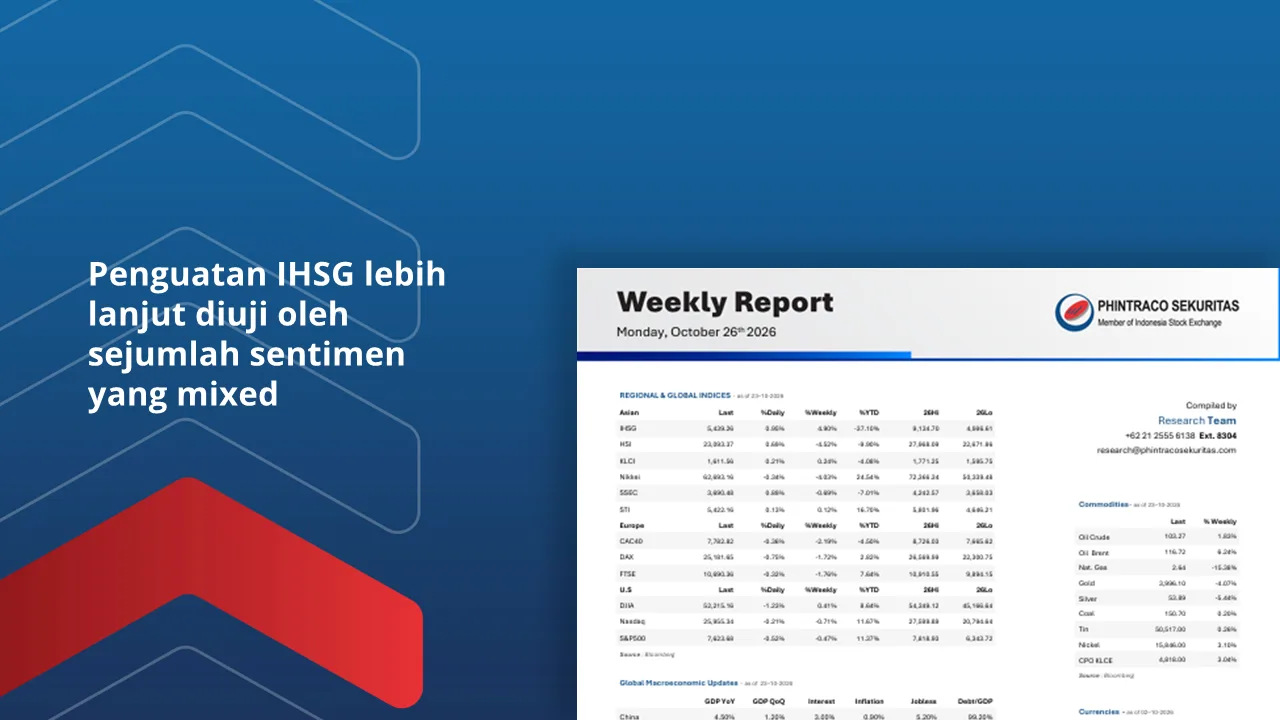
Penguatan IHSG lebih lanjut diuji oleh sejumlah sentimen yang mixed
Indeks di bursa Wall Street ditutup melemah pada Jumat (23/10).
Kenaikan harga minyak mendorong pelemahan indeks di Wall Street.
Harga WTI di level US$103/barel dan Brent pada level US$116/barel (23/10).
Harga emas spot melemah 0.6% pada level US$3,998/troy oz (23/10).
Investor akan menantikan hasil FOMC Meeting, inflasi PCE dan PDB AS (28/10).
ECB (29/10) dan BOJ (30/10) akan melakukan pertemuan bahas kebijakan moneter.
Cermati saham yang terkait dengan energi dan berorientasi ekspor.
Secara teknikal IHSG berpeluang uji level resistance 5,500-5,600, namun waspadai sentimen negatif dari eksternal dan profit taking.
Top picks pekan ini: ELSA, MEDC, MAPI, TEBE dan RAJA.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
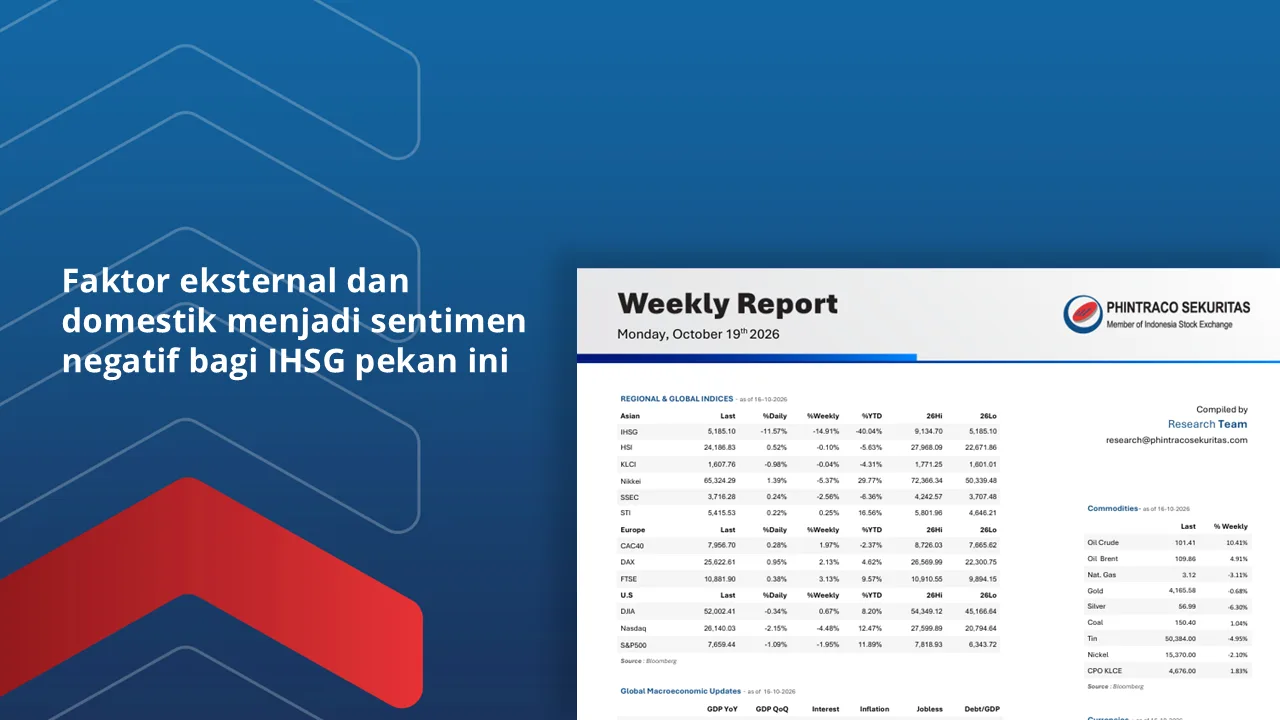
Faktor eksternal dan domestik menjadi sentimen negatif bagi IHSG pekan ini
Indeks di bursa Wall Street ditutup melemah pada Jumat (16/10).
Faktor negatif dari tekanan jual pada saham sektor AI dan naiknya harga minyak.
Harga minyak Brent meningkat lebih dari 3% pada level US$110/barel (16/10).
Indeks VIX menguat di atas level 22, pertama kali dalam empat bulan (16/10).
Investor akan cermati perkembangan geopolitik Ukraina dan Timur Tengah.
Dari domestik akan dirilis RDG Bank Indonesia, pertumbuhan kredit dan money supply.
Volatilitas perdagangan saham di BEI berpeluang akan meningkat pekan ini.
Diperkirakan IHSG menguji level 5,000 pekan ini, jika break berpotensi uji level support berikutnya di 4,700-4,800.
Top picks pekan ini: PWON, PTBA, TAPG, ITMG dan UNTR.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Fixed Income Research
Read More
Daily Fixed Income Report – 13 August 2026
U.S. Consumer Inflation melambat untuk bulan kedua berturut-turut menjadi 3.4% YoY pada Juli 2026 dari 3.5% YoY pada Juni, sejalan dengan ekspektasi, seiring meredanya dampak kenaikan harga energi akibat perang dengan Iran. Inflasi bensin turun menjadi 24.6% YoY dari 26.7% YoY, bahan bakar minyak menjadi 39.1% YoY dari 42.9% YoY. Sementara secara bulanan, inflasi AS naik 0.1% MoM pada Juli 2026 dari deflasi 0.4% MoM Juni 2026.
Posisi utang pemerintah Indonesia tercatat naik 3.76% MoM menjadi Rp10,293.69 triliun pada Juni 2026, setara dengan 41.26% terhadap Produk Domestik Bruto (PDB). Mayoritas utang, atau sekitar 87.11% dari total utang, bersumber dari penerbitan Surat Berharga Negara (SBN), sementara sisanya adalah komponen pinjaman.
Baca Laporan

Daily Fixed Income Report – 12 August 2026
U.S. Existing Home Sales turun lebih dalam 1.7% MoM menjadi 4.05 juta unit pada Juli 2026 dari penurunan 1.4% MoM pada Juni 2026 dan sedikit di bawah ekspektasi pasar sebesar 4.06 juta unit. Penjualan melemah di wilayah Selatan (-3.1% MoM) dan Midwest (-2.0% MoM). Meski demikian, secara tahunan penjualan masih meningkat 2.4% YoY pada Juli 2026,dengan pasar berpotensi menguat jika rata-rata suku bunga KPR kembali mendekati 6.0%.
Penjualan ritel Indonesia masih mengalami kontraksi 3% YoY pada Juni 2026, tetapi membaik dari kontraksi 3.9% YoY dari Mei 2026. Secara bulanan, penjualan ritel tumbuh 0.7% MoM pada Juni 2026 dari kontraksi 1.5% MoM pada Mei 2026. Penjualan ritel secara tahunan diperkirakan naik 0.9% YoY, sedangkan penjualan ritel secara bulanan diperkirakan turun 0.3% MoM pada Juli 2026.
Baca Laporan
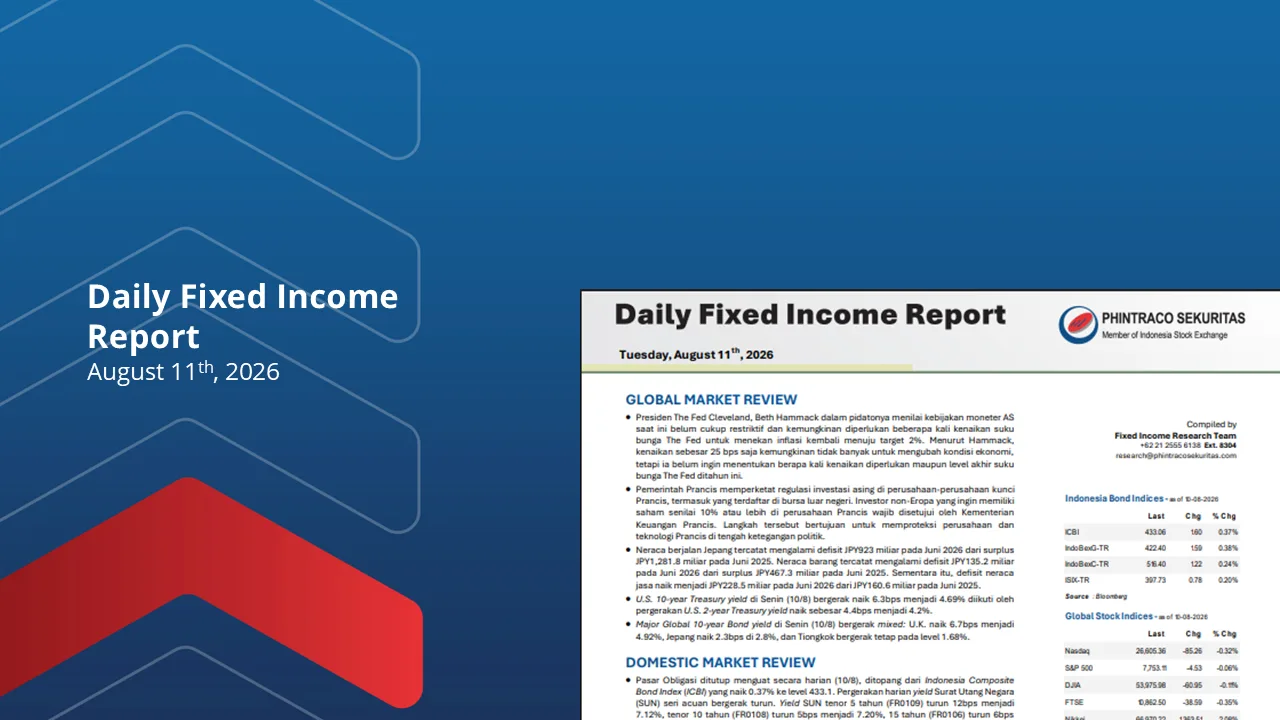
Daily Fixed Income Report – 11 August 2026
Presiden The Fed Cleveland, Beth Hammack dalam pidatonya menilai kebijakan moneter AS saat ini belum cukup restriktif dan kemungkinan diperlukan beberapa kali kenaikan suku bunga The Fed untuk menekan inflasi kembali menuju target 2%. Menurut Hammack, kenaikan sebesar 25 bps saja kemungkinan tidak banyak untuk mengubah kondisi ekonomi, tetapi ia belum ingin menentukan berapa kali kenaikan diperlukan maupun level akhir suku bunga The Fed ditahun ini.
Indeks Keyakinan Konsumen (IKK) tetap berada pada level optimis yaitu di atas level 100, tetapi turun ke level 116.8 pada Juli 2026 dari 117.8 pada Juni 2026. Optimisme konsumen tersebut ditopang oleh Indeks Kondisi Ekonomi Saat Ini (IKE) yang turun menjadi 107.9 pada Juni 2026 dari 109.2 pada Juli 2026 dan Indeks Ekspektasi Konsumen (IEK) yang turun menjadi 125.7 pada Juli 2026 dari 126.4 pada Juni 2026.
Baca Laporan
Single Stock Future
Read More
IPO Summary
Read More
PT Rans Entertainmen Indonesia Tbk (RANS)
Code : RANS
Sector : Consumer Cyclicals
Sub-Sector : Entertainment & Movie Production
---------------------------------------------
PERKIRAAN JADWAL PENAWARAN UMUM PERDANA SAHAM
Perkiraan Tanggal Efektif :
30 Juni 2026
Perkiraan Masa Penawaran Umum :
2 Juli 2026 - 8 Juli 2026
Perkiraan Tanggal Penjatahan :
8 Juli 2026
Perkiraan Tanggal Distribusi Saham :
9 Juli 2026
Perkiraan Tanggal Pencatatan Saham di BEI :
10 Juli 2026
---------------------------------------------
STRUKTUR PENAWARAN UMUM PERDANA SAHAM
Sebanyak-banyaknya sebesar 2,525,000,000 (dua miliar lima ratus dua puluh lima juta) saham biasa atas nama, atau sebanyak-banyaknya sebesar 20.02% (dua puluh koma nol dua persen) dari modal ditempatkan dan disetor Perseroan setelah Penawaran Umum Perdana Saham dengan nilai nominal Rp10,- (sepuluh Rupiah) setiap saham.
Nilai Nominal :
Rp10 per lembar saham
Harga Penawaran :
Rp135 - Rp170 per lembar saham
Jumlah Penawaran Umum :
Sebanyak-banyaknya sebesar Rp429,250,000,000,- (empat ratus dua puluh sembilan miliar dua ratus lima puluh juta Rupiah).
Penjamin Pelaksana Emisi Efek:
PT Trimegah Sekuritas Indonesia
Penjamin Emisi :
Akan ditentukan kemudian
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
PT Bach Multi Global Tbk (BACH)
Code : BACH
Sector : Industrials
Sub-Sector : Diversified Industrial Trading
---------------------------------------------
PERKIRAAN JADWAL PENAWARAN UMUM PERDANA SAHAM
Perkiraan Tanggal Efektif :
29 Juni 2026
Perkiraan Masa Penawaran Umum :
1 Juli 2026 - 3 Juli 2026
Perkiraan Tanggal Penjatahan :
3 Juli 2026
Perkiraan Tanggal Distribusi Saham :
6 Juli 2026
Perkiraan Tanggal Pencatatan Saham di BEI :
7 Juli 2026
---------------------------------------------
STRUKTUR PENAWARAN UMUM PERDANA SAHAM
Sebanyak-banyaknya 615,000,000 (enam ratus lima belas juta) saham biasa atas nama yang merupakan saham baru, dengan nilai nominal Rp50,- (lima puluh Rupiah) setiap saham yang mewakili sebanyak 15.06% (lima belas koma nol enam persen) dari modal yang telah ditempatkan dan disetor penuh setelah Penawaran Umum.
Nilai Nominal :
Rp50 per lembar saham
Harga Penawaran :
Rp400 - Rp500 per lembar saham
Jumlah Penawaran Umum :
Sebanyak-banyaknya sebesar Rp246,000,000,000,- (dua ratus empat puluh enam miliar rupiah) sampai dengan Rp307,500,000,000,-(tiga ratus tujuh miliar lima ratus juta rupiah).
Penjamin Pelaksana Emisi Efek:
PT Erdhika Elit Sekuritas
Penjamin Emisi :
Akan ditentukan kemudian
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
PT Nitrasanata Dharma Tbk (JECX)
Code : JECX
Sector : Healthcare
Sub-Sector : Healthcare Providers
---------------------------------------------
PERKIRAAN JADWAL PENAWARAN UMUM PERDANA SAHAM
Perkiraan Tanggal Efektif :
29 Juni 2026
Perkiraan Masa Penawaran Umum :
1 Juli 2026 - 3 Juli 2026
Perkiraan Tanggal Penjatahan :
3 Juli 2026
Perkiraan Tanggal Distribusi Saham :
6 Juli 2026
Perkiraan Tanggal Pencatatan Saham di BEI :
7 Juli 2026
---------------------------------------------
STRUKTUR PENAWARAN UMUM PERDANA SAHAM
Sebanyak-banyaknya 487,983,500 saham biasa, yang terdiri dari (i) 325,322,300 saham baru yang dikeluarkan dari portepel Perseroan yang mewakili 10.00% dan (ii) 162,661,200 saham milik DR.Dr. Waldensius Girsang, SpM(K) yang mewakili 5.00% dari modal ditempatkan dan disetor Perseroan setelah Penawaran Umum Perdana Saham yang mana seluruhnya sejumlah sebanyak-banyaknya 15% dari modal ditempatkan dan disetor Perseroan setelah Penawaran Umum Perdana Saham dengan nilai nominal Rp16,- (enam belas Rupiah) setiap saham.
Nilai Nominal :
Rp16 per lembar saham
Harga Penawaran :
Rp1,200 - Rp1,400 per lembar saham
Jumlah Penawaran Umum :
Sebanyak-banyaknya sebesar Rp683.176.900.000 (enam ratus delapan puluh tiga miliar seratus tujuh puluh enam juta sembilan ratus ribu Rupiah)
Penjamin Pelaksana Emisi Efek:
PT Trimegah Sekuritas
Penjamin Emisi :
Akan ditentukan kemudian
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Company Flash
Read More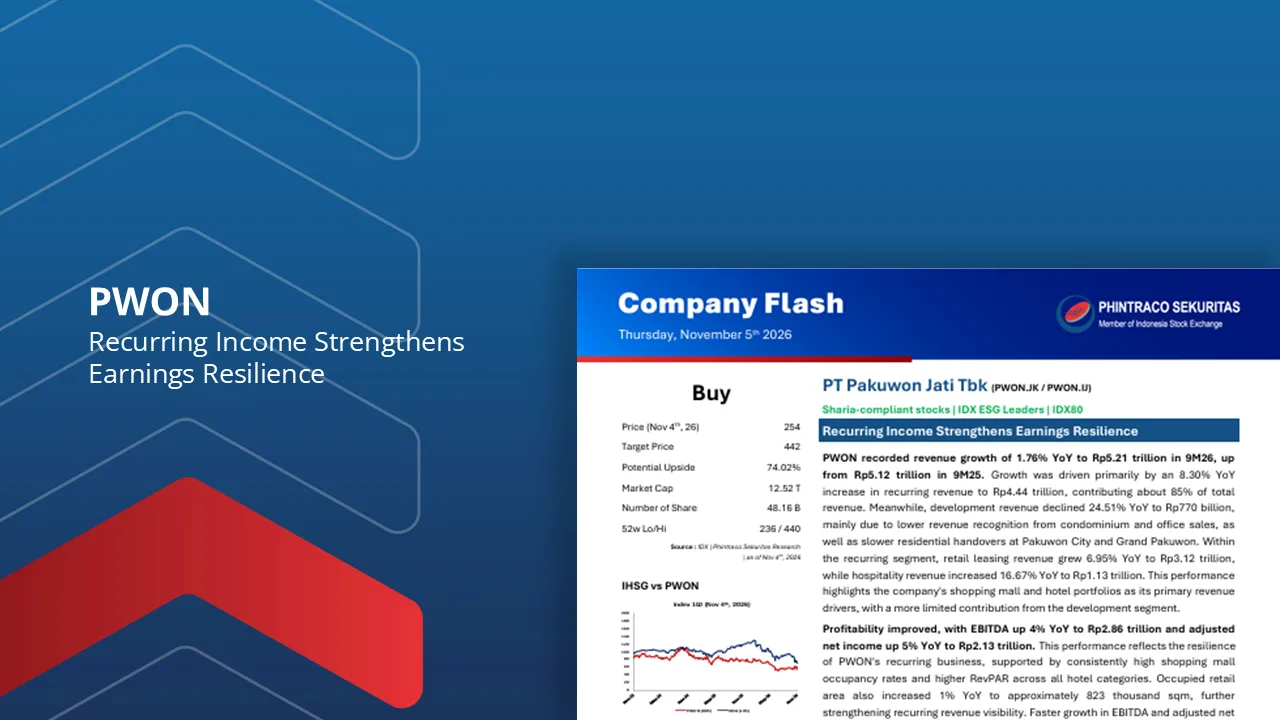
PWON: Recurring Income Strengthens Earnings Resilience
Revenue increased 1.76% YoY to Rp5.21 trillion in 9M26, supported by an 8.30% YoY growth in recurring revenue to Rp4.44 trillion, contributing approximately 85% of total revenue.
Development revenue declined 24.51% YoY to Rp770 billion, while retail leasing and hospitality revenue grew 6.95% and 16.67% YoY, respectively.
EBITDA grew 4% YoY to Rp2.86 trillion, while adjusted net income increased 5% YoY to Rp2.13 trillion, reflecting the resilience of PWON's recurring business and operational efficiency.
Marketing sales declined 10.19% YoY to Rp811 billion in 9M26, with the VAT incentive (PPN DTP) contributing approximately 59% of residential marketing sales.
Three key development projects with a total investment value of Rp12.3 trillion are expected to add 190 thousand sqm of retail NLA and 1,582 hotel rooms, supported by a 503.8ha land bank for future expansion.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
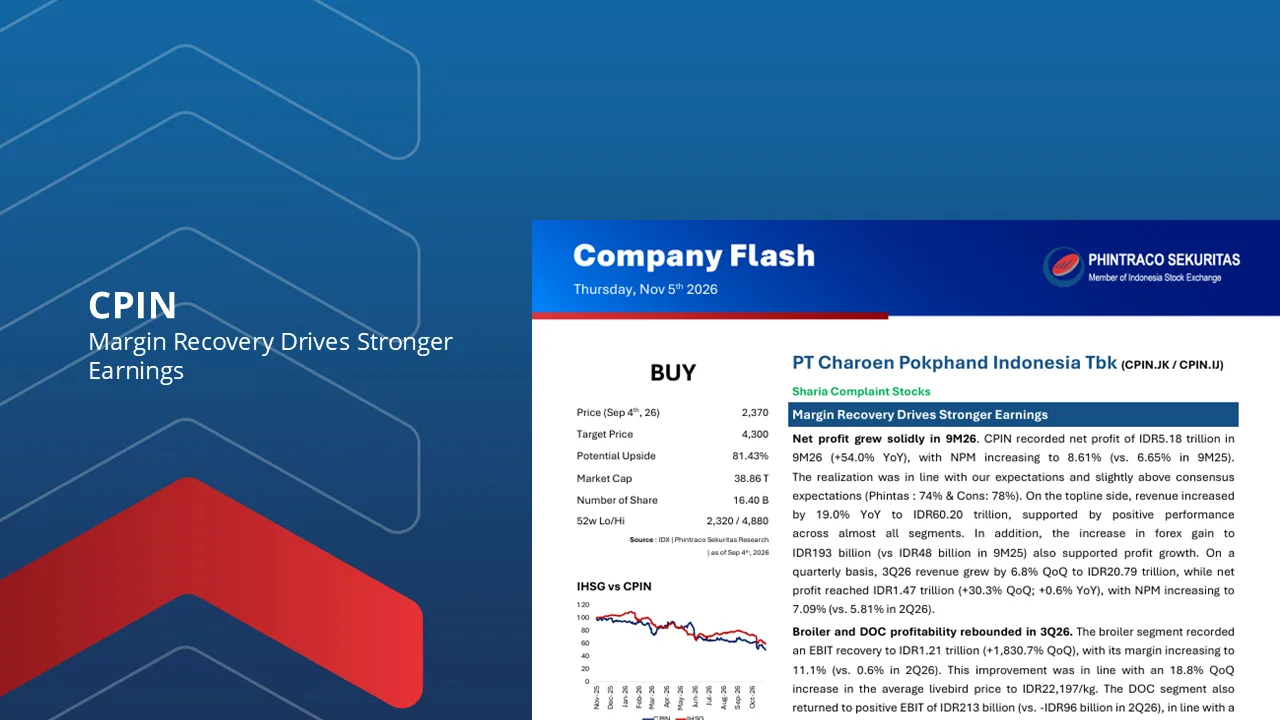
CPIN: Margin Recovery Drives Stronger Earnings
Phintraco Sekuritas Company Flash | 5 November 2026
PT Charoen Pokphand Indonesia Tbk – CPIN.IJ
Aditya Prayoga
>Solid Earnings Growth in 9M26. CPIN recorded revenue of IDR60.20 trillion (+19.0% YoY) and net profit of IDR5.18 trillion (+54.0% YoY) in 9M26. Net profit margin improved to 8.61% (vs. 6.65% in 9M25), with earnings realization reaching 74.1% of Phintraco's FY26 estimates and 78.0% of consensus. In 3Q26, net profit increased 30.3% QoQ to IDR1.47 trillion, supported by stronger operating performance.
>Broiler and DOC Led the Profitability Recovery. Broiler EBIT rebounded to IDR1.21 trillion in 3Q26 (+1,830.7% QoQ), with its margin improving to 11.1%, supported by an 18.8% QoQ increase in average livebird prices to IDR22,197/kg. DOC also returned to positive EBIT of IDR213 billion (vs. an IDR96 billion loss in 2Q26), following a 34.8% QoQ recovery in DOC prices to IDR6,707/chick. In contrast, Feed EBIT declined 25.5% QoQ to IDR923 billion amid higher input costs.
>Manageable COGS Supported Margin Recovery. 3Q26 COGS increased only 1.4% QoQ, below revenue growth of 6.8% QoQ. Consequently, gross profit rose 43.4% QoQ to IDR3.57 trillion, while GPM improved to 17.17% (vs. 12.79% in 2Q26). Operating profit also increased 80.2% QoQ to IDR2.18 trillion, lifting OPM to 10.48% from 6.21% in the previous quarter.
>CPIN trades at 5.4x FY26F P/E, around -1 standard deviation from its five-year average, representing an approximately 50% discount. The 47% YTD share price correction offers an attractive entry point.
>Key risks include weaker livebird and DOC prices, higher feed raw material costs, particularly corn and soybean meal (SBM), and slower consumer purchasing power recovery.
By PHINTRACO SEKURITAS | Research
-Disclaimer On-
Baca Laporan
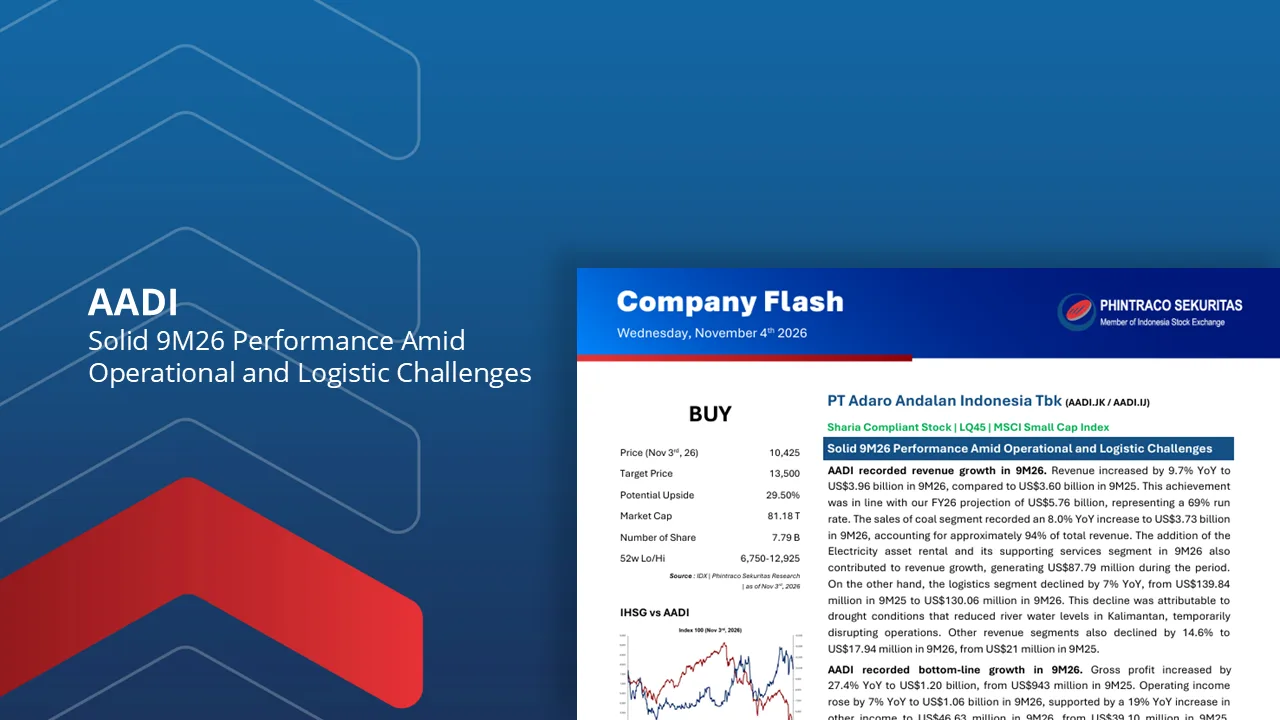
AADI : Solid 9M26 Performance Amid Operational and Logistic Challenges
AADI recorded revenue growth in 9M26. Revenue increased by 9.7% YoY to US$3.96 billion, achieving a 69% run rate against our FY26 projection. Growth was primarily supported by an 8.0% YoY increase in coal sales revenue to US$3.73 billion and the contribution from the newly added power asset leasing and supporting services segment, which generated US$87.79 million. However, logistics revenue declined by 7% YoY to US$130.06 million due to drought-related disruptions in Kalimantan, while other revenue decreased by 14.6% YoY to US$17.94 million.
AADI recorded bottom-line growth in 9M26. Gross profit increased by 27.4% YoY to US$1.20 billion, while operating income rose by 7% YoY to US$1.06 billion. Consequently, net profit grew by 16.3% YoY to US$683.3 million. However, tax expenses surged by 90% YoY, primarily reflecting the divestment of its 47.99% stake in Kestrel Coal Group, completed in 3Q26.
AADI completed the Kestrel Coal Resources divestment in 3Q26. The transaction generated initial proceeds of US$814.12 million, with additional contingent cash consideration of up to US$500 million over five years, subject to annual metallurgical coal price thresholds. The divestment is expected to strengthen the company's cash position and provide potential upside for dividend distributions. Meanwhile, coal sales volume declined by 3% QoQ to 17.9 million tons due to logistical constraints amid lower water levels in the Barito River, while ASP decreased by 1% QoQ to US$75.2/ton.
Key risks include coal regulatory uncertainty, prolonged drought conditions in Kalimantan that could disrupt operations, and the full implementation of exports through PT DSI.
By PHINTRACO SEKURITAS | Research
-Disclaimer On -
Baca Laporan
Company Update
Read More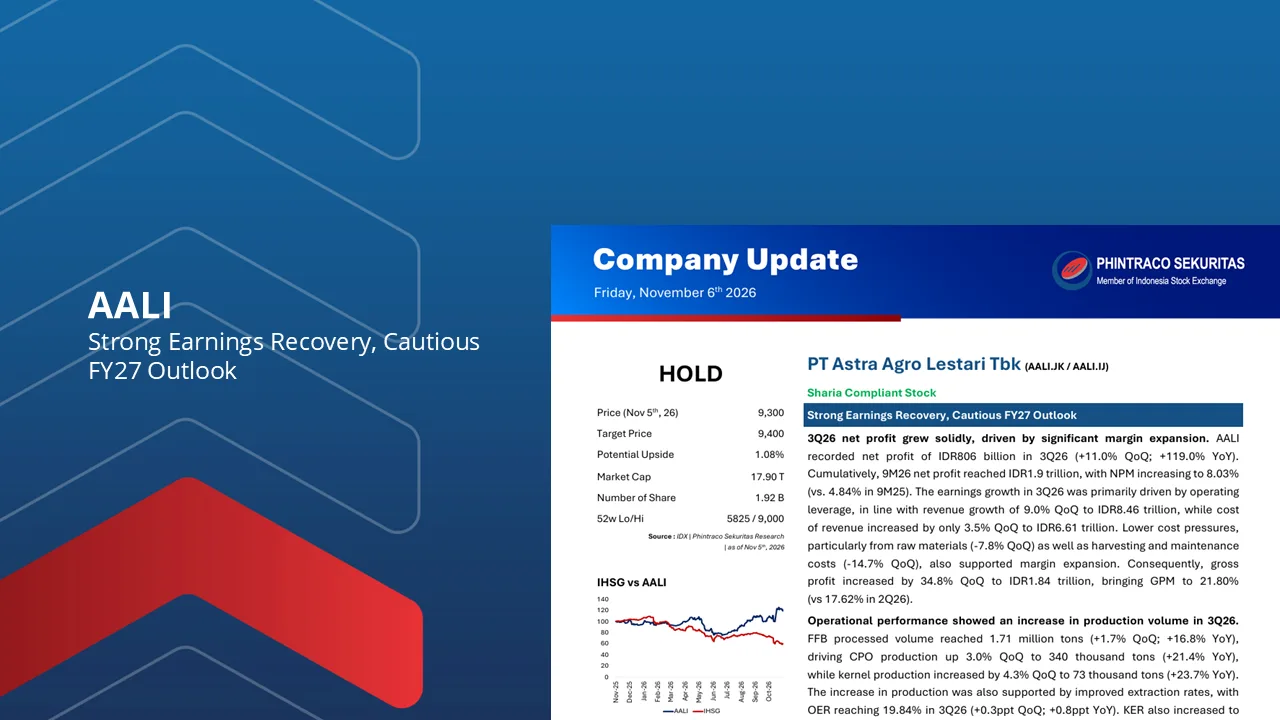
AALI: Strong Earnings Recovery, Cautious FY27 Outlook
Phintraco Sekuritas Company Update | 6 November 2026
PT Astra Agro Lestari Tbk – AALI.IJ
Aditya Prayoga
AALI: Strong Earnings Recovery, Cautious FY27 Outlook
>Strong Earnings Growth on Margin Expansion. AALI recorded 3Q26 net profit of IDR806 billion (+11.0% QoQ; +119.0% YoY), bringing 9M26 net profit to IDR1.9 trillion and NPM to 8.03% (vs. 4.84% in 9M25). Revenue grew 9.0% QoQ to IDR8.46 trillion, while cost of revenue increased only 3.5% QoQ, supported by lower raw material (-7.8% QoQ) and harvesting and maintenance costs (-14.7% QoQ). Consequently, GPM expanded to 21.80% from 17.62% in 2Q26.
>Higher Production Supported by Export Sales. FFB processed volume rose 1.7% QoQ to 1.71 million tons, lifting CPO production by 3.0% to 340k tons and kernel production by 4.3% to 73k tons. Total CPO and derivatives sales increased 2.7% QoQ to 453k tons, driven by export sales growth of 50.0% to 189k tons, while local sales declined 16.2% to 264k tons.
>More Conservative FY27F Outlook Amid El Niño. We lower FY27F revenue, gross profit, and operating profit estimates by 1.66%, 1.50%, and 1.34%, respectively, reflecting potential lower FFB productivity following El Niño in 2H26. Lower FFB availability could constrain CPO production and sales volume, reducing FY27F net profit estimate by 0.76% to IDR1.71 trillion. Conversely, we raise FY26F net profit estimate by 51.93% to IDR2.39 trillion following stronger-than-expected 9M26 performance.
>Key risks include: (1) global CPO price volatility, (2) El Niño-related production disruptions, and (3) higher fertilizer and labor costs.
By PHINTRACO SEKURITAS | Research
-Disclaimer On-
Baca Laporan
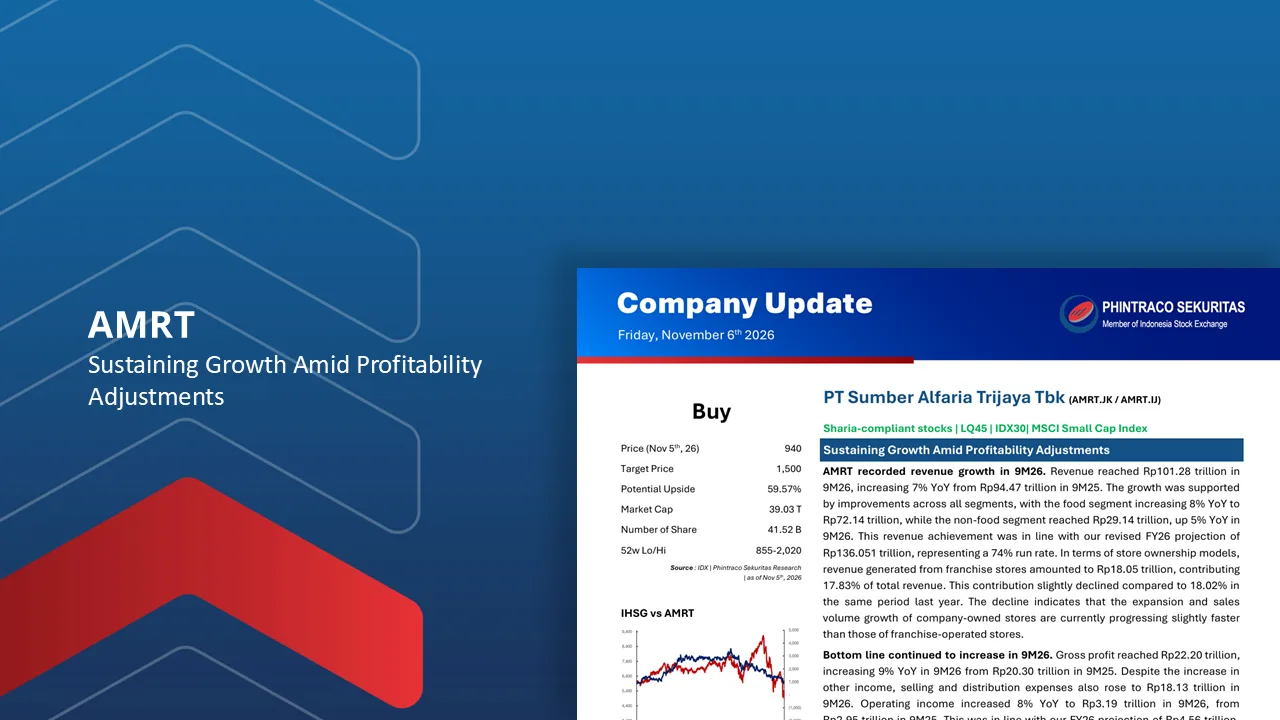
AMRT : Sustaining Growth Amid Profitability Adjustments
AMRT's 9M26 revenue increased 7% YoY to Rp101.28 trillion, supported by growth across food (+8%) and non-food (+5%) segments, with a 74% run rate against our revised FY26 estimate. Franchise revenue contributed 17.83% of total revenue, slightly declining YoY.
Gross profit rose 9% YoY to Rp22.20 trillion, while operating income increased 8% YoY to Rp3.19 trillion. Net income grew 6% YoY to Rp2.55 trillion. We lowered our FY26 net income forecast from Rp4.08 trillion to Rp3.67 trillion, as 9M26 realization reached only 63% of our initial estimate.
AMRT continued expanding its store network, particularly outside Java, targeting approximately 800 new Alfamart stores in 2026. Despite potential competition from Koperasi Desa Merah Putih, AMRT's operational performance remained solid. The Philippines also offers long-term growth potential, with 200–250 additional stores targeted.
We revised our valuation and projection for FY26 onwards, with key risks including weakening consumer purchasing power, Rupiah depreciation, and potential foreign investor capital outflows.
By PHINTRACO SEKURITAS | Research
-Disclaimer On -
Baca Laporan
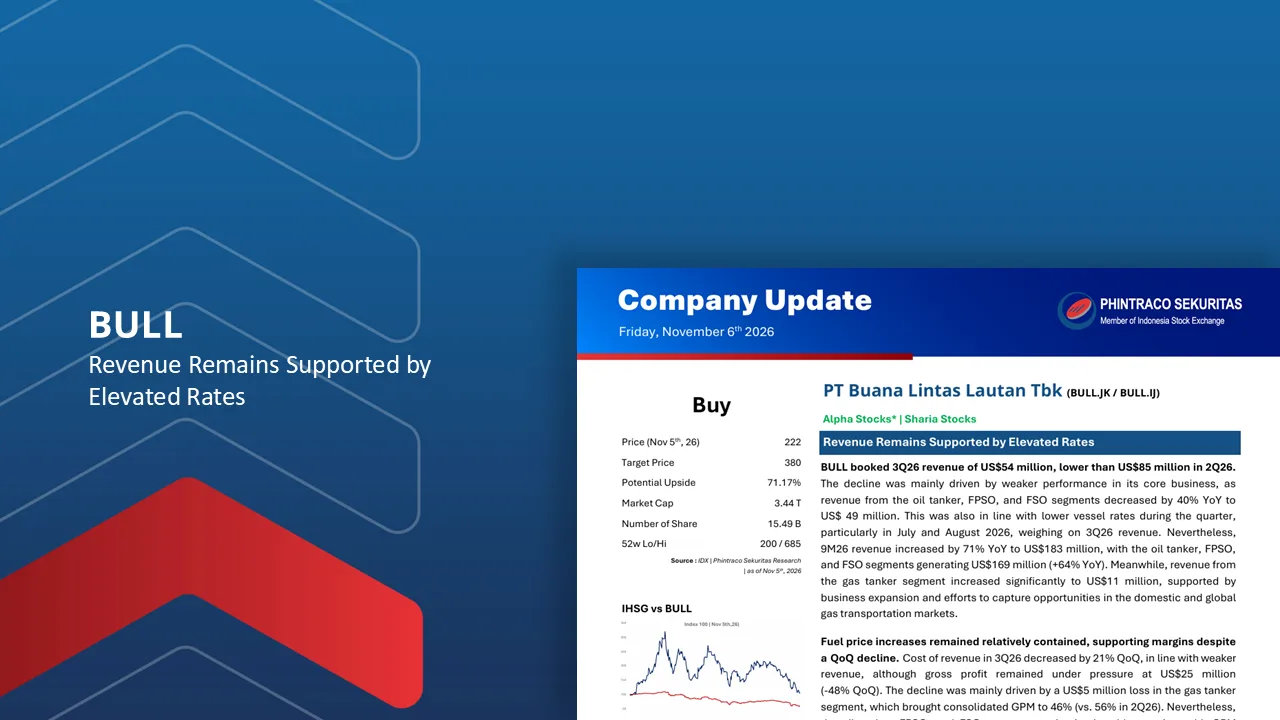
BULL: Revenue Remains Supported by Elevated Rates
BULL booked 3Q26 revenue of US$54 million, down from US$85 million in 2Q26, mainly due to weaker performance in the oil tanker, FPSO, and FSO segments amid lower vessel rates. Nevertheless, 9M26 revenue increased by 71% YoY to US$183 million, supported by these segments, which contributed US$169 million (+64% YoY), while the gas tanker segment generated US$11 million.
3Q26 gross profit decreased by 48% QoQ to US$25 million, mainly due to a US$5 million loss from the gas tanker segment, bringing consolidated GPM to 46%. However, 9M26 gross profit increased by 235% YoY to US$91 million, with GPM improving to 50% (vs. 25% in 9M25) and EBITDA reaching US$99 million (+180% YoY).
We expect vessel rates to remain above pre conflict levels in 4Q26, supporting revenue, although elevated rates may not persist in the longer term. Strong fleet utilization, FSO and FPSO contracts, and an expected recovery in the gas tanker segment should support BULL's operational performance.
We estimate FY26F revenue at US$235 million (+62% YoY), gross profit at US$113 million, and net profit at US$96 million. We maintain our BUY rating with a fair value of IDR 380/share, implying FY26F/FY27F EV/EBITDA of 3.26x/2.74x. Key Risks: Tanker charter rate fluctuations, dependence on oil and gas transportation demand, and shipping regulatory changes.
By PHINTRACO SEKURITAS | Research
– Disclaimer On –
Baca Laporan
Sectoral Update
Read More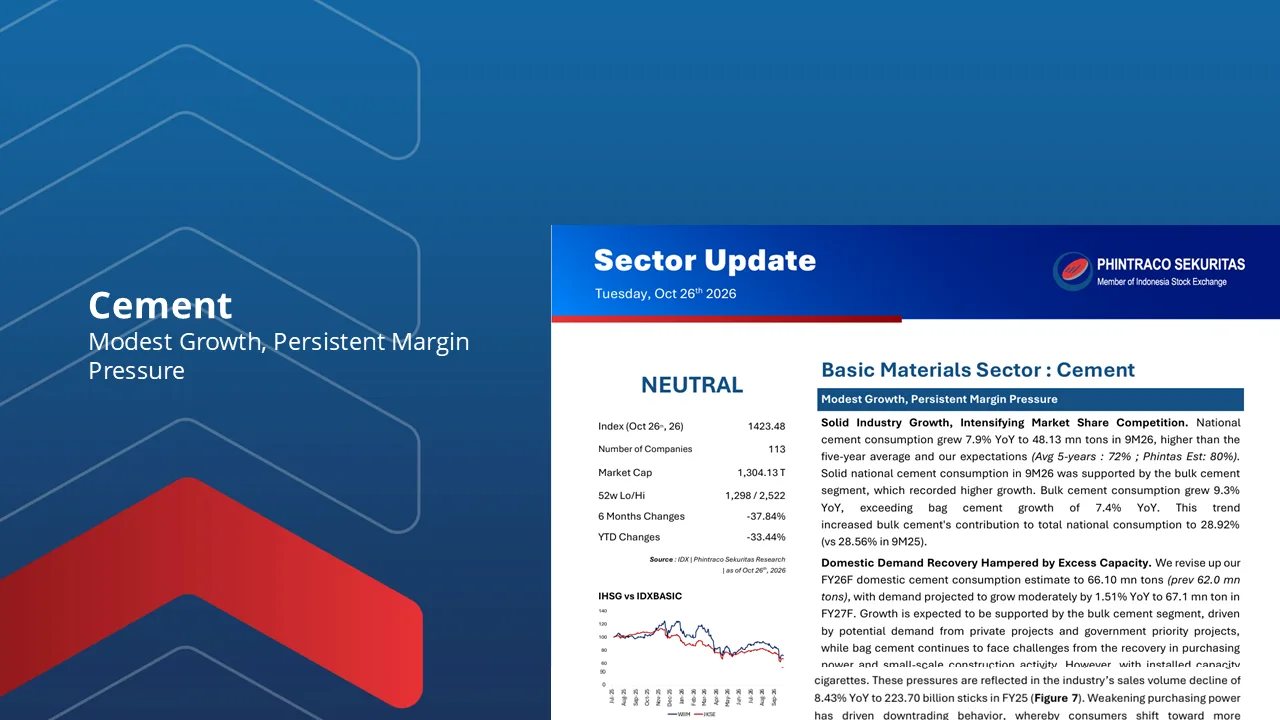
Cement Sector: Modest Growth, Persistent Margin Pressure
Phintraco Sekuritas Sector Update
Cement Sector
Aditya Prayoga
Cement Sector: Modest Growth, Persistent Margin Pressure
>National cement consumption grew 7.9% YoY to 48.13 million tons in 9M26, exceeding the five-year average and our expectations. Growth was supported by the bulk cement segment, which expanded 9.3% YoY, outpacing bag cement growth of 7.4% YoY. Consequently, bulk cement's contribution to total national consumption increased to 28.92%, from 28.56% in 9M25.
>We revised up our FY26F domestic cement consumption estimate to 66.10 million tons from 62.0 million tons, reflecting solid sales realization through 9M26. However, demand growth is expected to normalize in FY27F, with consumption projected to reach 67.1 million tons (+1.51% YoY). Despite the gradual recovery, installed capacity of approximately 120 million tons per year is expected to keep industry utilization at only 55.9% in FY27F, leaving oversupply as a structural challenge.
>Margin recovery is expected to remain constrained by elevated input and logistics costs. ASP increases are projected at only 1%-2% YoY, while COGS per ton could rise by more than 2% YoY. Although Bloomberg projects average Brent crude oil prices of USD 92.41/bbl and coal prices of around USD 120/MT in FY27F, geopolitical risks could keep energy prices elevated. The implementation of the Zero ODOL policy from January 2027 could further increase logistics costs per ton, adding pressure to cement producers' margins.
> Upside risks include stronger consumer purchasing power, accelerated infrastructure projects, lower energy prices, and better-than-expected ASP realization. Downside risks include prolonged oversupply, intensifying price competition, higher-than-expected energy and distribution costs, delays in infrastructure projects, and weaker domestic cement demand.
By PHINTRACO SEKURITAS | Research
— Disclaimer On —
Baca Laporan
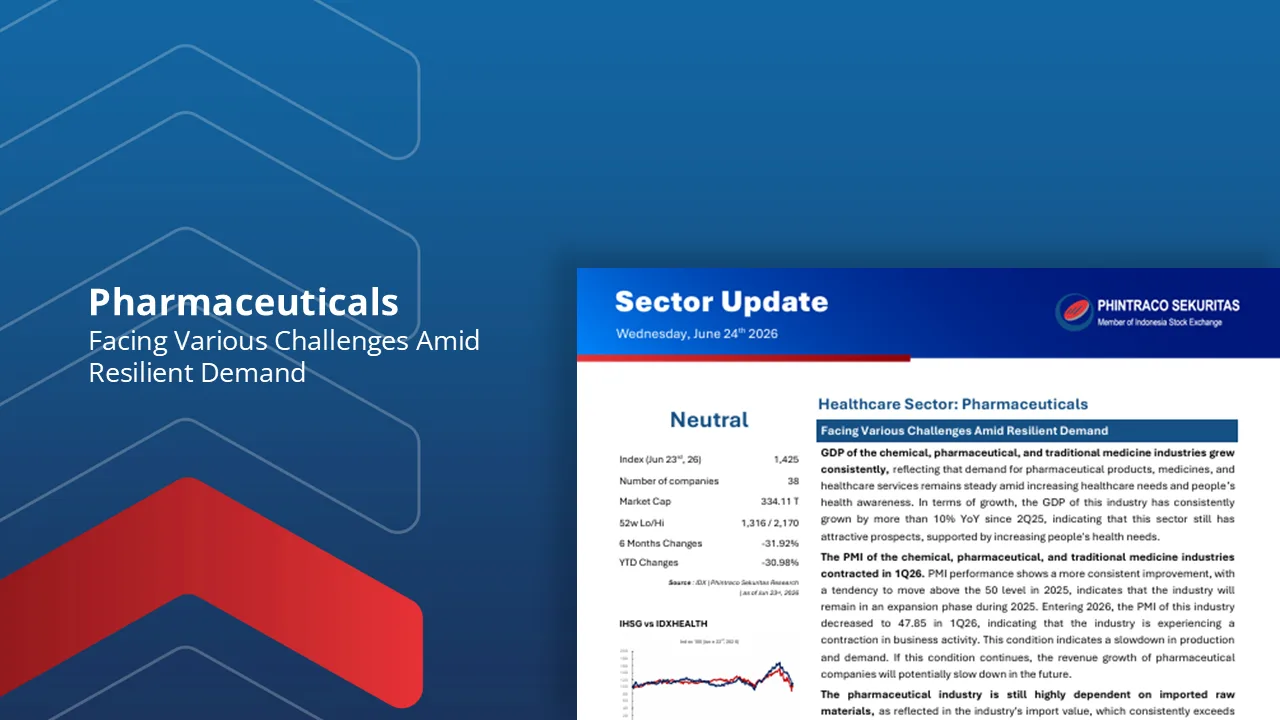
Pharmaceuticals Sector: Facing Various Challenges Amid Resilient Demand
GDP of the chemical, pharmaceutical, and traditional medicine industries grew consistently, reflecting that demand for pharmaceutical products, medicines, and healthcare services remains steady amid increasing healthcare needs and people’s health awareness.
The PMI of the chemical, pharmaceutical, and traditional medicine industries contracted in 1Q26. This condition indicates a slowdown in production and demand. If this condition continues, the revenue growth of pharmaceutical companies will potentially slow down in the future.
The pharmaceutical industry is still highly dependent on imported raw materials, as reflected in the industry's import value, which consistently exceeds its export value. This condition has caused the sector’s trade balance to consistently experience a deficit.
The performance of the pharmaceutical companies in our coverage
is mixed. KLBF booked revenue growth of 10.13% YoY in 1Q26. This growth was driven by increased sales across all business segments.
Downside risks in this sector include a more-than-expected weakening of purchasing power, restrictions on expansion, and intense competition with e-commerce platforms. Meanwhile, SIDO booked a revenue decrease of 18.83% YoY in 1Q26, primarily due to SIDO’s inventory normalization efforts in its distribution channels.
Downside risks in this sector include dependence on imported raw materials, the risk of changes in pharmaceutical regulations, and intense competition between industry players.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
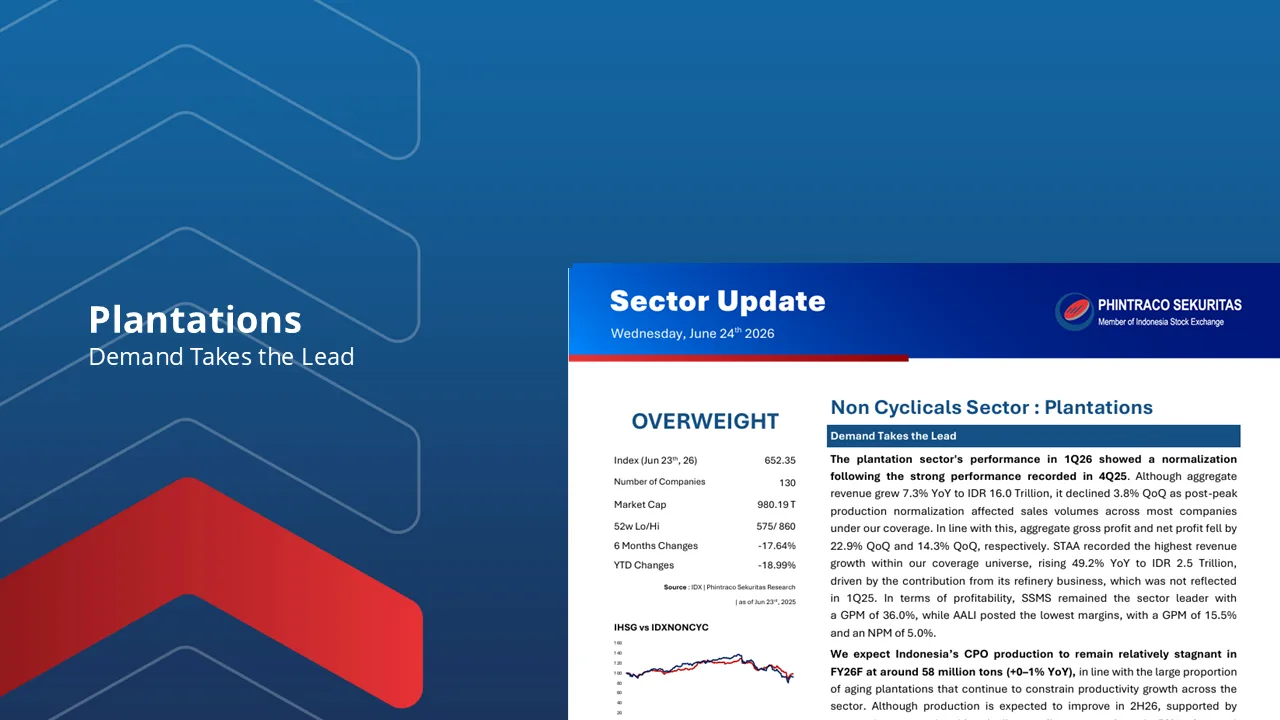
Plantation: Demand Takes the Lead
**Phintraco Sekuritas Sector Update**
**Plantation Sector**
**Aditya Prayoga**
> The plantation sector's performance in 1Q26 showed a quarterly normalization following the strong performance recorded in 4Q25. Aggregate revenue grew 7.3% YoY to IDR 16.0 Trillion, but declined 3.8% QoQ as the peak production and harvesting season came to an end, resulting in lower sales volumes across most companies under our coverage. A similar trend was reflected in aggregate gross profit and net profit, which declined by 22.9% QoQ and 14.3% QoQ, respectively.
> STAA recorded the strongest growth within our coverage universe, with revenue rising 49.2% YoY to IDR 2.5 Trillion, driven by the contribution from its refinery business, which was not reflected in 1Q25. However, its quarterly performance also normalized, with revenue and net profit declining by 20.0% QoQ and 31.6% QoQ, respectively. In terms of profitability, SSMS remained the sector leader with a GPM of 36.0%, while AALI posted the lowest margins, with a GPM of 15.5% and an NPM of 5.0%.
>We expect Indonesia’s CPO production to remain relatively stagnant in FY26F at around 58 million tons (+0–1% YoY) While 2H26 production is likely to be slightly stronger than 1H26, supported by seasonal patterns where approximately 53% of annual output is generated in the second half, we believe the improvement will be largely seasonal in nature.
>Looking ahead, the potential emergence of El Niño in 2H26 remains a factor worth monitoring. Nevertheless, we believe the risk to FY26F production remains relatively limited, given that weather-related impacts on palm oil productivity typically materialize with a lag of 9–12 months. As a result, any stronger-than-expected El Niño event is more likely to affect the FY27F production outlook rather than FY26F.
> On the demand side, the implementation of the mandatory B50 biodiesel program, effective from 1 July 2026, is expected to significantly increase domestic CPO consumption. Based on the government’s simulation, CPO demand for biodiesel could rise to approximately 17.9 million tons (+33.4%), creating additional demand of around 4.35 million tons compared to the current B40 scheme. As domestic demand growth is expected to outpace supply growth, market balances could tighten further and support CPO prices.
> External demand is also expected to remain supportive. India's seasonal restocking cycle ahead of the Diwali festival is likely to strengthen imports during 2H26, while recent data suggest that China's palm oil imports are beginning to recover after several years of decline. We believe these factors should help absorb additional supply entering the market during the second half of the year.
>Downside risks to our view include: (1) volatility in CPO and other vegetable oil prices, (2) changes in biodiesel or export policies, and (3) higher-than-expected fertilizer and operating costs resulting from geopolitical tensions and global supply chain disruptions.
Full Report : https://phintracosekuritas.com/
By PHINTRACO SEKURITAS | Research
– Disclaimer On –
Baca Laporan
Macro Flash
Read More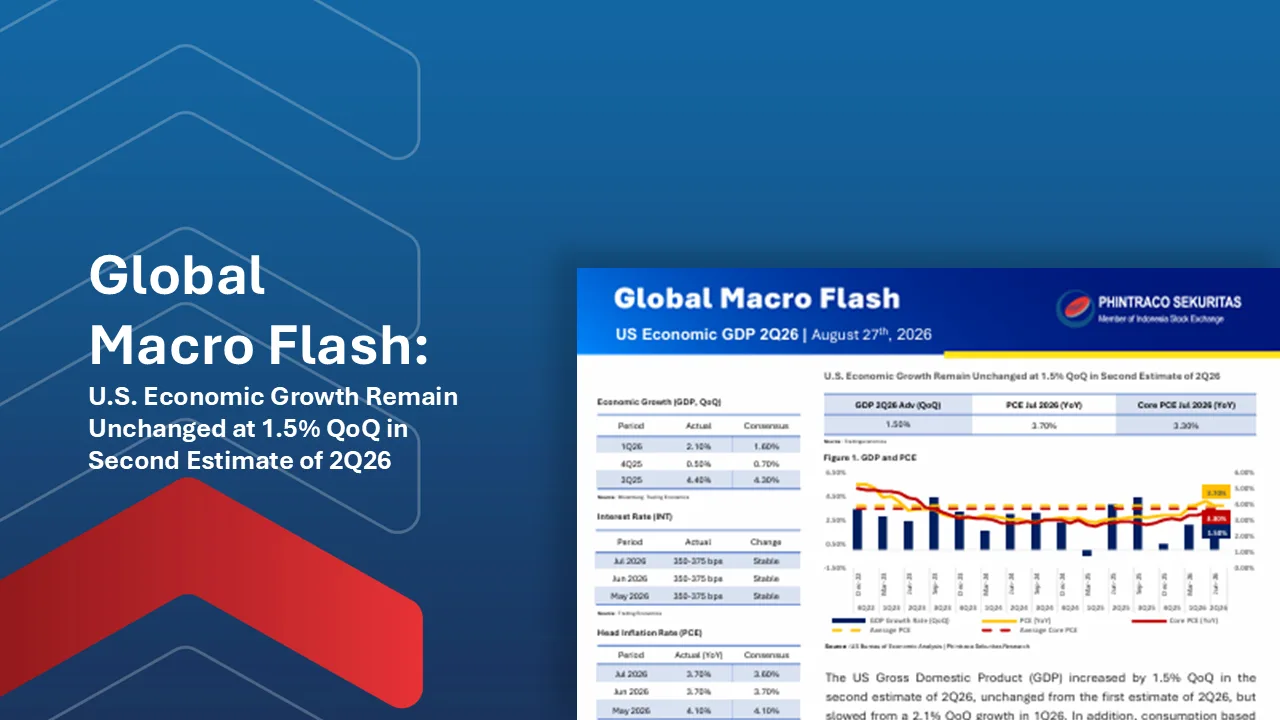
U.S. Economic Growth Remain Unchanged at 1.5% QoQ in Second Estimate of 2Q26
GDP Growth Rate 2Q26 Adv. Est: 1.50% QoQ
PCE July 2026: 3.70% YoY
Core PCE July 2026: 3.30% YoY
The US Gross Domestic Product (GDP) rose by 1.5% QoQ in the second estimate of 2Q26, unchanged from the first estimate of 2Q26, but slowed from a 2.1% QoQ growth in 1Q26. Consumption-based inflation indicators were recorded stable as shown by Personal Consumption Expenditure (PCE) of 3.7% YoY and Core PCE of 3.3% YoY in July 2026, but still well above the Fed’s 2% inflation target. In addition, the US personal income rose for nine consecutive months to US$27.11 trillion or grew by 0.4% MoM in July 2026 from a 0.2% MoM growth in June 2026, reflected the resilience of the US economy amid energy disruption and high borrowing costs.
By PHINTRACO SEKURITAS | Research
-Disclaimer On-
Baca Laporan
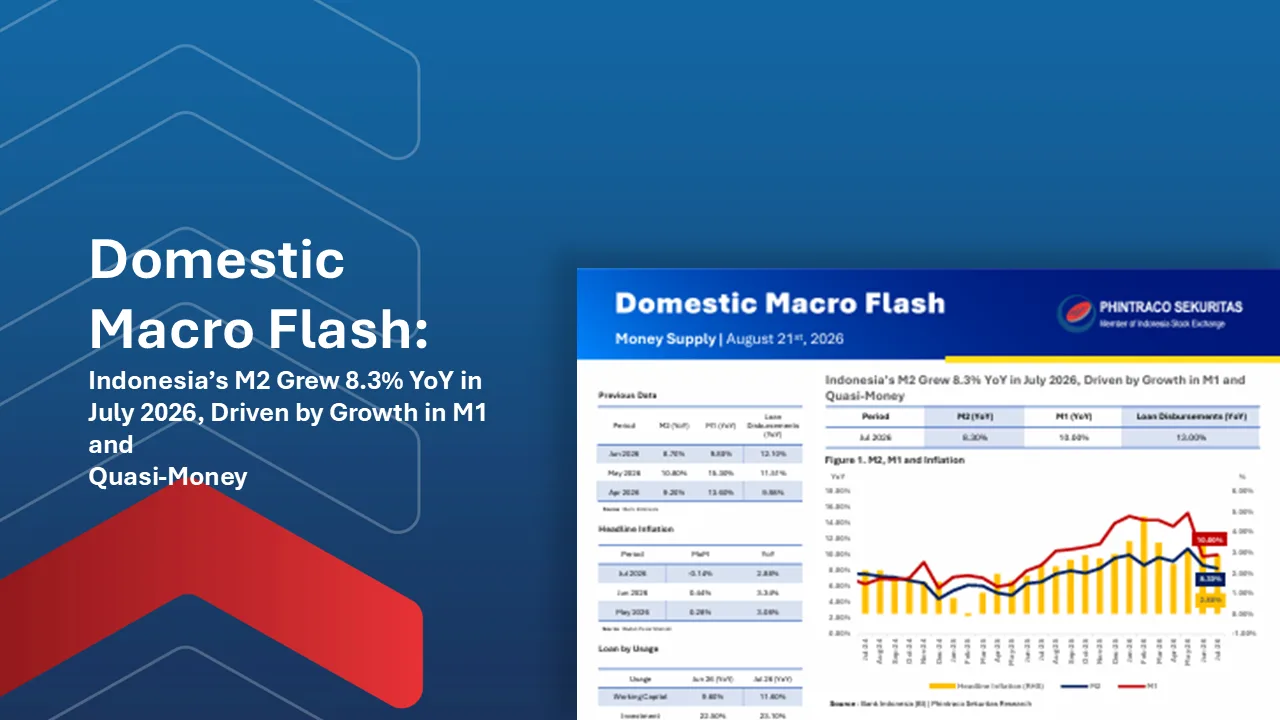
Indonesia’s M2 Grew 8.3% YoY in July 2026, Driven by Growth in M1 and Quasi-Money
Broad money supply (M2) was recorded at IDR 10,371.1 trillion, growing by 8.3% YoY in July 2026, slowing from 8.7% YoY growth in June 2026. By component, the growth was driven by both narrow money supply (M1) and quasi-money. M1 was recorded at IDR 5,908.7 trillion, growing by 10.0% YoY in July 2026, while quasi-money stood at IDR 4,375.9 trillion, growing by 5.6% YoY. In addition, M2 growth in July 2026 was primarily supported by loan growth of 13.0% YoY and a 4.6% YoY increase in net claims on the central government.
Baca Laporan

Bank Indonesia Keeps BI Rate at 5.75% in August 2026
BI Rate: 5.75%
Deposit Facility: 4.75%
Lending Facility: 6.50%
BI maintained the BI Rate at 5.75% while prioritizing Rupiah stability and inflation control, and continued to support sustainable economic growth through monetary and macroprudential measures. The unchanged 200 bps BI Rate–FFR spread, together with foreign fund flows shifting from equities toward SBN and SRBI, indicates investors’ preference for relatively lower-risk domestic assets amid global uncertainty. Going forward, BI is expected to remain focused on exchange rate stability, liquidity management, and maintaining the attractiveness of Indonesian assets to support sustainable economic growth.
Baca Laporan
Market Outlook
Read More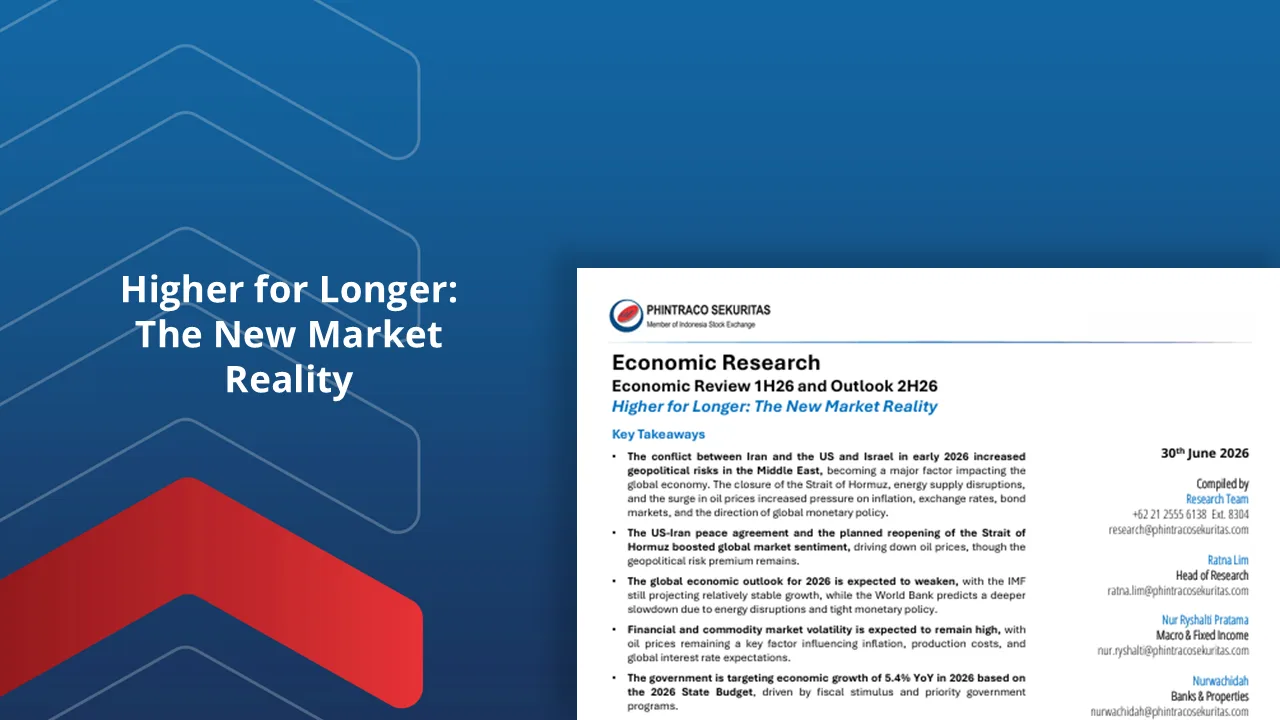
Higher for Longer: The New Market Reality
Middle East geopolitical tensions disrupted global energy supply, pushing up oil prices and increasing pressure on inflation, exchange rates, and global monetary policy.
The US–Iran peace agreement and the planned reopening of the Strait of Hormuz improved market sentiment and eased oil prices, although geopolitical risks remain.
Global growth is expected to moderate in 2026, with persistent market volatility driven by energy prices, inflation, and higher-for-longer interest rates.
Indonesia targets 5.4% GDP growth in 2026, supported by fiscal stimulus, while inflation is expected to remain within Bank Indonesia's target range in 2H26.
Bank Indonesia is expected to maintain a tight monetary stance amid Rupiah depreciation, global rate pressures, and inflation risks.
Fiscal conditions remain manageable, with the 2026 budget deficit reaching 0.7% of GDP by May, still well below the full-year target despite widening from last year.
Foreign investors are likely to remain cautious, as the market awaits MSCI's market accessibility review and S&P's sovereign credit rating assessment.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Global Economic Research : Embracing the Economic Dynamics of 2026
Global economic growth is expected to keep slowing amid high global uncertainty. This situation continues to weigh on trade, investment, and overall economic performance.
U.S. President Donald Trump’s import tariff policies have created uncertainty, though recent negotiations indicate potential progress. Efforts toward a U.S.–China trade deal, including partial tariff cuts and delayed export restrictions, are offset by new risks from stricter transshipment monitoring.
Artificial Intelligence (AI) is transforming the global economy by automating production and addressing labor shortages. The integration of AI and robotics enhances industrial efficiency and supports productivity through adaptive labor and migration policies.
Global inflation pressures have eased except in the U.S., Europe, and the U.K., driven by import tariffs and strong demand. Several major central banks have started to cut interest rates, while others remain cautious to maintain stability.
Global fiscal conditions are becoming more fragile due to geopolitical tensions, U.S. tariff policies, and high public debt. Expansionary fiscal policies and rising interest rates are increasing debt costs and limiting fiscal space.
Geopolitical tensions continue to disrupt supply chains, raising energy and food prices. However, global commodity prices in 2025 show mixed trends, influenced by weaker demand, supply disruptions, and climate change.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Indonesia Economic Research: Embracing the Economic Dynamics of 2026
Indonesia's economy is projected to grow 5.0%-5.2% YoY in 2026. Indonesia's economic growth is expected to accelerate in 2026, in line with expectations of improving global conditions and increased domestic investment activity.
Consumer confidence index and retail sales are expected to remain positive in 2026. Supported by the government's stimulus program, assuming controlled inflation and consumption incentive.
Inflation in 2026 is expected to remain within BI's target range of 2.5% ± 1%. This projection is based on relatively stable inflation expectations at low levels, the stability of the Rupiah exchange rate, and synergistic efforts by Bank Indonesia and the Government.
The opportunity for further cuts by Bank Indonesia (BI) Rate remains possible in 2026. This projection is based on relatively stable inflation expectations at low levels, the stability of the Rupiah exchange rate, and synergistic efforts by Bank Indonesia and the Government.
The allocation of government funds in banks has positively influenced national liquidity. By September 2025, the adjusted base money rose to Rp2,152.4 trillion, up from Rp1,961.34 trillion in August 2025.
The 2026 APBN deficit is targeted at 2.68% of GDP. The 2026 APBN targets state revenue at IDR 3,153.6 trillion, comprising IDR 2,357.7 trillion in tax revenue and IDR 336 trillion in customs and excise revenue.
IHSG's conservative level for 2026 is estimated at 9,255 and its aggressive level at 9,883.
Sectoral Coverage: Banks, Properties & Real estate, F&B and Poultry, Retails, Telecommunication, Tower, Coal, Pharmaceuticals, Plantations, Construction, Metals & Mining, Industrial, and Cement.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Monthly Strategy
Read More
Monthly Strategy :Investment Strategies Amid Heightening Market Uncertainty
-November 2026-
Global Highlight: The Fed maintained its policy rate at 3.75%–4.00% in October 2026, in line with market expectations, while leaving the possibility of another rate hike in December amid persistent inflationary pressures. U.S. inflation accelerated, with headline CPI reaching 3.7% YoY and PCE inflation rising to 3.6% YoY in September, driven partly by elevated energy prices, with crude oil remaining above US$100/barrel. Meanwhile, U.S. economic growth strengthened to 3.4% annualized in 3Q26 from 2.2% in 2Q26, supported by robust private investment and household consumption. In other major economies, the ECB and BoJ maintained their policy rates, while China's economic growth improved to 4.5% YoY in 3Q26. Persistent inflation and resilient economic activity could keep global monetary conditions tight.
Indonesia Highlight: Bank Indonesia maintained its policy rate at 5.75% in October 2026, while raising the Deposit Facility Rate by 25 bps to 5.00% to support Rupiah stability. However, the Rupiah continued to weaken, closing at Rp18,132/US$ at the end of October. Inflation eased slightly to 3.23% YoY in October from 3.28% in September, although food inflation accelerated to 4.82% YoY amid El Niño-related supply pressures. On the positive side, manufacturing PMI strengthened to 54.0 in October, its highest level since March 2024, while the trade balance maintained a US$3.36 billion surplus in September. These developments indicate improving manufacturing activity and resilient external trade, although currency depreciation and inflationary pressures remain key concerns.
IHSG View: The IHSG faced significant selling pressure in October 2026, declining 16.7% MoM and 41.52% YTD amid escalating geopolitical tensions, elevated oil prices, Rupiah depreciation, and uncertainty surrounding MSCI's consultation on a potential reclassification of Indonesia from Emerging Market to Standalone Market status. Foreign investors recorded net selling of Rp126.2 trillion in the regular market through the end of October. Although domestic corporate fundamentals remain relatively resilient and equity valuations appear attractive compared with global markets, heightened uncertainty could continue to limit market recovery. We recommend a more selective investment approach, focusing on short-term trading opportunities and gradual accumulation at attractive valuations with limited capital allocation. Diversification into money market and government bond instruments may also help manage portfolio risk.
Sector Allocation:
Metals Mining, Coal, CPO, and Shipping Related. Read more for the Stock Picks.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Equity : Balancing Uncertainty, Gradual Recovery Ahead
-October 2026-
Global Highlight: The Fed raised its policy rate by 25 bps to 3.75%–4.00% in September 2026 amid persistent inflation and higher oil prices. The Fed signaled one potential additional hike in 2026, while the U.S. labor market remained solid with nonfarm payrolls rising by 162k, despite wage growth slowing to 3.1% YoY. Global monetary tightening could further tighten financial conditions and keep bond yields elevated.
Indonesia Highlight: Bank Indonesia kept its policy rate at 5.75% in September 2026 despite the Fed’s rate hike, narrowing the BI Rate–Fed Rate spread to 1.75%, but still above the five-year average. Inflation rose to 3.28% YoY, while manufacturing PMI returned to expansion at 52.4 and the trade surplus widened to US$3.55 billion in August. The 2027 state budget remains expansionary, targeting a 2.4% of GDP deficit and 6.0% economic growth, although high global rates and bond yields could constrain fiscal space.
IHSG View: Global equity markets remain highly volatile amid rising bond yields, oil prices, and geopolitical uncertainty. The IHSG’s direction will be influenced by U.S. inflation and labor data, Fed policy, UST yields, oil prices, and the 3Q26 earnings season. While a rebound remains possible, investors will also monitor the potential Fed rate hike in October and MSCI’s announcement in November. We maintain our IHSG target at 7,000 by end-2026.
Sector Allocation:
Banks, Coal, Metals Mining, Oil & Gas, Retailers, and Industrial. Read more for the Stock pick.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Equity Monthly Strategy : Global Rates Remain Key to Market Direction
-September 2026-
Global Highlight: Global growth remained resilient despite a moderation in the U.S. economy, with real GDP growth slowing to 1.5% in 2Q26 from 2.1% in 1Q26. Meanwhile, U.S. inflation eased to 3.4% YoY in July, although PCE and core PCE remained elevated at 3.7% and 3.3%, respectively, keeping inflation well above the Fed’s 2% target. Persistent inflation alongside moderating growth could reinforce a higher-for-longer Fed policy stance, while keeping the possibility of further rate hikes open.
Indonesia Highlight: Bank Indonesia maintained the BI Rate at 5.75% while strengthening policy measures to support Rupiah stability and sustainable economic growth. Indonesia’s economy grew 5.29% YoY in 2Q26, moderating from 5.61% in 1Q26 amid slower household consumption and government spending, while loan growth remained strong at 13.58% YoY in July. Meanwhile, inflation accelerated to 3.19% YoY in August and manufacturing PMI fell into contraction territory, highlighting moderating domestic activity and downside risks to the 2026 growth outlook.
IHSG View: Global equity markets remained volatile in August 2026 amid rising U.S. Treasury yields, shifting expectations for the Fed’s September decision, and elevated energy prices due to ongoing Middle East tensions. Domestically, the JCI rebounded 4.64% MoM, supported by improving Rupiah performance, easing concerns over the domestic outlook, and reduced foreign selling pressure, although it remained down 24.53% YTD. Going forward, tighter global financial conditions and narrower Indonesia–U.S. yield spreads could continue to pressure capital flows and the Rupiah, favoring a more selective and short term trading approach amid elevated market volatility.
Sector Allocation: Telecommunication, Poultry, Retailers, Coal, Metal Mining, and Oil & Gas. Read more for the Stock pick.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan