Phintas

Phintraco Sekuritas

Phintraco Sekuritas adalah Perusahaan Sekuritas, Anggota Bursa Efek Indonesia yang menyediakan layanan Perantara Pedagang Efek dan Penjamin Emisi Efek. Phintraco Sekuritas berhasil meraih 8 Rekor MURI dan memiliki jaringan yang luas di Indonesia dengan Kantor Cabang dan Galeri Investasi tersebar dari Aceh hingga Papua.

150k

Investor

28

Kantor Cabang

300

Galeri Investasi

150k

Investor

28

Kantor Cabang

300

Galeri Investasi

Profits Left

Our Product

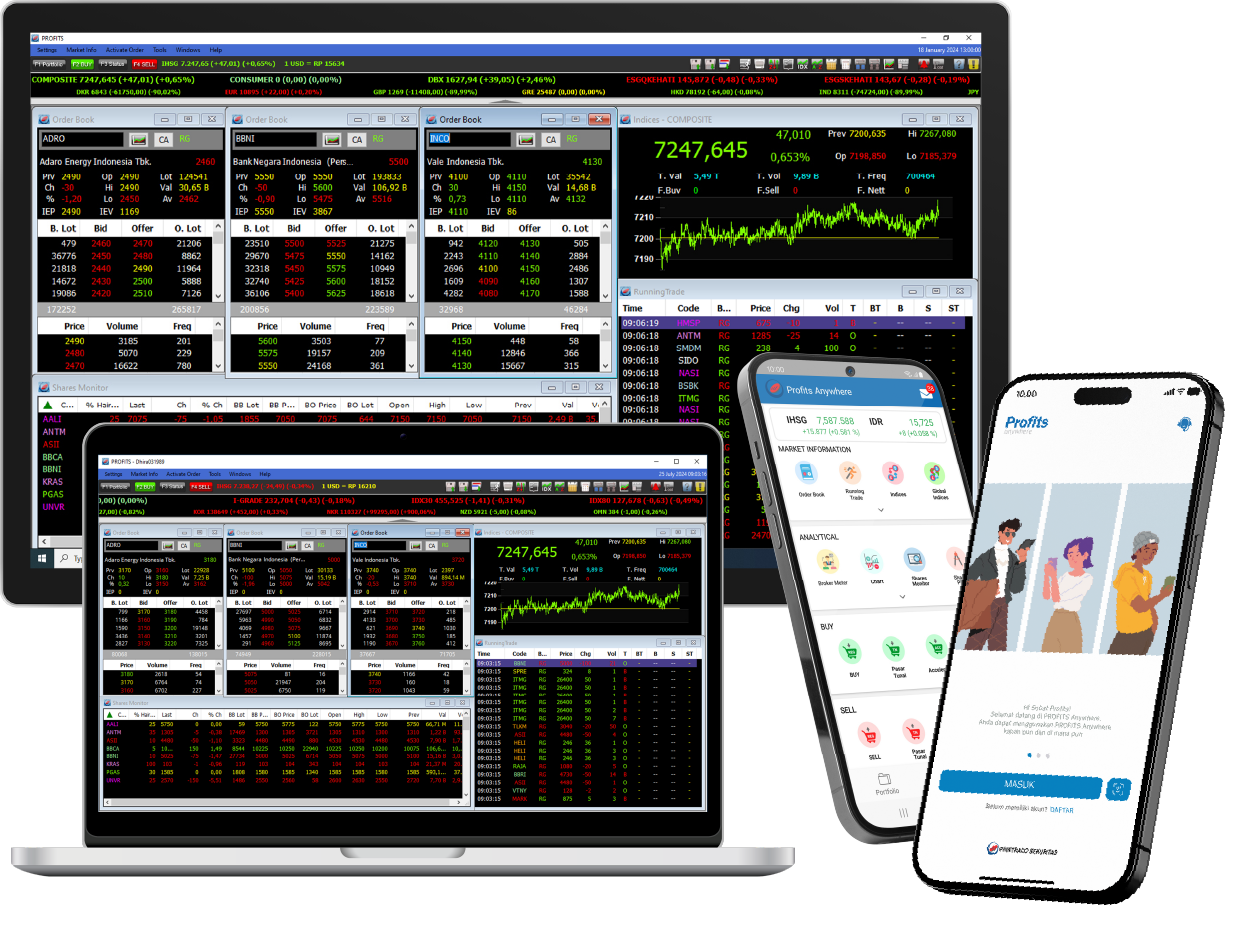
Profits

Investment Breaktrough Beyond Limit.

Institutional Brokerage

Divisi Institutonal Brokerage siap memberikan pelayanan kepada perusahaan atau lembaga yang tertarik untuk berinvestasi.

Selengkapnya

Investment Banking

Phintraco Sekuritas juga memiliki layanan Investment Banking yang dapat membantu memenuhi kebutuhan Perusahaan Anda.

Selengkapnya

Research Report

Research

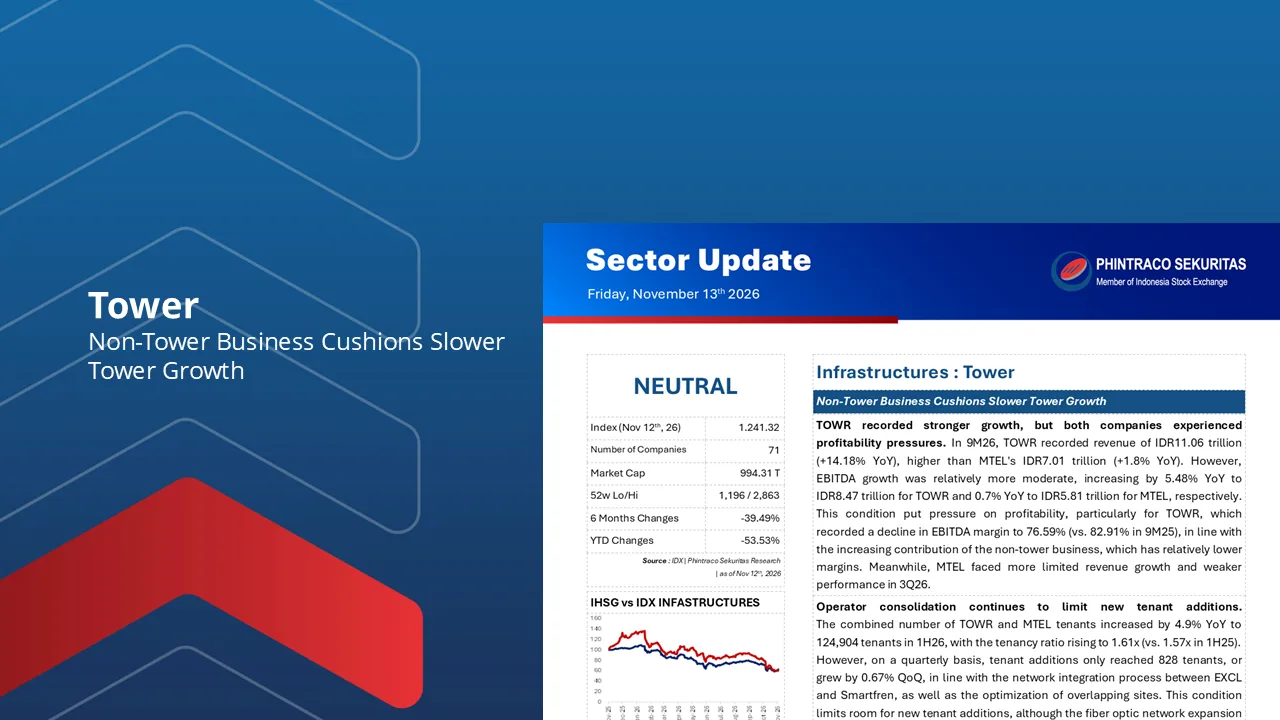
Tower : Non Tower Business Cushions Slower Tower Growth

13 Nov 2026 Sectoral Update

Phintraco Sekuritas Sector Update | 13 November 2026
Tower Sector
Aditya Prayoga

Tower : Non tower business cushions slower tower growth

>TOWR outperformed MTEL in revenue growth, but profitability remained under pressure. In 9M26, TOWR’s revenue increased 14.18% YoY to IDR11.06 trillion, compared with MTEL’s 1.8% YoY growth to IDR7.01 trillion. However, EBITDA growth was slower at 5.48% YoY for TOWR and 0.7% YoY for MTEL, bringing combined EBITDA margin to 78.98% in 9M26.

>TOWR’s stronger revenue growth was accompanied by margin compression. TOWR’s EBITDA margin declined to 76.59% in 9M26 (vs. 82.91% in 9M25), partly reflecting the higher contribution from its lower-margin non-tower business. Meanwhile, MTEL continued to record more moderate revenue growth and weaker performance in 3Q26.

>Operator consolidation continues to constrain tenant additions. The combined number of TOWR and MTEL tenants increased 4.9% YoY to 124,904 in 1H26, with the tenancy ratio improving to 1.61x (vs. 1.57x in 1H25). However, quarterly additions were limited to 828 tenants (+0.67% QoQ), reflecting network integration between EXCL and Smartfren and the optimization of overlapping sites.

>Non-tower businesses are becoming an increasingly important growth driver. Combined non-tower revenue rose 35.0% YoY to IDR3.95 trillion in 1H26, while tower revenue declined 1.4% YoY to IDR7.95 trillion. TOWR led non-tower growth with a 44.5% YoY increase to IDR3.09 trillion, compared with MTEL’s 9.0% YoY growth to IDR858 billion. However, the lower-margin profile of non-tower businesses may weigh on overall profitability as their contribution increases.

>Organic growth remains limited amid operator consolidation, although 5G, FWA, and non-tower expansion provide additional growth opportunities. TOWR offers attractive valuation with non-tower business exposure, while MTEL benefits from lower exposure to operator consolidation and broader tower coverage outside Java.

>Key risks include more aggressive operator consolidation, higher churn and rental rate pressure, weaker-than-expected non-tower monetization, and higher interest rates and operating costs.

By PHINTRACO SEKURITAS | Research
— Disclaimer On —
Baca Laporan
Research

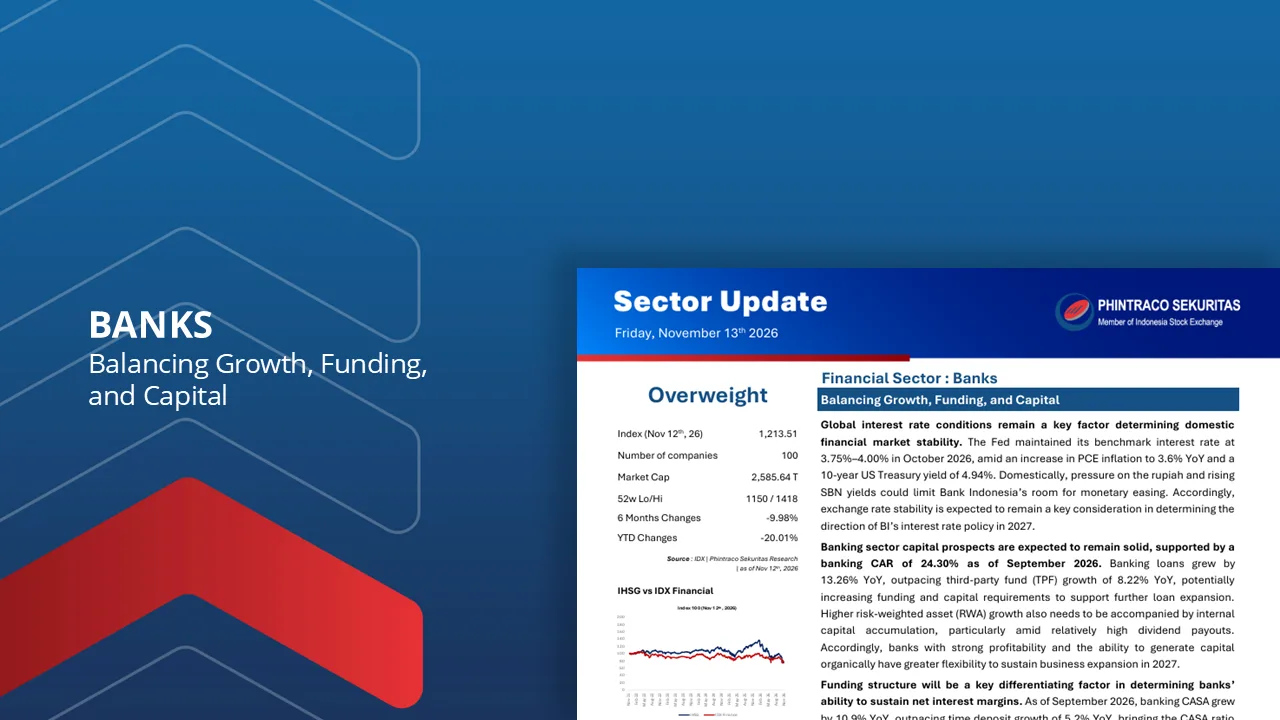
Banks: Balancing Growth, Funding, and Capital

13 Nov 2026 Sectoral Update

Banking loan growth remained resilient, expanding by 13.26% YoY to Rp9,245 trillion in September 2026, although growth moderated from 13.65% in August. Investment loans remained the primary growth driver, increasing by 23.20% YoY.

Funding structure remains a key differentiator, as industry loan growth continued to outpace deposit growth of 8.22% YoY. CASA grew by 10.9% YoY, exceeding the 5.2% growth in time deposits, lifting the industry CASA ratio to 64.9%.

Net interest margin remained under pressure, with the industry NIM declining to 4.29% in September 2026 from 4.56% at the end of 2025. Differences in funding composition and loan repricing capabilities contributed to varying margin performance across banks.

Asset quality remained relatively manageable, with gross NPL improving to 2.07% and Loan at Risk (LaR) declining to 8.50%. However, LaR remained approximately 4.1 times gross NPL, highlighting the need to monitor potential credit migration and provisioning requirements.

Banking sector capitalization remained solid, supported by an industry CAR of 24.30% in September 2026. Strong capital buffers provide support for continued credit expansion, although banks still need to balance risk-weighted asset growth, internal capital generation, and dividend distribution.

By PHINTRACO SEKURITAS | Research
– Disclaimer On –


Baca Laporan
Research

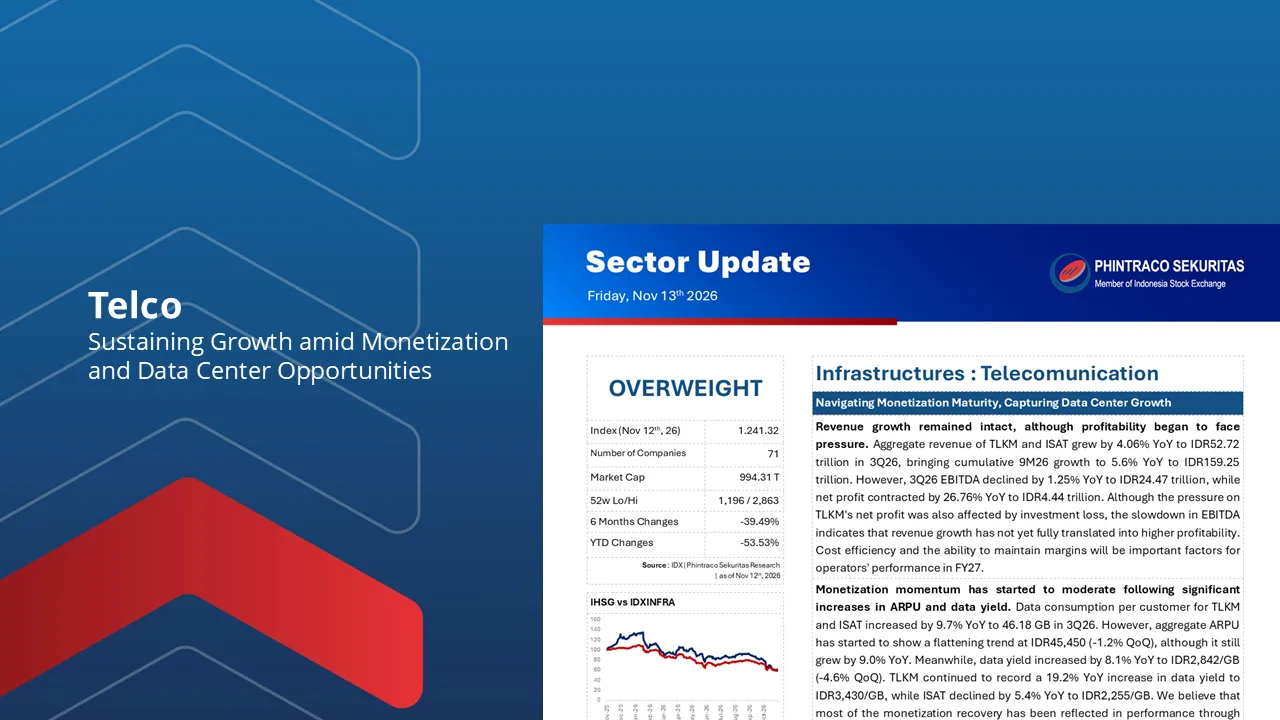
Telco : Sustaining Growth amid Monetization and Data Center Opportunities

13 Nov 2026 Sectoral Update

Phintraco Sekuritas Sector Update | 13 November 2026
Telco Sector
Aditya Prayoga

>Revenue growth remained intact, although profitability faced pressure. Combined revenue of TLKM and ISAT grew 4.06% YoY to IDR52.72 trillion in 3Q26, bringing 9M26 growth to 5.6% YoY to IDR159.25 trillion. However, EBITDA declined 1.25% YoY to IDR24.47 trillion, while net profit contracted 26.76% YoY to IDR4.44 trillion. The slowdown highlights the need for stronger cost efficiency to support profitability in FY27.

>Monetization momentum has started to moderate following significant ARPU and data yield improvements.** Data consumption increased 9.7% YoY to 46.18 GB per customer in 3Q26. However, aggregate ARPU declined 1.2% QoQ to IDR45,450, while data yield fell 4.6% QoQ to IDR2,842/GB. We expect further monetization improvements to become more limited in FY27.

>Indonesia has the potential to capture spillover from regional data center expansion.** Capacity constraints in Singapore and Malaysia, particularly in land and electricity availability, create opportunities for Indonesia to attract regional investments. Indonesia currently has 333 MW of operational data center capacity and a 714 MW pipeline, supported by lower electricity tariffs of US$60/MWh compared with Malaysia (US$133/MWh) and Singapore (US$178/MWh).

>We maintain positive stance on the telco sector, supported by continued data consumption growth, connectivity demand from AI and cloud computing, and data center expansion opportunities.

>TLKM remains our preferred choice, supported by its network scale, fiber-optic infrastructure, and stronger data monetization capabilities. ISAT offers higher growth potential through AI Factory development, while EXCL (UR) provides exposure to potential post-consolidation synergies.

>Key risks include : slower data consumption growth, pressure on ARPU and data yield, and higher capital expenditure.

By PHINTRACO SEKURITAS | Research
— Disclaimer On —
Baca Laporan
Research

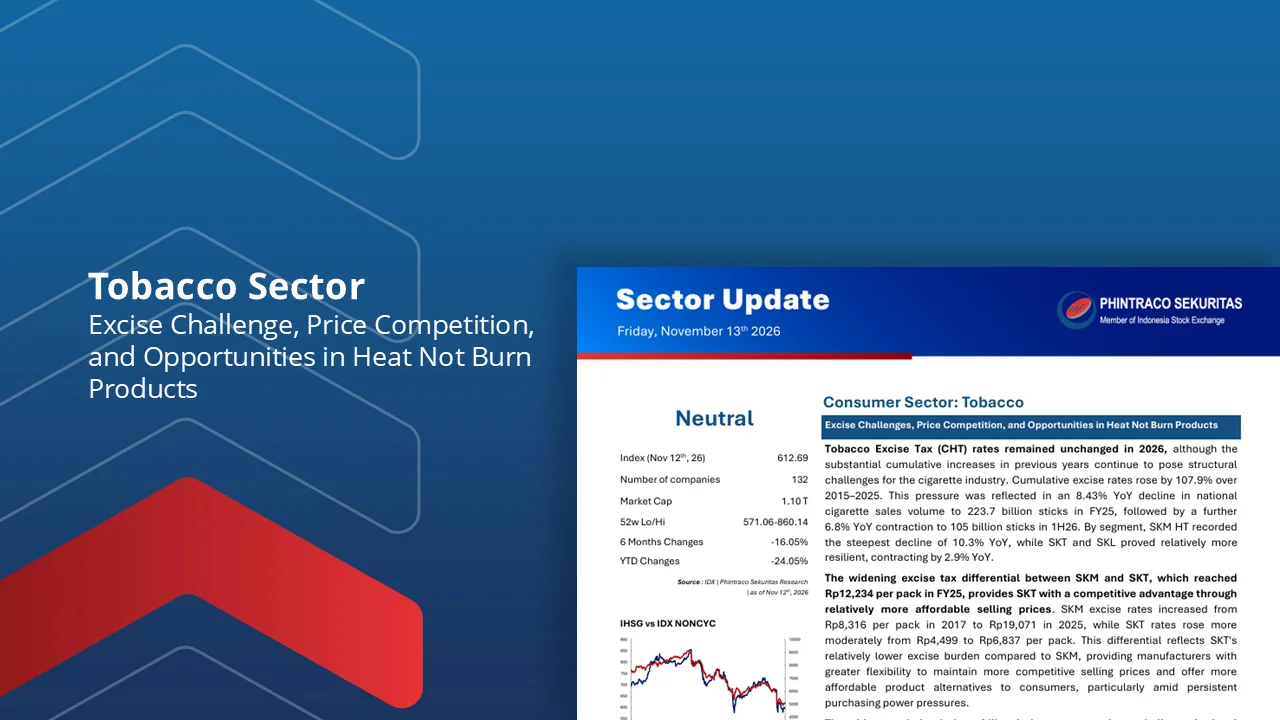
Tobacco Sector : Excise Challenge, Price Competition, and Opportunities in Heat Not Burn Products

13 Nov 2026 Sectoral Update

Rising Excise Burden Continues to Pressure Cigarette Sales. Despite unchanged excise rates in 2026, cumulative increases of 107.9% over 2015–2025 continue to weigh on the industry, with cigarette sales volume declining 6.8% YoY in 1H26.

Wider Excise Differential Supports SKT Competitiveness. The Rp12,234 per-pack excise gap between SKM and SKT in FY25 provides SKT with a pricing advantage, allowing manufacturers to offer more affordable products amid weakening purchasing power.

Illegal Cigarettes Remain a Key Industry Challenge. Despite intensified enforcement, illegal cigarette circulation continues to distort market competition. Seizures reached 1.2 billion sticks in 9M26 or increasing 44.4% YoY, with stronger enforcement potentially supporting legal manufacturers’ market share recovery.

Smoke-Free Products Offer New Growth Opportunities. HNB adoption and market expansion could become new industry growth drivers, supported by product innovation, wider distribution, and increasing consumer penetration, creating opportunities for revenue diversification.

Declining volumes, illegal cigarettes, and excise uncertainty remain key concerns. However, rerating potential could emerge from stable excise rates and stronger enforcement, with HMSP benefiting from SFP growth and WIIM from SKT prospects and solid fundamentals.

By PHINTRACO SEKURITAS | Research
-Disclaimer On –

Baca Laporan
Research

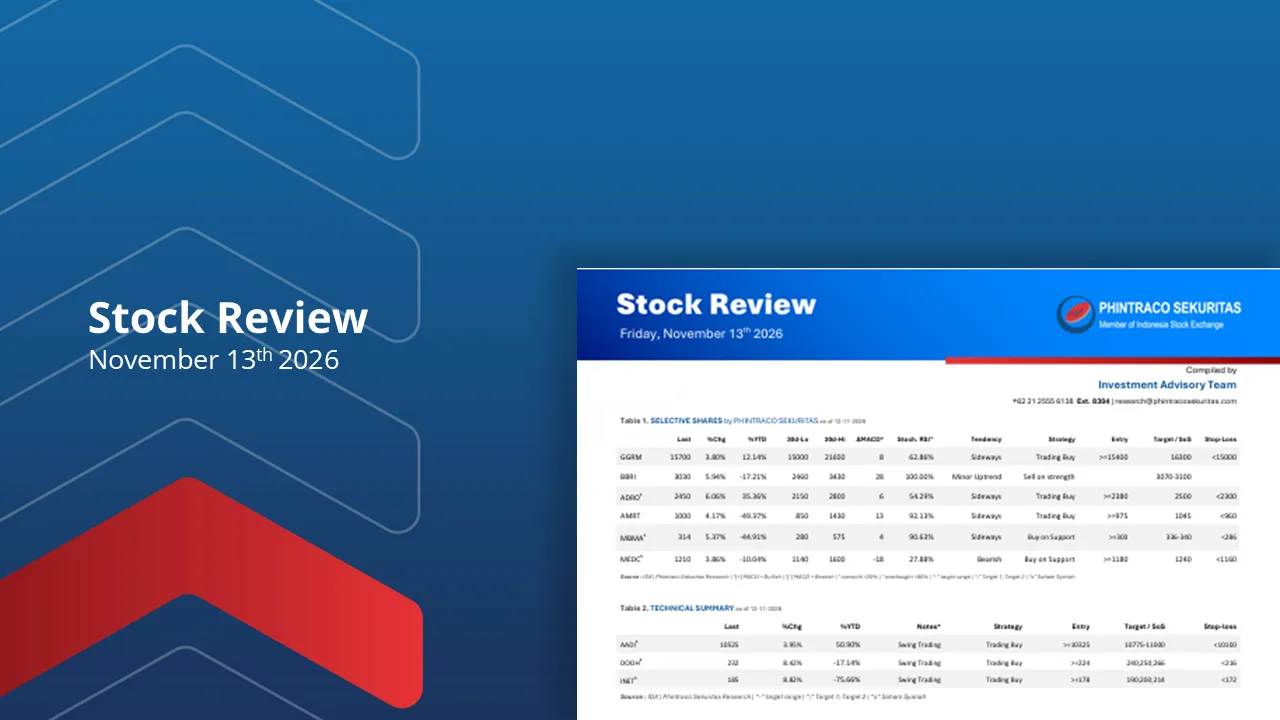
Today’s Selective Shares by Phintraco Sekuritas

13 Nov 2026 Technical Research

November 13th, 2026

Baca Laporan
Research

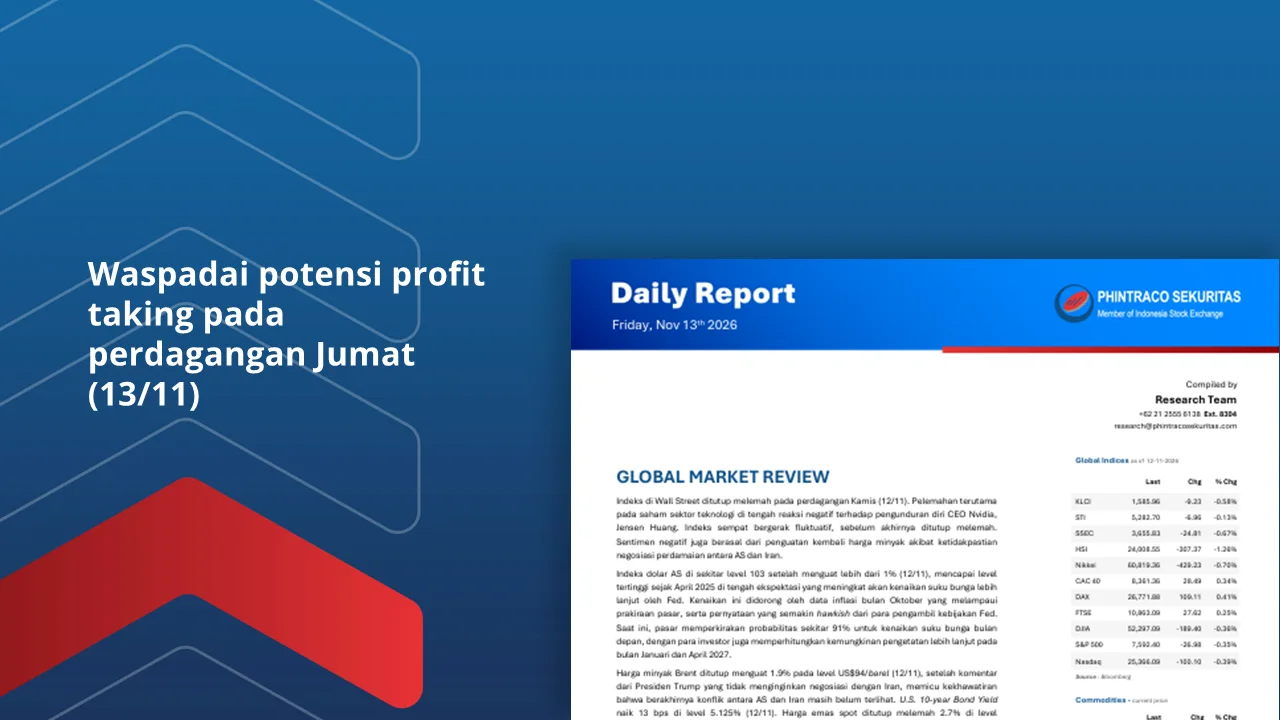
Waspadai potensi profit taking pada perdagangan Jumat (13/11)

13 Nov 2026 Daily Research

Indeks di bursa Wall Street ditutup melemah pada Kamis (12/11).

Pelemahan dipicu oleh saham sektor teknologi dan ketidakpastian negosiasi AS-Iran.

Indeks dolar AS di sekitar level 103 setelah menguat lebih dari 1% (12/11).

Probabilitas telah mencapai 91% untuk kenaikan suku bunga Fed pada bulan depan.

Harga minyak Brent ditutup menguat 1.9% pada level US$94/barel (12/11).

U.S. 10-year Bond Yield naik 13 bps di level 5.125% (12/11).

Harga emas spot ditutup melemah 2.7% di level US$3,881/troy oz (12/11).

Waspadai potensi profit taking di tengah penguatan dolar AS dan harga minyak, serta koreksi harga emas.

Jika IHSG bertahan di atas level 5,200, diperkirakan akan menguji level resistance berikutnya di 5,280-5,320.

Top picks (13/11): BBRI, TLKM, AMMN, ADRO, AMRT dan MBMA.

By PHINTRACO SEKURITAS | Research
– Disclaimer On –

Baca Laporan
Research

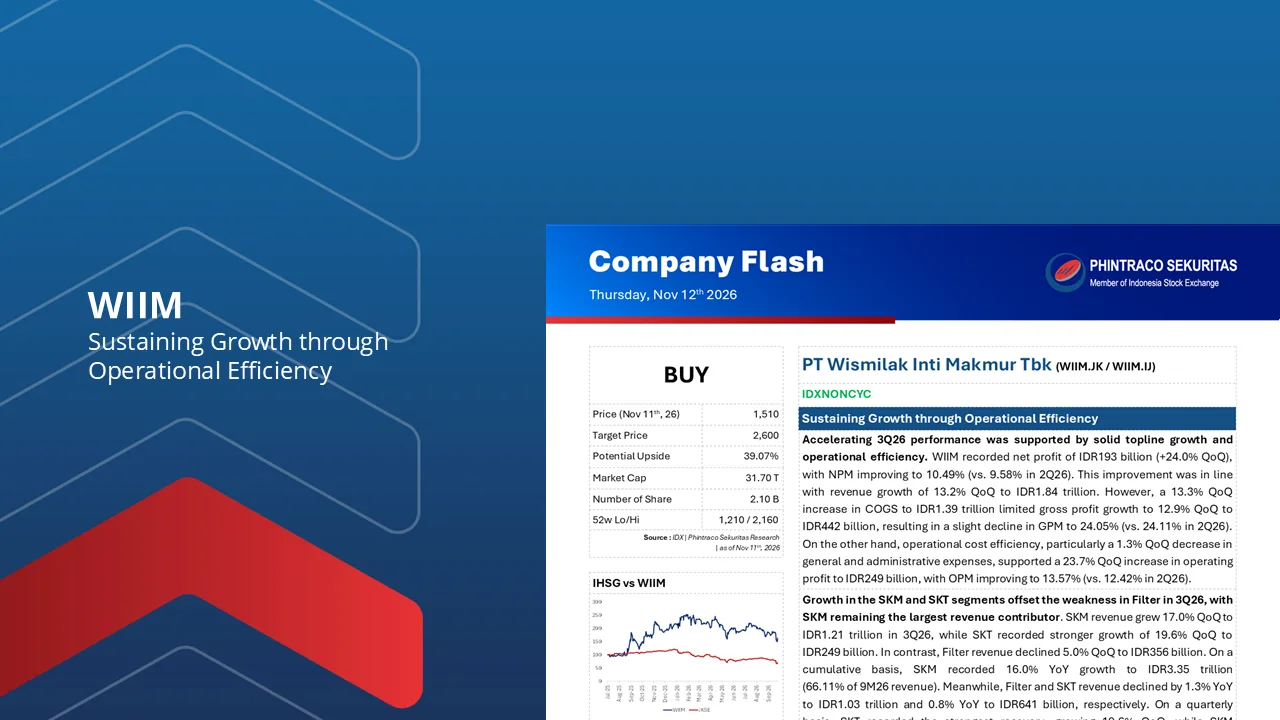
WIIM : Sustaining Growth through Operational Efficiency

12 Nov 2026 Company Flash

3Q26 performance accelerated, supported by solid revenue growth and operational efficiency. WIIM recorded net profit of IDR193 billion (+24.0% QoQ), with NPM improving to 10.49% (vs. 9.58% in 2Q26). Revenue grew 13.2% QoQ to IDR1.84 trillion. However, higher COGS (+13.3% QoQ) slightly pressured GPM to 24.05%. Meanwhile, lower operating expenses supported 23.7% QoQ growth in operating profit to IDR249 billion, with OPM improving to 13.57%.

SKM and SKT growth offset weaker Filter performance, while SKM remained the largest revenue contributor. SKM revenue grew 17.0% QoQ to IDR1.21 trillion, while SKT increased 19.6% QoQ to IDR249 billion. In contrast, Filter declined 5.0% QoQ to IDR356 billion. For 9M26, SKM grew 16.0% YoY to IDR3.35 trillion, contributing 66.11% of total revenue. Filter and SKT declined 1.3% and 0.8% YoY to IDR1.03 trillion and IDR641 billion, respectively.

Cost efficiency and regulatory stability could support sustainable growth. In 9M26, selling expenses declined 12.7% YoY to IDR361.4 billion, mainly due to lower promotion and advertising expenses (-24.0% YoY). This supported a 67.6% YoY increase in operating profit to IDR638 billion. Going forward, SKM and SKT growth could benefit from stable excise tax rates and stricter enforcement against illegal cigarettes, potentially improving the competitiveness of legal producers such as WIIM.

Key risks include excise tax increases, weaker purchasing power, cigarette market competition, and slower-than-expected SKT market share gains.

By PHINTRACO SEKURITAS | Research
— Disclaimer On —
Baca Laporan
Research

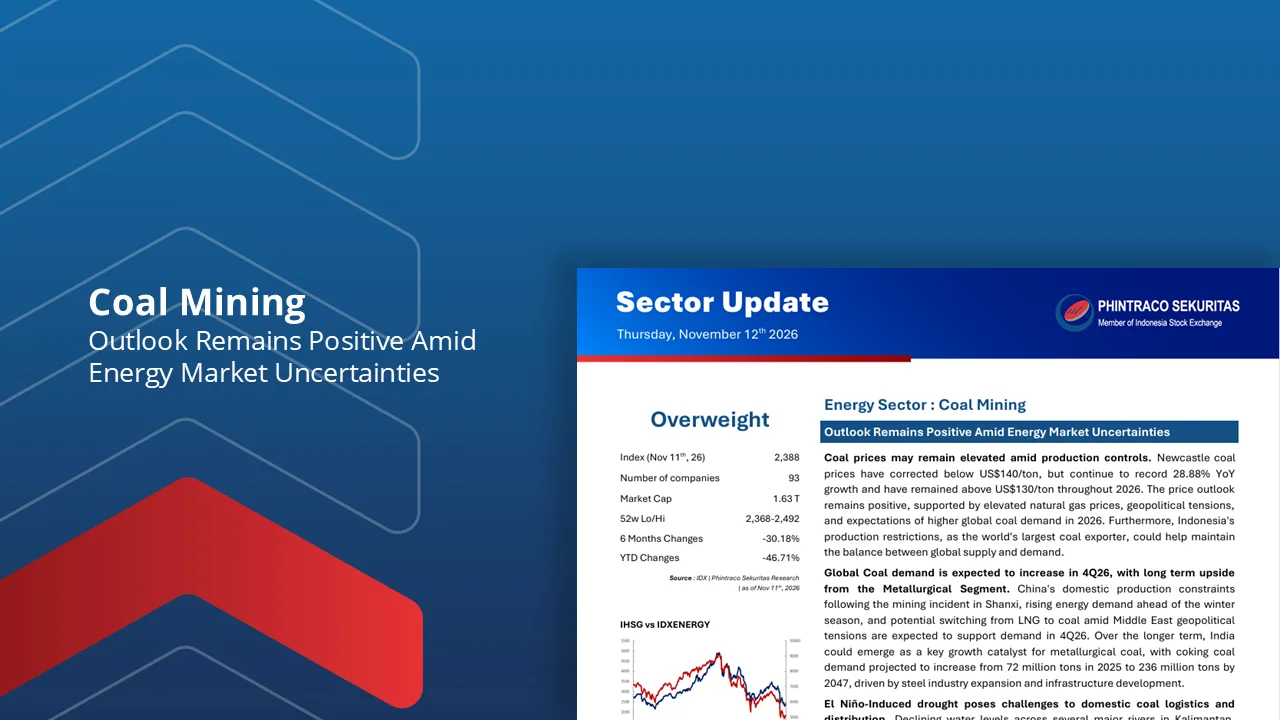
Coal Mining : Outlook Remains Positive Amid Energy Market Uncertainties

12 Nov 2026 Sectoral Update

Newcastle coal prices have corrected below US$140/ton but remain up 28.88% YoY and above US$130/ton throughout 2026. Prices are expected to remain relatively elevated, supported by geopolitical tensions, high natural gas prices, and Indonesia’s production controls, which could help tighten global supply.

China’s domestic supply constraints, seasonal demand, and potential fuel substitution amid elevated LNG prices are expected to support coal demand in 4Q26. Meanwhile, India’s coking coal demand is projected to more than triple from 72 million tons in 2025 to 236 million tons by 2047, driven by steel capacity expansion and infrastructure development.

Declining river levels across Kalimantan have reduced barge loading capacity to 3,000–6,000 tons from the normal 7,000–10,000 tons, resulting in stockpile accumulation, higher logistics costs, and 3.7–3.9 million tons of stranded coal monthly since July 2026, potentially weighing on export realization and domestic supply.

The government is implementing centralized coal exports through DSI starting January 2027, alongside tighter blending oversight, DMO adjustments, and DHE SDA requirements. Meanwhile, the 2027 RKAB evaluation remains ongoing, with 9M26 production reaching 514.98 million tons or 71.5% of the FY26 projection. Potential quota restrictions could support coal prices but increase operational and sales volume uncertainty.

ADMR supported by its metallurgical coal portfolio and aluminium diversification, while PTBA benefits from resilient domestic demand and downstream development initiatives. Key risks include regulatory uncertainty, prolonged drought, and elevated oil prices that could increase operating costs.

By PHINTRACO SEKURITAS | Research
-Disclaimer On

Baca Laporan
Research

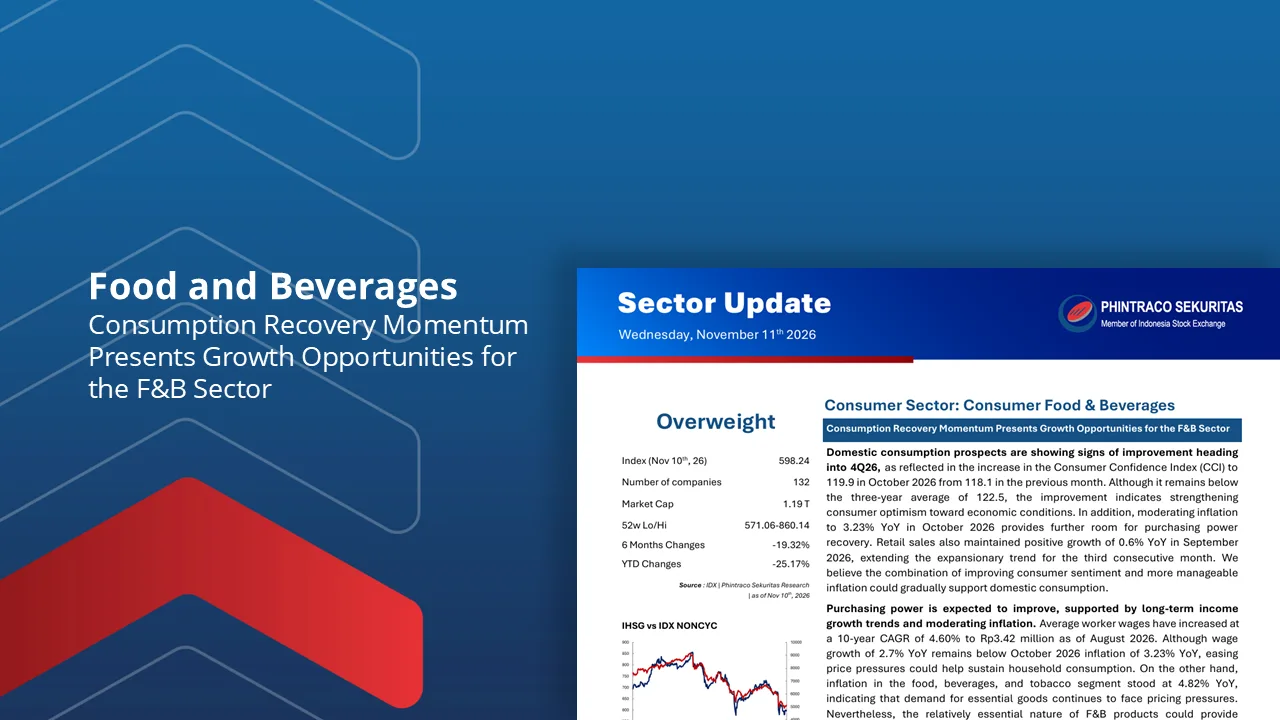
Food and Beverages Sector : Consumption Recovery Momentum Presents Growth Opportunities for the F&B Sector

12 Nov 2026 Sectoral Update

Domestic consumption shows gradual recovery heading into 4Q26. The CCI increased to 119.9 in October 2026, while inflation moderated to 3.23% YoY. Retail sales also maintained positive growth of 0.6% YoY in September, indicating improving consumer sentiment and gradual recovery in domestic consumption.

Average wages recorded a 10-year CAGR of 4.60% to Rp3.42 million as of August 2026, although wage growth of 2.7% YoY remained below inflation of 3.23%. Nevertheless, the essential nature of F&B products and affordable product offerings could help sustain demand.

Raw material and packaging costs remain key concerns, although easing commodity prices could support margin recovery. Declining cocoa prices provide some cost relief, while wheat, CPO, and plastic prices remain exposed to geopolitical and weather-related risks. A sustained decline in raw material prices could improve cost structures and profitability, particularly for issuers with strong operational efficiency.

Rupiah depreciation remains a key risk for issuers with high imported raw material exposure. The rupiah has weakened approximately 8% throughout 2026, breaching Rp18,000/US$. Hedging, supply diversification, and selective pricing adjustments could help mitigate cost pressures, while operational efficiency and product mix optimization remain essential to preserving margins.

MYOR’s solid performance is supported by cost efficiencies and foreign exchange gains, given its substantial export contribution. Key risks include weakening purchasing power, elevated raw material prices, and further rupiah depreciation.

By PHINTRACO SEKURITAS | Research
-Disclaimer On –

Baca Laporan
Research

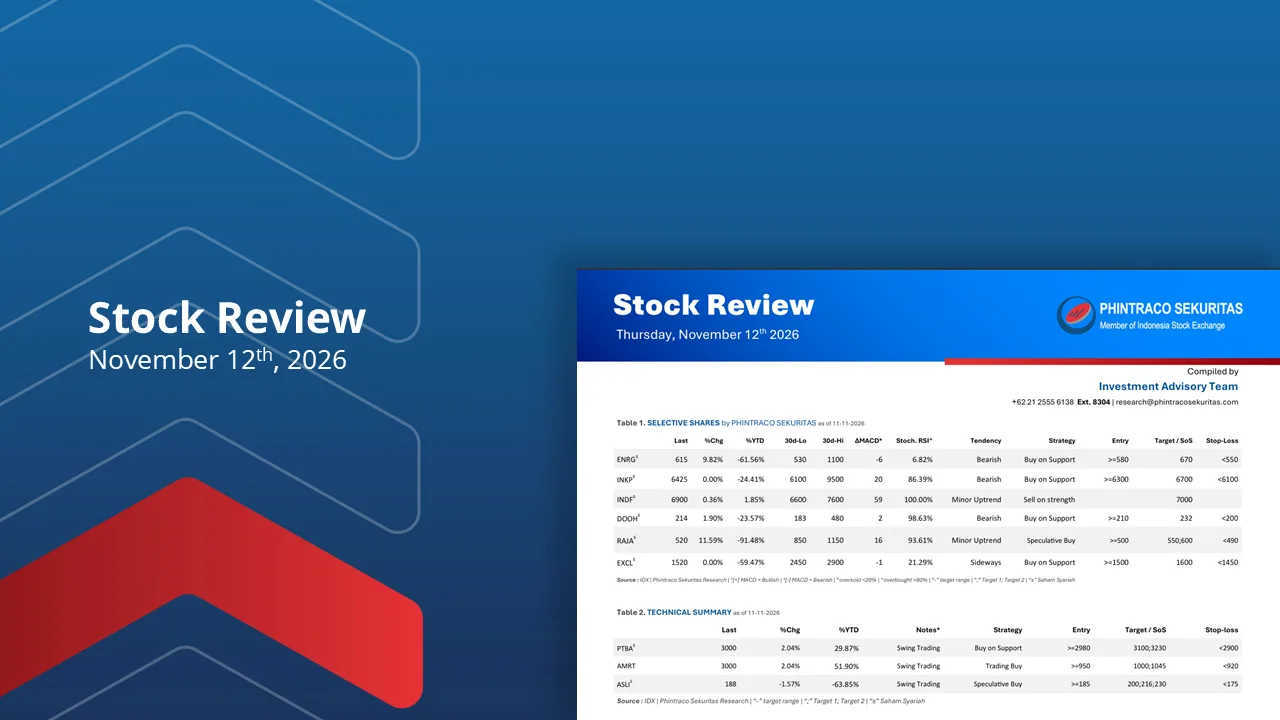
Today’s Selective Shares by Phintraco Sekuritas

12 Nov 2026 Technical Research

November 12th,26

Baca Laporan
Research

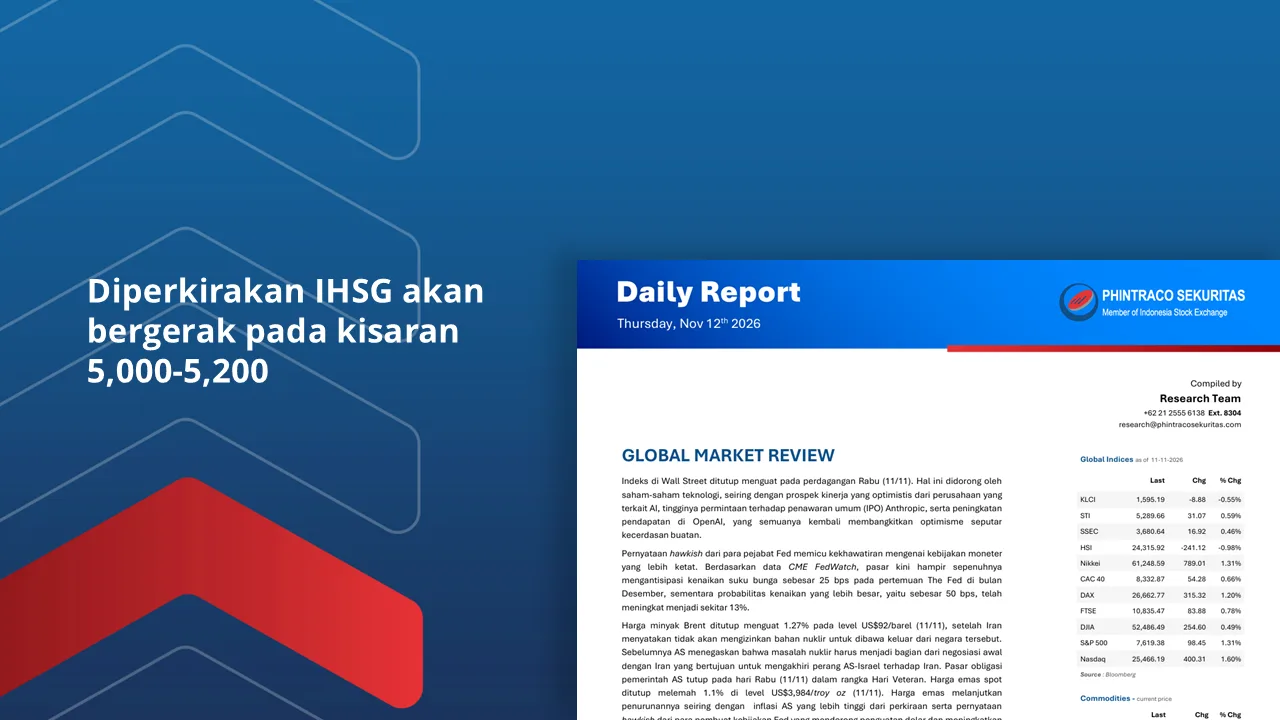
Diperkirakan IHSG akan bergerak pada kisaran 5,000-5,200

12 Nov 2026 Daily Research

Indeks di bursa Wall Street ditutup menguat pada Rabu (11/11).

Penguatan dipicu oleh saham sektor teknologi.

Pasar hampir sepenuhnya mengantisipasi kenaikan suku bunga sebesar 25 bps pada pertemuan The Fed di bulan Desember.

Harga minyak Brent ditutup menguat 1.27% pada level US$92/barel (11/11).

Pasar obligasi pemerintah AS tutup pada hari Rabu (11/11) dalam rangka Hari Veteran.

Harga emas spot ditutup melemah 1.1% di level US$3,984/troy oz (11/11).

Rebalancing indeks MSCI November mengeluarkan saham BRPT dari Global Standard dan menurunkan saham BRMS ke smallcap.

MSCI mengeluarkan saham AVIA, CTRA, MTEL, EMTK, JSMR, RAJA, WIFI dari indeks smallcap.

Diperkirakan IHSG akan bergerak pada kisaran 5,000-5,200.

Top picks (12/11): EXCL, ENRG, ASLI, INKP dan PTBA.

By PHINTRACO SEKURITAS | Research
– Disclaimer On –


Baca Laporan
Research

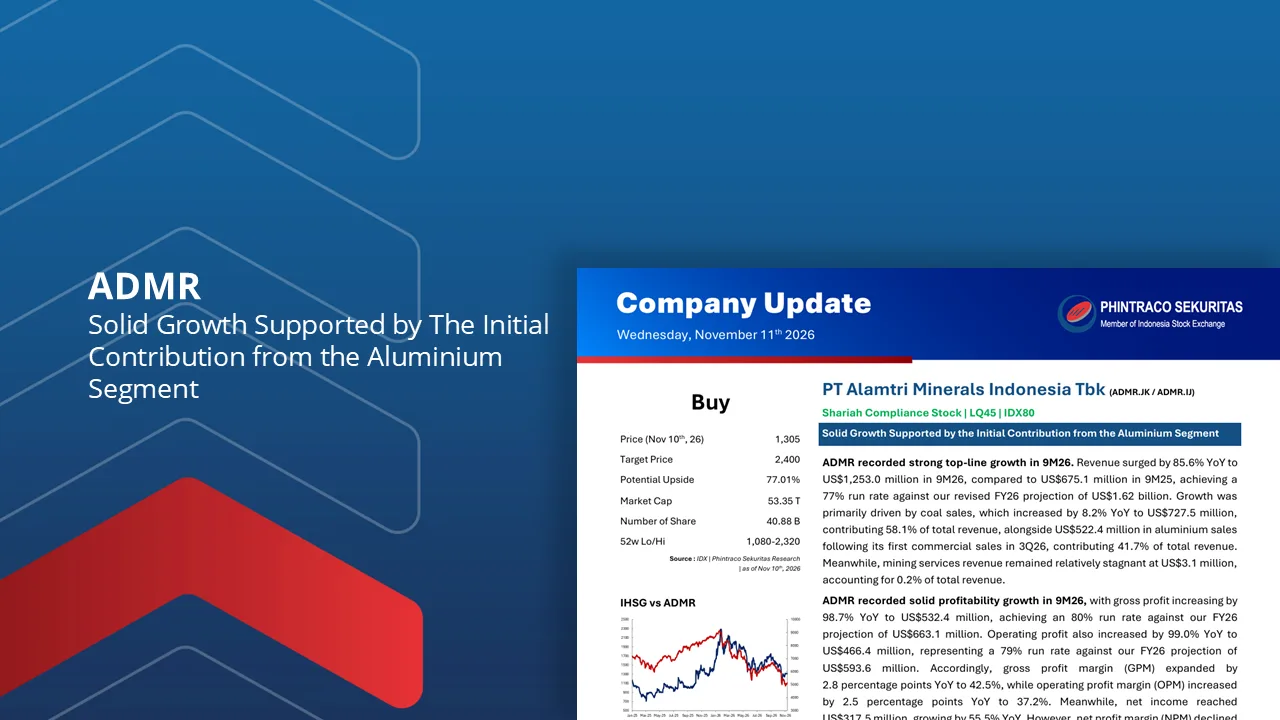
ADMR : Solid Growth Supported by the Initial Contribution from the Aluminium Segment

11 Nov 2026 Company Update

ADMR’s revenue surged by 85.6% YoY to US$1.25 billion in 9M26, achieving 77% of our revised FY26 projection. Growth was supported by coal sales of US$727.5 million (+8.2% YoY) and the initial contribution from aluminium sales of US$522.4 million following its first commercial sales in 3Q26. Aluminium now accounts for 41.7% of total revenue, marking an important milestone in ADMR’s business diversification.

Gross profit and operating profit increased by 98.7% and 99.0% YoY to US$532.4 million and US$466.4 million, respectively, supported by higher revenue contributions from aluminium. Accordingly, GPM and OPM expanded to 42.5% and 37.2%, while net income grew by 55.5% YoY to US$317.5 million. However, NPM declined to 25.3%, indicating that bottom-line growth remained relatively slower than operating profit expansion.

ADMR issued Rp2 trillion in bonds through PT Maruwai Coal, with approximately 92% of the proceeds allocated to capex, primarily for the construction of CHPP 2 in Murung Raya, Central Kalimantan. The project is expected to strengthen coal processing capabilities, support future production capacity, and improve operational efficiency, although the issuance will increase consolidated financial liabilities.

We revised our valuation and projection for FY26 onwards, supported by stronger revenue growth and the growing contribution from aluminium sales. Key risks include low river water levels in Kalimantan that could disrupt logistics, regulatory uncertainty surrounding coal exports, and a slowdown in global aluminium demand.

By PHINTRACO SEKURITAS | Research
-Disclaimer On –

Baca Laporan
Research

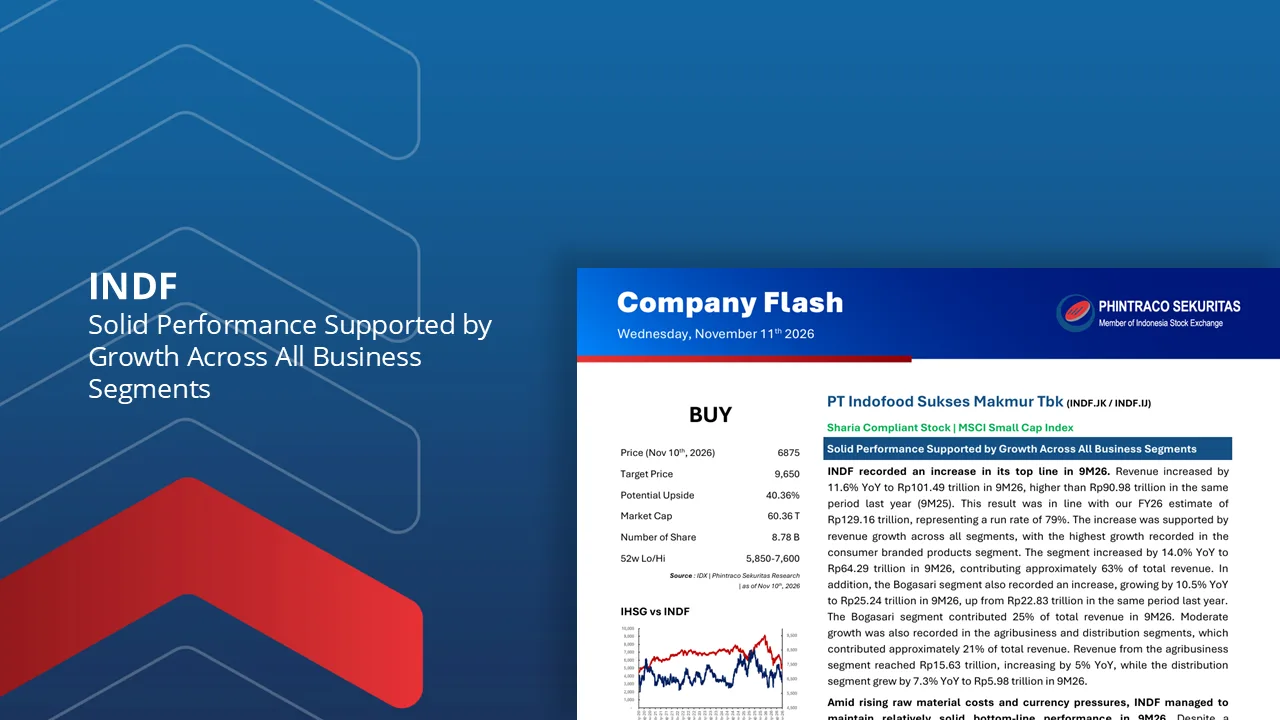
INDF : Solid Performance Supported by Growth Across All Business Segments

11 Nov 2026 Company Flash

Revenue Growth Supported by All Business Segments. INDF’s revenue increased by 11.6% YoY to Rp101.49 trillion in 9M26, achieving 79% of our FY26 estimate. Growth was primarily driven by the consumer branded products segment (+14.0% YoY), followed by Bogasari (+10.5% YoY), reflecting broad-based growth across its business segments.

Profitability Remained Resilient Amid Cost and Currency Pressures. Gross profit increased by 10.5% YoY to Rp33.43 trillion in 9M26, despite higher raw material costs, particularly CPO. Meanwhile, net income remained relatively stable at Rp7.87 trillion (-0.2% YoY), reflecting the group’s operational resilience amid higher production costs, Rupiah depreciation, and weaker contributions from associates and joint ventures.

Solid Operational Performance Across Segments. INDF recorded higher production volumes in its agribusiness segment, with FFB production increasing by 4% YoY to 2.01 million tons and CPO production growing by 13% YoY to 580 thousand tons in 9M26. The improvement was supported by a higher CPO extraction rate of 21.6%, reflecting stronger plantation productivity.

Key risks include weakening consumer purchasing power, rising raw material prices, and Rupiah depreciation against the US dollar.

By PHINTRACO SEKURITAS | Research
-Disclaimer On –

Baca Laporan
Research

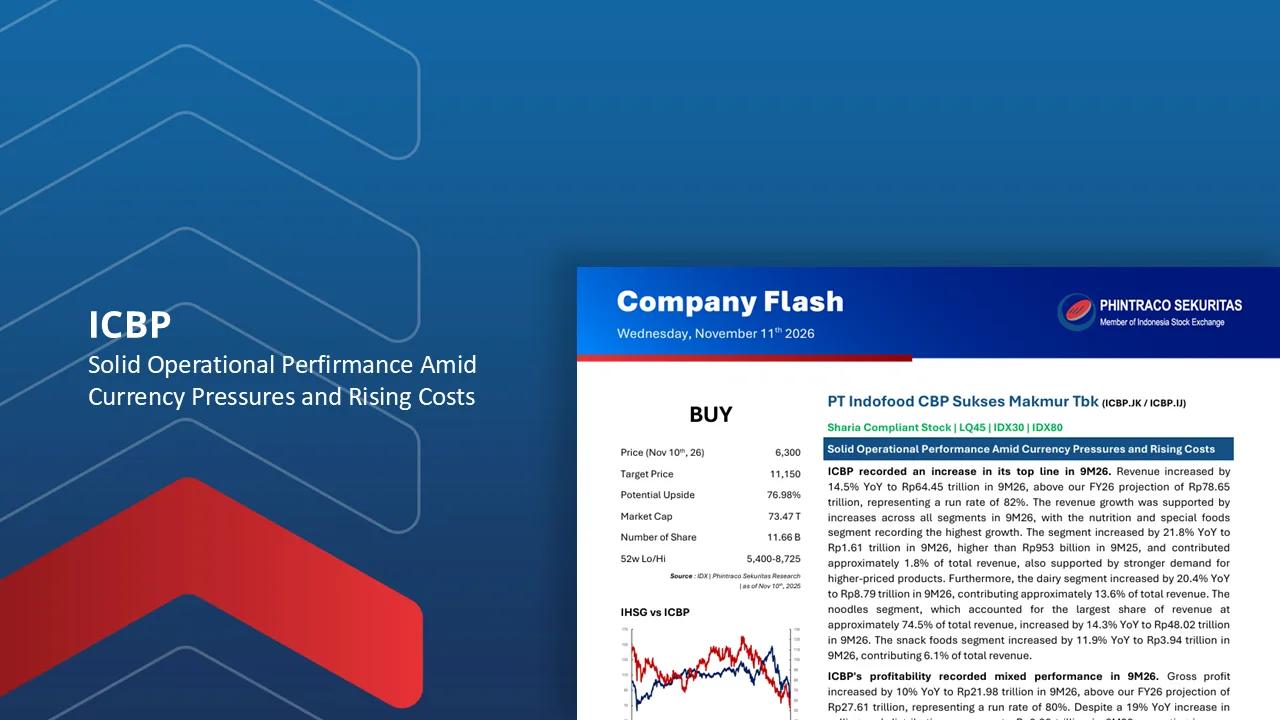
ICBP : Solid Operational Performance Amid Currency Pressures and Rising Costs

11 Nov 2026 Company Flash

Revenue Growth Remained Strong in 9M26. ICBP’s revenue increased by 14.5% YoY to Rp64.45 trillion in 9M26, achieving 82% of our FY26 projection. Growth was supported by all segments, particularly nutrition and special foods (+21.8% YoY), dairy (+20.4% YoY), and noodles (+14.3% YoY), reflecting stronger demand across its product portfolio, including higher-priced products.

Profitability Recorded Mixed Performance. Gross profit and operating income increased by 10% and 7% YoY to Rp21.98 trillion and Rp13.66 trillion, respectively, both achieving 80% of our FY26 projections. However, net income declined by 13% YoY to Rp6.16 trillion, mainly due to unrealized forex losses on global bonds amid Rupiah depreciation, alongside higher selling and distribution expenses.

Solid Operational Performance Amid Rising Costs. ICBP launched 38 new products throughout 2026, while sales volumes increased across all segments, led by dairy, followed by food seasonings and nutrition and special foods. Nevertheless, higher raw material and packaging costs continued to weigh on profitability, although solid volume growth reflected resilient demand and strong brand competitiveness.

Key risks include Rupiah depreciation against the US dollar, weakening consumer purchasing power, and rising raw material prices.

By PHINTRACO SEKURITAS | Research
-Disclaimer On

Baca Laporan
Research

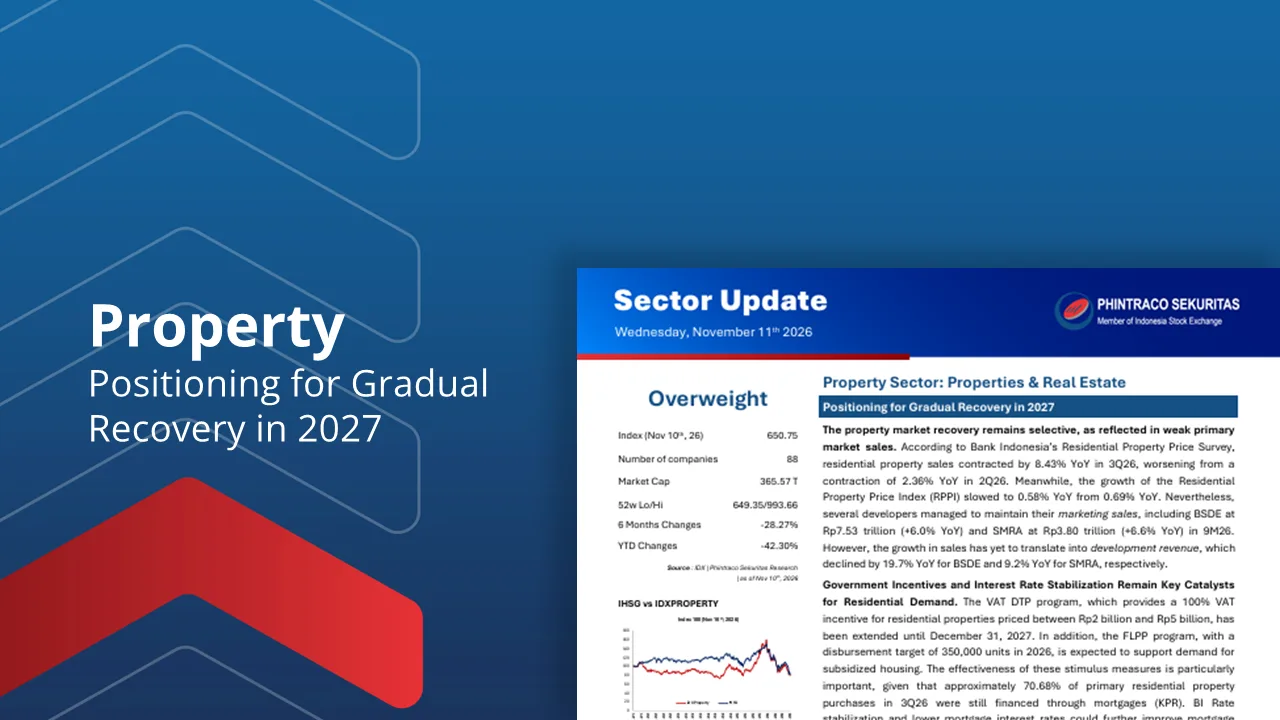
Property Sector: Positioning for Gradual Recovery in 2027

11 Nov 2026 Sectoral Update

Property Sector Outlook Remains Positive for 2027. The sector is expected to benefit from potential interest rate cuts, housing incentives, and improving purchasing power, although the recovery may remain gradual and uneven across segments.

Marketing Sales Provide Foundation for Future Revenue Growth. Several developers recorded solid presales performance in 9M26, providing a potential revenue pipeline for 2027. However, conversion into recognized revenue remains dependent on construction progress and unit handovers.

Recurring Income Supports Earnings Resilience. Recurring revenue continued to grow across major developers, supported by shopping malls, hotels, and other investment properties. This provides a more stable earnings base amid slower development revenue.

Profitability and Balance Sheet Strength Remain Key Differentiators. Differences in margins, return on equity, and leverage highlight the importance of selective exposure to developers with stronger earnings quality and financial flexibility.

Valuation Upside Remains Selective. Property stocks continue to trade at relatively attractive valuations, with varying NAV discounts across developers. The potential for re-rating will depend on stronger marketing sales, improved revenue recognition, and sustained recovery in profitability.

By PHINTRACO SEKURITAS | Research
– Disclaimer On –

Baca Laporan

Berita

Berita

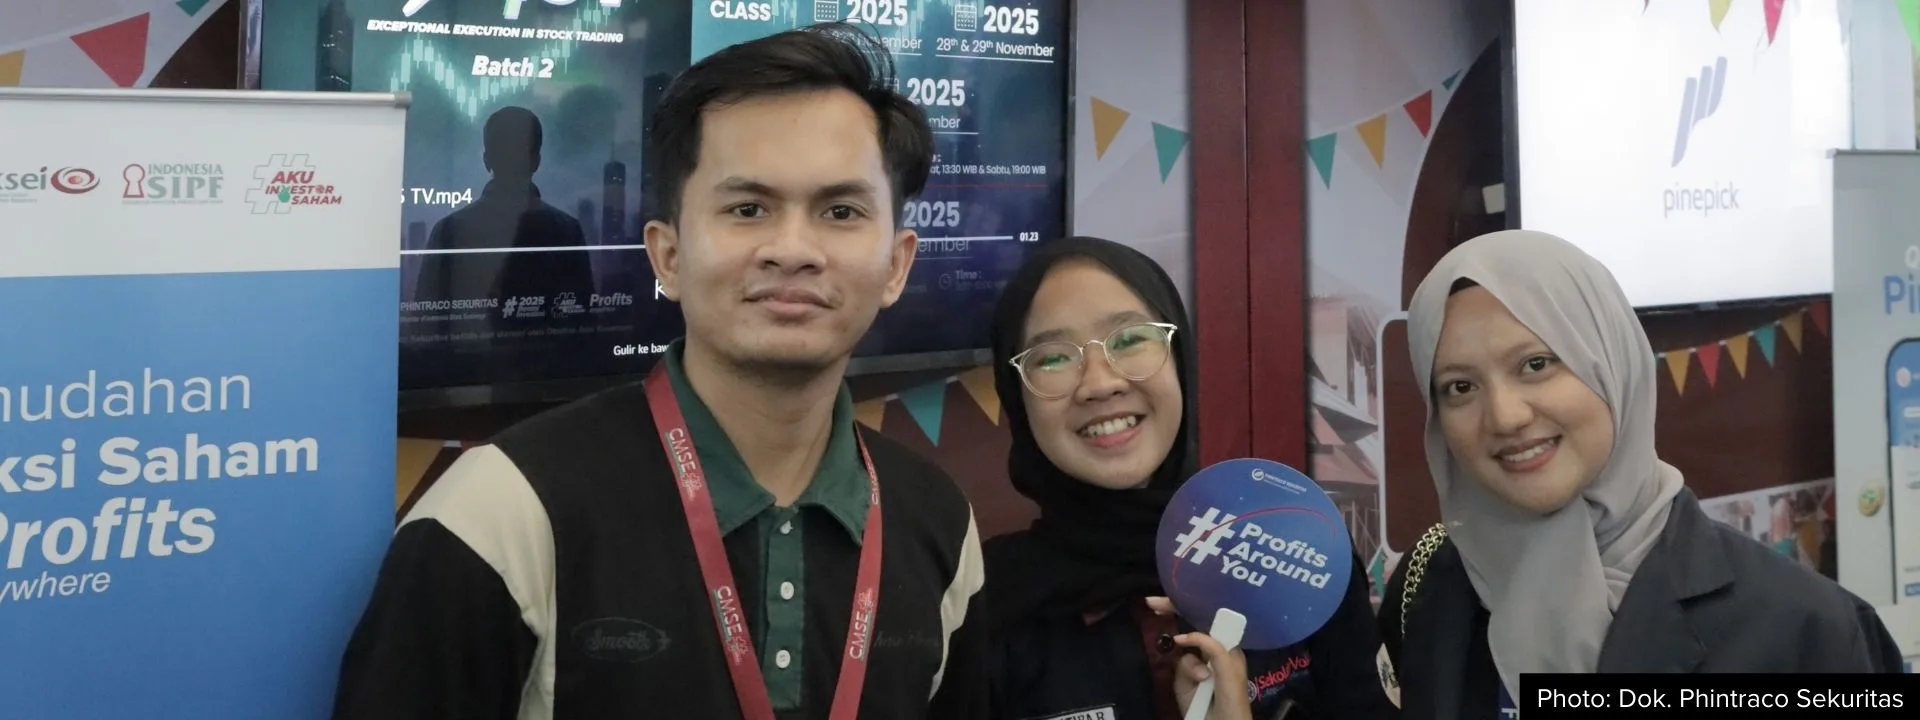
Investasi bareng Phintraco Sekuritas di CMSE 2025

12 Dec 2025 Berita

Phintraco Sekuritas kembali hadir di Capital Market Summit & Expo (CMSE) yang diselenggarakan pada 17–18 Oktober 2025 di Main Hall Bursa Efek Indonesia.

Sumber: Dokumentasi Perusahaan Phintraco Sekuritas

CMSE digelar oleh Bursa Efek Indonesia (BEI) bersama dengan Self-Regulatory Organization (SRO), yakni PT Kliring Penjaminan Efek Indonesia (KPEI) dan PT Kustodian Sentral Efek Indonesia (KSEI). Pada CMSE, berisi serangkaian kegiatan seperti pameran, talk show dan aktivitas interaktif seputar edukasi pasar modal Indonesia melalui berbagai kegiatan yang terbagi dalam berbagai sesi.

Di CMSE 2025, tema yang diusung ialah “Pasar Modal untuk Rakyat: Satu Pasar, Berjuta Peluang.” Tema tersebut merupakan suatu ungkapan yang menggambarkan upaya dalam membuka pandangan masyarakat mengenai mudahnya berinvestasi dan mengenal pasar modal. Selain itu, sebagai bagian dari kampanye yang telah lama dijalankan BEI, tagar #AkuInvestorSaham diharapkan dapat terus memberikan dampak positif melalui aktivitas pendidikan mengenai literasi pasar modal yang mampu menarik perhatian untuk mengenalkan cara mulai investasi saham.

Di tahun ini, CMSE 2025 dimeriahkan dengan kehadiran sekitar 95 tenant dari para pelaku pasar maupun industri, serta UMKM yang ada di seluruh Indonesia. Kali ini Phintraco Sekuritas kembali hadir dengan menawarkan pengalaman berinvestasi yang dekat, menyenangkan, dan mudah dipahami oleh masyarakat. Setiap tahunnya, Phintraco Sekuritas selalu berusaha memberikan inovasi dan pengalaman baru bagi nasabah dan calon nasabah. Di tahun 2025, kegiatan ini berlangsung selama dua hari terhitung dari tanggal 17-18 Oktober di Main Hall Bursa Efek Indonesia. 

Pada kesempatan tahun ini, para pengunjung booth Phintraco Sekuritas bisa mendapatkan berbagai doorprize menarik hanya dengan membuka akun baru melalui PROFITS Anywhere. Nantinya, nasabah yang baru memiliki akun akan berkesempatan memainkan games berupa Mini Golf. Selain mini games yang ditawarkan, pengunjung booth Phintraco Sekuritas juga dapat menerima hadiah langsung berupa makanan ringan hingga kipas. Nasabah yang memainkan games tersebut bisa mendapatkan hadiah menarik seperti beragam tumbler dan pulpen eksklusif dari Phintraco Sekuritas sebagai bagian dari upaya investasi saham untuk pemula agar terasa menyenangkan. 

Menyenangkan bukan, Sahabat Profits?

Tunggu kehadiran Phintraco Sekuritas di CMSE 2026 selanjutnya ya untuk mendapatkan keseruan serta hadiah menarik lainnya! Selain itu, yuk ikuti media sosial kami di @phintracosekuritasofficial supaya Anda tidak ketinggalan informasi menarik lainnya.


Penulis: Salsabila Wardhani

Editor: Yundira Putri Rahmadianti

Baca Laporan
Berita

Experience the Excitement of Saham Investment Week (SIW) 2025 with Phintraco Sekuritas

20 Nov 2025 Berita

On June 19-21, 2025, Phintraco Sekuritas continued to participate in the Sharia Investment Week (SIW) event held by the Indonesia Stock Exchange (IDX).


The IDX, along with the Indonesian Clearing House of Guarantors (KPEI) and the Indonesian Central Depository and Settlement Institution (KSEI), supported by the Financial Services Authority (OJK), regularly organizes SIW to help the Indonesian people learn more about the Sharia Capital Market. Annually, SIW is attended by members of the Sharia Online Trading System (AB SOTS), with Phintraco Sekuritas being one of them.

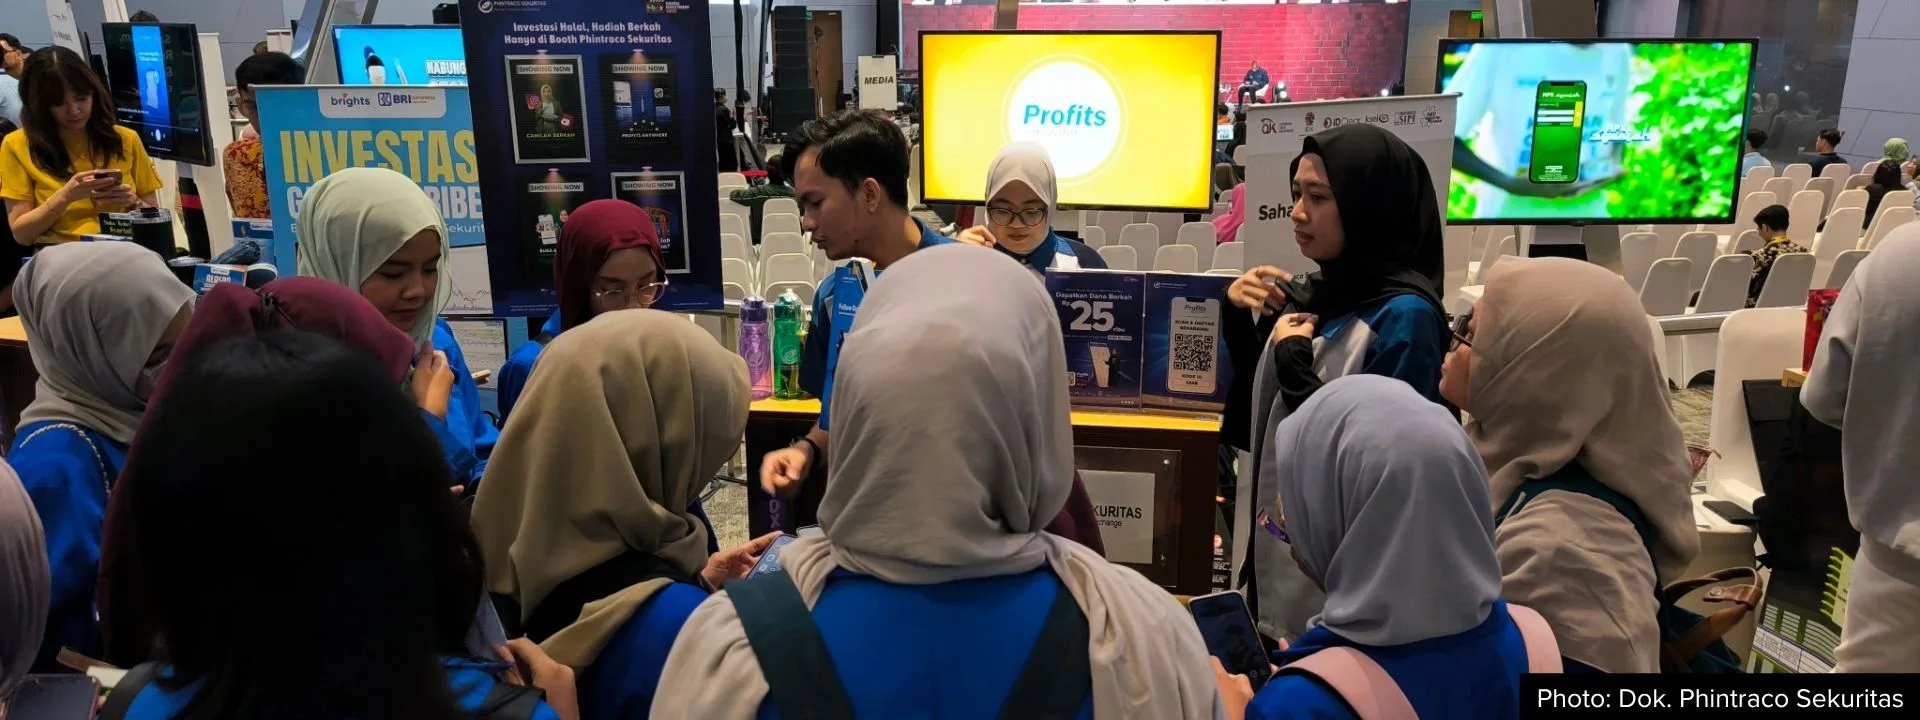
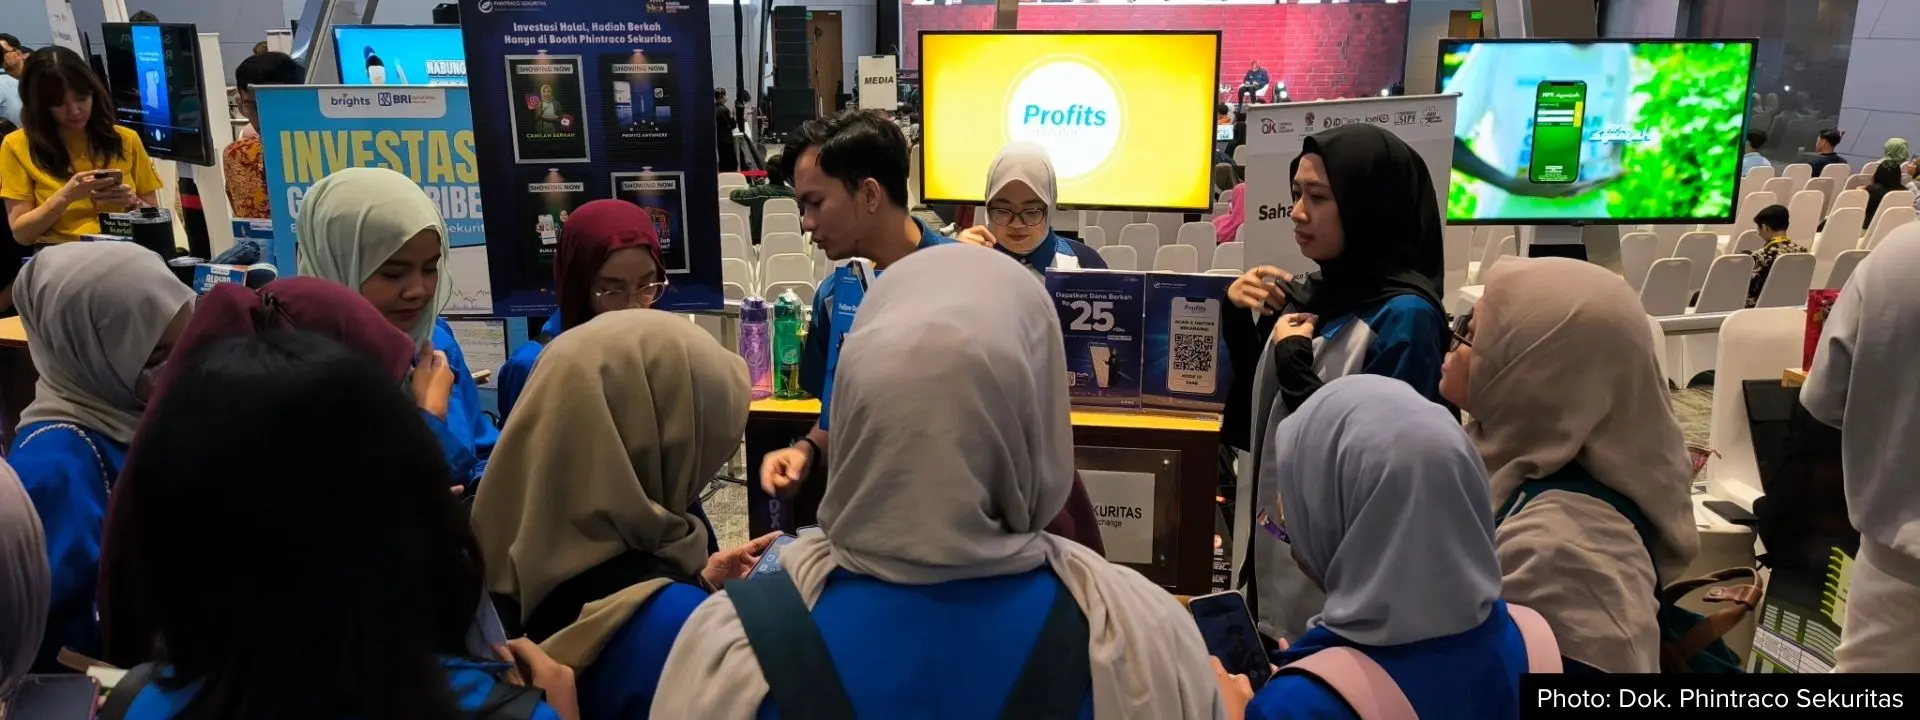
During the 3-day SIW 2025 event, customers and prospective customers can attend in person at the IDX Main Hall or online via the SIW website at https://siw.idx.co.id/. The high enthusiasm of customers and prospective customers has made the Phintraco Sekuritas booth at SIW 2025 always crowded with visitors seeking information about sharia investment, both offline and online. Prospective customers who open an account at Phintraco Sekuritas will receive a free RDN worth IDR 25,000 exclusively during SIW 2025.

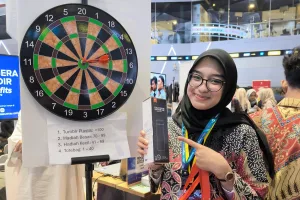
Then, after the new customer opens a sharia account, they will be entitled to participate in a dart game with various attractive prizes. If they win a certain score, customers can get attractive snacks, prayer mats, and even exclusive tumblers. Therefore, the presence of Phintraco Sekuritas at SIW 2025 is always eagerly awaited by customers and prospective customers.

Source: Company Documentation

However, even though SIW 2025 has ended, Phintraco Sekuritas is ready to participate in the next SIW with a variety of exciting activities and the newest information. Stay tuned for SIW 2026 on the IDX or Phintraco Sekuritas social media accounts at @phintracosekuritasofficial.


Writer: Yundira Putri Rahmadianti

Editor: Salsabila Wardhani

Baca Laporan
Berita

Intip Keseruan SIW 2025 bersama Phintraco Sekuritas

09 Oct 2025 Berita

Tanggal 19 hingga 21 Juni 2025 lalu, Phintraco Sekuritas kembali mengikuti event Sharia Investment Week (SIW) yang diadakan oleh Bursa Efek Indonesia (BEI).

Diselenggarakan secara rutin oleh BEI yang bekerja sama bersama Kliring Penjamin Efek Indonesia (KPEI) dan Kustodian Sentral Efek Indonesia (KSEI) dengan dukungan Otoritas Jasa Keuangan (OJK), SIW bertujuan untuk meningkatkan literasi Pasar Modal Syariah masyarakat Indonesia menjadi lebih luas. Sehingga setiap tahunnya SIW dihadiri oleh Anggota Bursa Sharia Online Trading System (AB SOTS) dan Phintraco Sekuritas merupakan salah satunya.

Di SIW 2025 yang berlangsung selama 3 hari ini, nasabah dan calon nasabah dapat hadir secara luring ke Main Hall BEI ataupun secara daring melalui website SIW di laman https://siw.idx.co.id/. Tingginya antusiasme dari nasabah dan calon nasabah membuat booth Phintraco Sekuritas di SIW 2025 selalu ramai dikunjungi untuk mendapatkan informasi seputar investasi syariah baik secara luring dan daring, calon nasabah yang melakukan pembukaan akun di Phintraco Sekuritas akan mendapatkan hadiah RDN senilai Rp25.000 secara gratis khusus selama SIW 2025 berlangsung.

Sumber: Dokumentasi Perusahaan

Kemudian setelah nasabah baru melakukan pembukaan akun syariah, maka akan  berhak mengikuti permainan dart dengan beragam hadiah menarik. Jika memenangkan skor tertentu, nasabah bisa mendapatkan camilan menarik, sajadah, hingga tumbler eksklusif. Sehingga kehadiran Phintraco Sekuritas di SIW 2025 selalu ditunggu setiap harinya oleh nasabah dan calon nasabah.

Meski SIW 2025 telah berakhir, namun Phintraco Sekuritas siap untuk hadir di SIW selanjutnya dengan beragam keseruan dan informasi terbaru lainnya. Nantikan SIW 2026 di sosial media BEI atau Phintraco Sekuritas di @phintracosekuritasofficial.


Penulis: Yundira Putri Rahmadianti

Editor: Dhira Parama Yuga

Baca Laporan
Download Download Download Download