Daily Research
Read More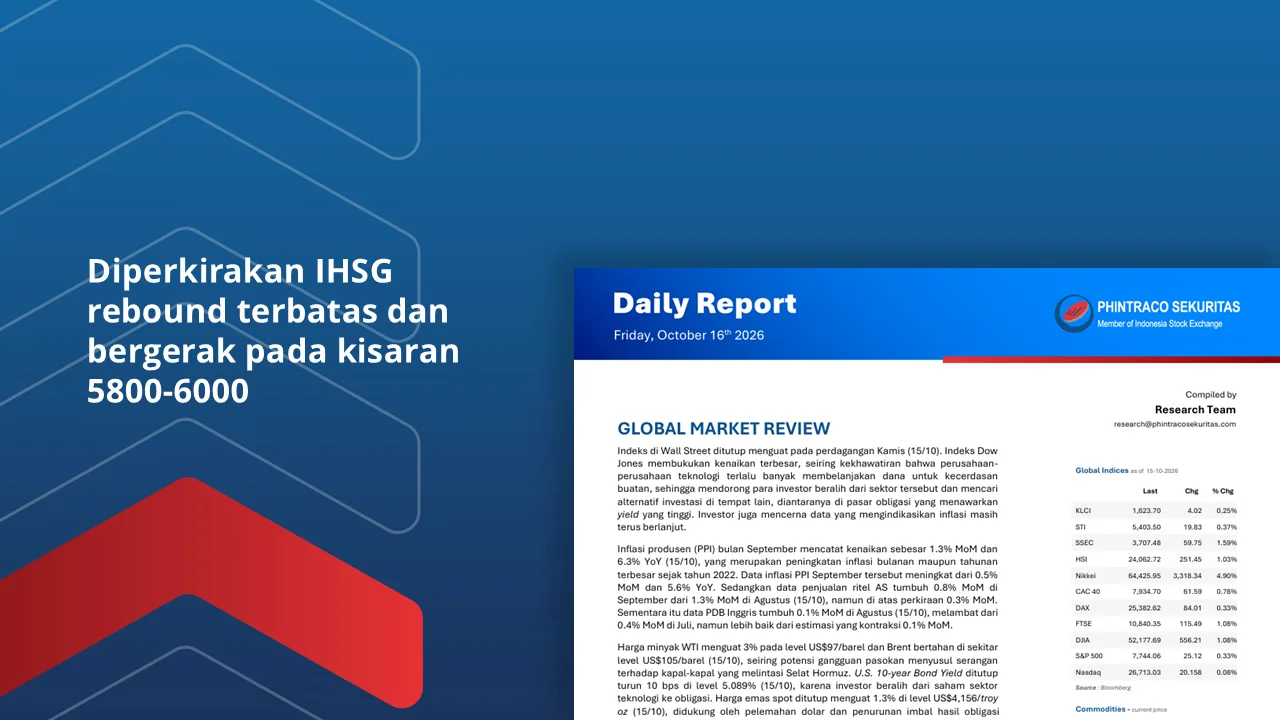
Diperkirakan IHSG rebound terbatas dan bergerak pada kisaran 5800-6000

Indeks di Wall Street ditutup menguat pada Kamis (15/10).
Indeks Dow Jones menguat karena investor beralih dari saham sektor teknologi.
Inflasi PPI September mencatat kenaikan sebesar 1.3% MoM dan 6.3% YoY (15/10).
Penjualan ritel AS tumbuh 0.8% MoM di September (15/10).
PDB Inggris tumbuh 0.1% MoM di Agustus (15/10).
Utang Luar Negeri (ULN) Indonesia naik menjadi US$459.3 miliar pada Agustus 2026, tumbuh 5.6% YoY (15/10).
Harga minyak WTI menguat 3% pada level US$97/barel (15/10).
U.S. 10-year Bond Yield ditutup turun 10 bps di level 5.089% (15/10).
Harga emas spot ditutup menguat 1.3% di level US$4,156/troy oz (15/10).
IHSG berpotensi rebound terbatas dan bergerak pada kisaran 5,800-6,000.
Top picks (16/10): INTP, ASII, UNTR, BBNI, BMRI dan BBRI.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
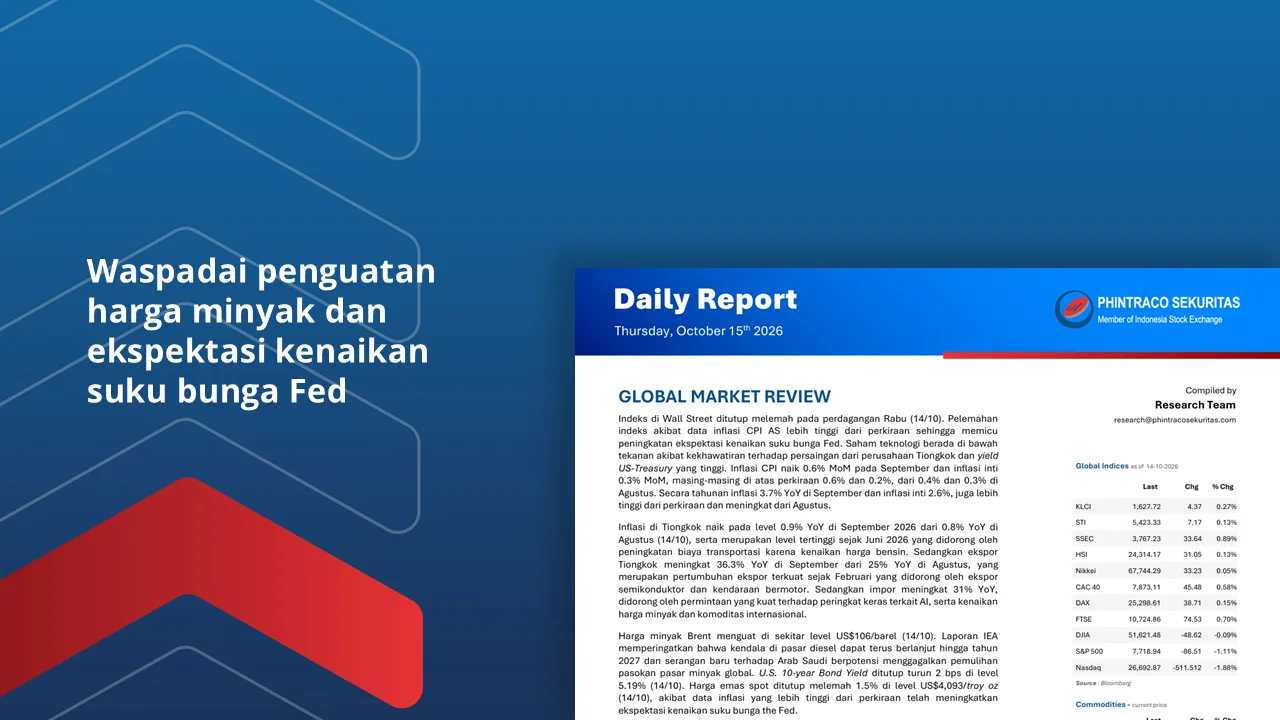
Waspadai penguatan harga minyak dan ekspektasi kenaikan suku bunga Fed
Indeks di Wall Street ditutup melemah pada Rabu (14/10).
Pelemahan indeks akibat data inflasi dan tekanan pada saham teknologi.
Data inflasi yang lebih tinggi dari perkiraan meningkatkan ekspektasi kenaikan suku bunga.
Inflasi CPI AS meningkat menjadi 0.6% MoM dan 3.7% YoY di September (14/10).
Inflasi di Tiongkok naik pada level 0.9% YoY di September 2026 (14/10).
Ekspor Tiongkok meningkat 36.3% YoY di September (14/10).
Harga minyak Brent menguat di level US$106/barel (14/10).
U.S. 10-year Bond Yield ditutup turun 2 bps di level 5.19% (14/10).
Harga emas spot ditutup melemah 1.5% di level US$4,093/troy oz (14/10).
Diperkirakan IHSG bergerak sideways pada kisaran 5,800-6,000.
Top picks (15/10): BRPT, PANI, UNTR, ISAT, BDMN dan MAPI.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Diperkirakan IHSG sideways pada kisaran 5,800-6,000
Indeks di Wall Street ditutup melemah terbatas pada Selasa (13/10).
Investor mencerna earning season bank-bank besar, serta saham-saham produsen memory tertekan.
Rata-rata laba emiten dalam indeks S&P 500 diperkirakan tumbuh hampir 30% YoY.
Inflasi CPI AS diperkirakan berakselerasi menjadi 0.6% MoM dan 3.7% YoY di September (14/10).
Inflasi Tiongkok diperkirakan naik di level 1% YoY pada September 2026 (14/10).
Ekspor Tiongkok diperkirakan tumbuh 25.5% YoY dan impor 24.5% pada September (14/10).
Harga minyak Brent ditutup melemah terbatas di level US$105/barel (13/10).
U.S. 10-year Bond Yield ditutup melemah lebih dari 2 bps di level 5.215 (13/10).
Harga emas spot ditutup melemah 0.4% di level US$4,154/troy oz (13/10).
Diperkirakan IHSG bergerak sideways pada kisaran 5,800-6,000, selama di bawah level 6,000.
Top picks (14/10): BBCA, AMMN, ASII, TINS, BBNI dan EMAS.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Technical Research
Read More
Weekly Research
Read More
Investor cermati sentimen eksternal dan domestik pekan ini
Indeks di bursa Wall Street ditutup menguat pada Jumat (9/10).
Penguatan dipicu oleh saham sektor teknologi dan koreksi tipis harga minyak.
Serangan Houthi terhadap bandara Arab Saudi diperkirakan meningkatkan ketegangan.
Pertemuan tahunan IMF dan Bank Dunia di Bangkok (12-18/10).
IMF akan rilis World Economic Outlook terbaru pada Selasa (13/10).
BEI dan KSEI lengkapi data kepemilikan saham untuk investor lokal dan asing.
BEI akan memperluas cakupan saham HSC untuk kapitalisasi pasar di atas Rp5 triliun.
Waspadai dampak naiknya harga minyak dan perluasan saham HSC.
Diperkirakan IHSG bergerak pada kisaran 6,000-6,215 pekan ini.
Top picks pekan ini: ASII, TLKM, AMMN, BBRI dan DSSA.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Diperkirakan IHSG sideways pada kisaran 6,000-6,200 pekan ini
Indeks di bursa Wall Street ditutup menguat pada Jumat (2/10).
Penguatan dipicu oleh data nonfarm payrolls yang lebih rendah dari perkiraan.
Nonfarm payrolls tercatat 29 ribu di September, melambat dari 133 ribu di Agustus.
Tingkat pengangguran AS naik menjadi 4.2% dari 4.1% (2/10).
G7 akan melepas 100 juta barel cadangan minyak selama 4 bulan ke depan.
Dari AS, akan dirilis FOMC minutes, data ISM Service PMI, serta data awal Michigan Consumer Sentiment.
Dari domestik akan dirilis cadangan devisa (7/10), indeks keyakinan konsumen (8/10), serta retail sales dan penjualan otomotif (9/10).
Diperkirakan IHSG sideways cenderung menguat pada kisaran 6,000-6,200 pekan ini.
Top picks pekan ini: ASII, BRMS, BBCA, BRPT dan MDKA.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
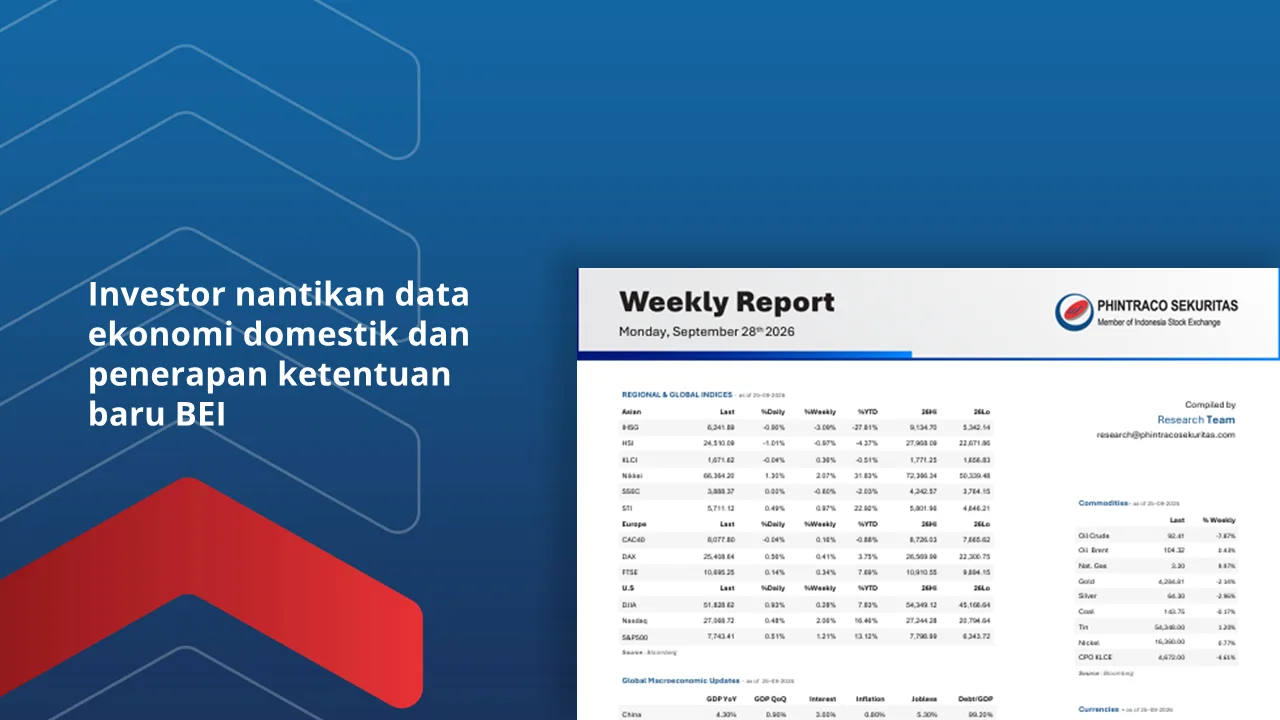
Investor nantikan data ekonomi domestik dan penerapan ketentuan baru BEI
Indeks di bursa Wall Street ditutup menguat pada Jumat (25/9).
Penguatan indeks didukung oleh kenaikan saham sektor teknologi dan koreksi harga minyak.
Iran mengusulkan AS kembali pada nota kesepahaman bulan Juni.
AS dan Tiongkok memperpanjang gencatan senjata perang dagang hingga 10 Januari.
Investor akan menantikan data indeks Manufacturing PMI, neraca perdagangan dan inflasi yang akan dirilis pada Kamis (1/10).
Batas minimum harga saham di pasar reguler dan pasar tunai dari Rp50 menjadi Rp1 per saham mulai 28 September 2026.
BEI hapus 4 kriteria FCA, sehingga 92 saham FCA dikembalikan ke pasar pencatatan semula.
ARB simetris ditetapkan mulai berlaku pada 1 Januari 2027.
Diperkirakan IHSG masih berpotensi uji level 6,186-6,200 pada pekan ini.
Top picks pekan ini: ADRO, ITMG, AADI, BBRI dan BBCA.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Fixed Income Research
Read More
Daily Fixed Income Report – 13 August 2026
U.S. Consumer Inflation melambat untuk bulan kedua berturut-turut menjadi 3.4% YoY pada Juli 2026 dari 3.5% YoY pada Juni, sejalan dengan ekspektasi, seiring meredanya dampak kenaikan harga energi akibat perang dengan Iran. Inflasi bensin turun menjadi 24.6% YoY dari 26.7% YoY, bahan bakar minyak menjadi 39.1% YoY dari 42.9% YoY. Sementara secara bulanan, inflasi AS naik 0.1% MoM pada Juli 2026 dari deflasi 0.4% MoM Juni 2026.
Posisi utang pemerintah Indonesia tercatat naik 3.76% MoM menjadi Rp10,293.69 triliun pada Juni 2026, setara dengan 41.26% terhadap Produk Domestik Bruto (PDB). Mayoritas utang, atau sekitar 87.11% dari total utang, bersumber dari penerbitan Surat Berharga Negara (SBN), sementara sisanya adalah komponen pinjaman.
Baca Laporan
Daily Fixed Income Report – 12 August 2026
U.S. Existing Home Sales turun lebih dalam 1.7% MoM menjadi 4.05 juta unit pada Juli 2026 dari penurunan 1.4% MoM pada Juni 2026 dan sedikit di bawah ekspektasi pasar sebesar 4.06 juta unit. Penjualan melemah di wilayah Selatan (-3.1% MoM) dan Midwest (-2.0% MoM). Meski demikian, secara tahunan penjualan masih meningkat 2.4% YoY pada Juli 2026,dengan pasar berpotensi menguat jika rata-rata suku bunga KPR kembali mendekati 6.0%.
Penjualan ritel Indonesia masih mengalami kontraksi 3% YoY pada Juni 2026, tetapi membaik dari kontraksi 3.9% YoY dari Mei 2026. Secara bulanan, penjualan ritel tumbuh 0.7% MoM pada Juni 2026 dari kontraksi 1.5% MoM pada Mei 2026. Penjualan ritel secara tahunan diperkirakan naik 0.9% YoY, sedangkan penjualan ritel secara bulanan diperkirakan turun 0.3% MoM pada Juli 2026.
Baca Laporan
Daily Fixed Income Report – 11 August 2026
Presiden The Fed Cleveland, Beth Hammack dalam pidatonya menilai kebijakan moneter AS saat ini belum cukup restriktif dan kemungkinan diperlukan beberapa kali kenaikan suku bunga The Fed untuk menekan inflasi kembali menuju target 2%. Menurut Hammack, kenaikan sebesar 25 bps saja kemungkinan tidak banyak untuk mengubah kondisi ekonomi, tetapi ia belum ingin menentukan berapa kali kenaikan diperlukan maupun level akhir suku bunga The Fed ditahun ini.
Indeks Keyakinan Konsumen (IKK) tetap berada pada level optimis yaitu di atas level 100, tetapi turun ke level 116.8 pada Juli 2026 dari 117.8 pada Juni 2026. Optimisme konsumen tersebut ditopang oleh Indeks Kondisi Ekonomi Saat Ini (IKE) yang turun menjadi 107.9 pada Juni 2026 dari 109.2 pada Juli 2026 dan Indeks Ekspektasi Konsumen (IEK) yang turun menjadi 125.7 pada Juli 2026 dari 126.4 pada Juni 2026.
Baca Laporan
Single Stock Future
Read More
IPO Summary
Read More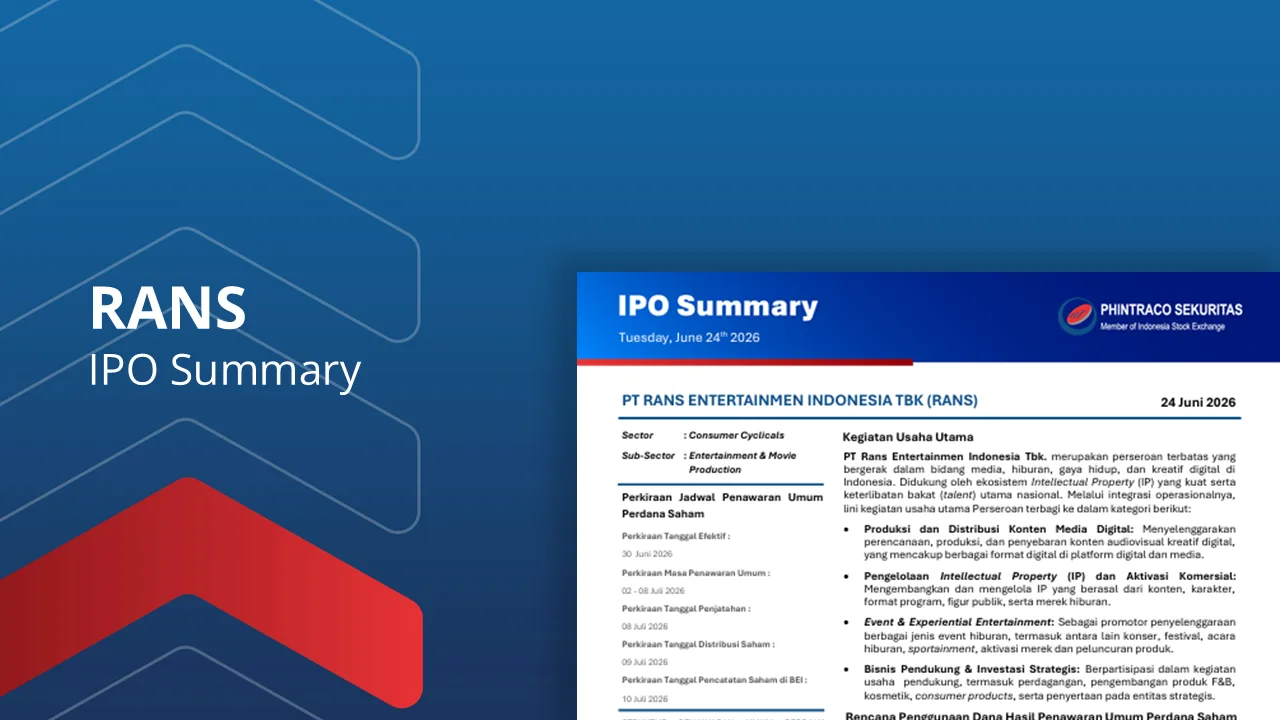
PT Rans Entertainmen Indonesia Tbk (RANS)
Code : RANS
Sector : Consumer Cyclicals
Sub-Sector : Entertainment & Movie Production
---------------------------------------------
PERKIRAAN JADWAL PENAWARAN UMUM PERDANA SAHAM
Perkiraan Tanggal Efektif :
30 Juni 2026
Perkiraan Masa Penawaran Umum :
2 Juli 2026 - 8 Juli 2026
Perkiraan Tanggal Penjatahan :
8 Juli 2026
Perkiraan Tanggal Distribusi Saham :
9 Juli 2026
Perkiraan Tanggal Pencatatan Saham di BEI :
10 Juli 2026
---------------------------------------------
STRUKTUR PENAWARAN UMUM PERDANA SAHAM
Sebanyak-banyaknya sebesar 2,525,000,000 (dua miliar lima ratus dua puluh lima juta) saham biasa atas nama, atau sebanyak-banyaknya sebesar 20.02% (dua puluh koma nol dua persen) dari modal ditempatkan dan disetor Perseroan setelah Penawaran Umum Perdana Saham dengan nilai nominal Rp10,- (sepuluh Rupiah) setiap saham.
Nilai Nominal :
Rp10 per lembar saham
Harga Penawaran :
Rp135 - Rp170 per lembar saham
Jumlah Penawaran Umum :
Sebanyak-banyaknya sebesar Rp429,250,000,000,- (empat ratus dua puluh sembilan miliar dua ratus lima puluh juta Rupiah).
Penjamin Pelaksana Emisi Efek:
PT Trimegah Sekuritas Indonesia
Penjamin Emisi :
Akan ditentukan kemudian
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
PT Bach Multi Global Tbk (BACH)
Code : BACH
Sector : Industrials
Sub-Sector : Diversified Industrial Trading
---------------------------------------------
PERKIRAAN JADWAL PENAWARAN UMUM PERDANA SAHAM
Perkiraan Tanggal Efektif :
29 Juni 2026
Perkiraan Masa Penawaran Umum :
1 Juli 2026 - 3 Juli 2026
Perkiraan Tanggal Penjatahan :
3 Juli 2026
Perkiraan Tanggal Distribusi Saham :
6 Juli 2026
Perkiraan Tanggal Pencatatan Saham di BEI :
7 Juli 2026
---------------------------------------------
STRUKTUR PENAWARAN UMUM PERDANA SAHAM
Sebanyak-banyaknya 615,000,000 (enam ratus lima belas juta) saham biasa atas nama yang merupakan saham baru, dengan nilai nominal Rp50,- (lima puluh Rupiah) setiap saham yang mewakili sebanyak 15.06% (lima belas koma nol enam persen) dari modal yang telah ditempatkan dan disetor penuh setelah Penawaran Umum.
Nilai Nominal :
Rp50 per lembar saham
Harga Penawaran :
Rp400 - Rp500 per lembar saham
Jumlah Penawaran Umum :
Sebanyak-banyaknya sebesar Rp246,000,000,000,- (dua ratus empat puluh enam miliar rupiah) sampai dengan Rp307,500,000,000,-(tiga ratus tujuh miliar lima ratus juta rupiah).
Penjamin Pelaksana Emisi Efek:
PT Erdhika Elit Sekuritas
Penjamin Emisi :
Akan ditentukan kemudian
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
PT Nitrasanata Dharma Tbk (JECX)
Code : JECX
Sector : Healthcare
Sub-Sector : Healthcare Providers
---------------------------------------------
PERKIRAAN JADWAL PENAWARAN UMUM PERDANA SAHAM
Perkiraan Tanggal Efektif :
29 Juni 2026
Perkiraan Masa Penawaran Umum :
1 Juli 2026 - 3 Juli 2026
Perkiraan Tanggal Penjatahan :
3 Juli 2026
Perkiraan Tanggal Distribusi Saham :
6 Juli 2026
Perkiraan Tanggal Pencatatan Saham di BEI :
7 Juli 2026
---------------------------------------------
STRUKTUR PENAWARAN UMUM PERDANA SAHAM
Sebanyak-banyaknya 487,983,500 saham biasa, yang terdiri dari (i) 325,322,300 saham baru yang dikeluarkan dari portepel Perseroan yang mewakili 10.00% dan (ii) 162,661,200 saham milik DR.Dr. Waldensius Girsang, SpM(K) yang mewakili 5.00% dari modal ditempatkan dan disetor Perseroan setelah Penawaran Umum Perdana Saham yang mana seluruhnya sejumlah sebanyak-banyaknya 15% dari modal ditempatkan dan disetor Perseroan setelah Penawaran Umum Perdana Saham dengan nilai nominal Rp16,- (enam belas Rupiah) setiap saham.
Nilai Nominal :
Rp16 per lembar saham
Harga Penawaran :
Rp1,200 - Rp1,400 per lembar saham
Jumlah Penawaran Umum :
Sebanyak-banyaknya sebesar Rp683.176.900.000 (enam ratus delapan puluh tiga miliar seratus tujuh puluh enam juta sembilan ratus ribu Rupiah)
Penjamin Pelaksana Emisi Efek:
PT Trimegah Sekuritas
Penjamin Emisi :
Akan ditentukan kemudian
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Company Flash
Read More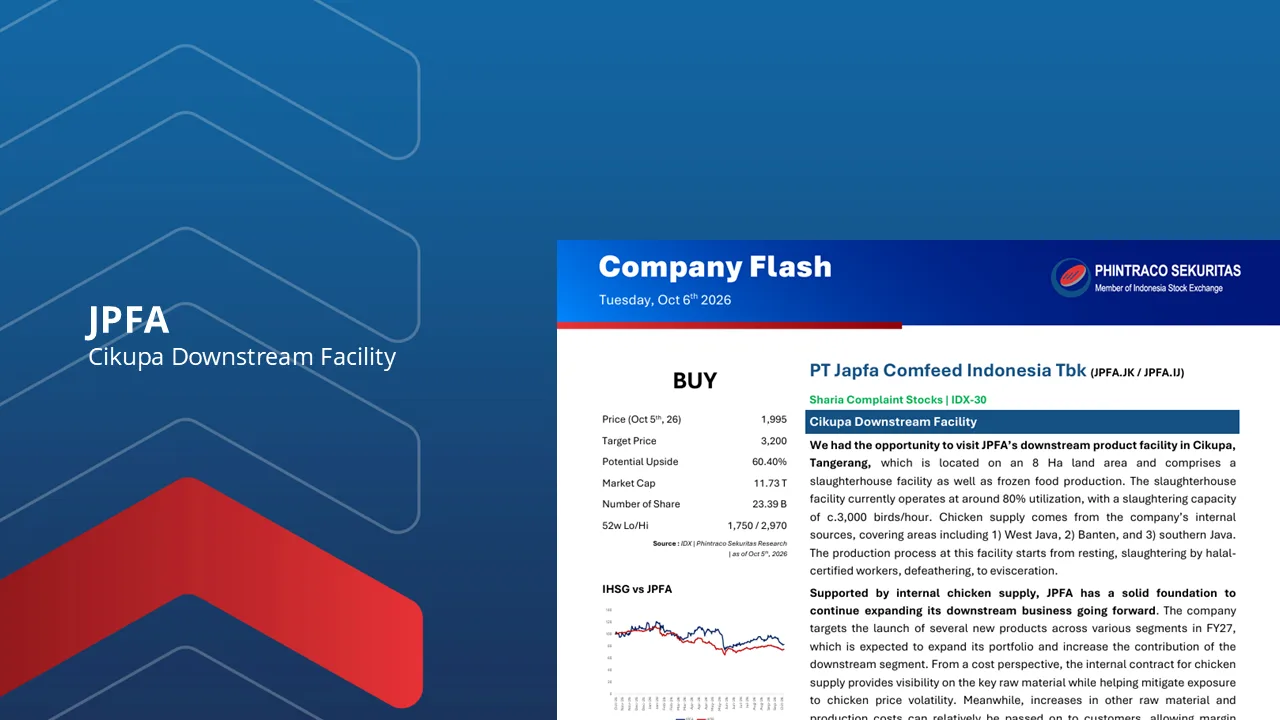
JPFA: Site Visit Notes – Cikupa Downstream Facility
Phintraco Sekuritas Company Flash
PT Japfa Comfeed Indonesia Tbk - JPFA.IJ
Aditya Prayoga
JPFA: Site Visit Notes – Cikupa Downstream Facility
>We visited JPFA’s downstream product facility in Cikupa, Tangerang, which spans 8 Ha and comprises a slaughterhouse and frozen food production facility. The slaughterhouse currently operates at c.80% utilization, with a slaughtering capacity of c.3,000 birds/hour.
>Chicken supply is sourced internally, covering West Java, Banten, and southern Java. The production process includes resting, slaughtering by halal-certified workers, defeathering, and evisceration.
>Supported by internal chicken supply, JPFA has a solid foundation to continue expanding its downstream business. The company targets the launch of several new products across various segments in FY27, which should expand its portfolio and increase downstream contribution.
>The internal chicken supply contract provides greater visibility on the key raw material cost and helps mitigate exposure to chicken price volatility. Meanwhile, increases in other raw material and production costs can relatively be passed on to customers, helping keep margin pressure manageable alongside product expansion.
>Downstream growth remains solid, with nearly all categories recording positive growth in 1H26. RTC, both premium and affordable, grew 54% YoY and 5% YoY, respectively, while RTE and RTD grew 60% YoY and 15% YoY. Fresh chicken recorded significant growth of 532% YoY.
>Based on distribution mapping, 68% of 1H26 sales still came from general trade, while modern trade contributed a relatively smaller portion. This leaves room to increase modern market penetration and shift the product mix toward higher value-added products and ASP.
>Key risks include weaker live bird/DOC prices, higher raw material costs that could pressure margins, and weak consumer purchasing power.
By PHINTRACO SEKURITAS | Research
— Disclaimer On —
Baca Laporan
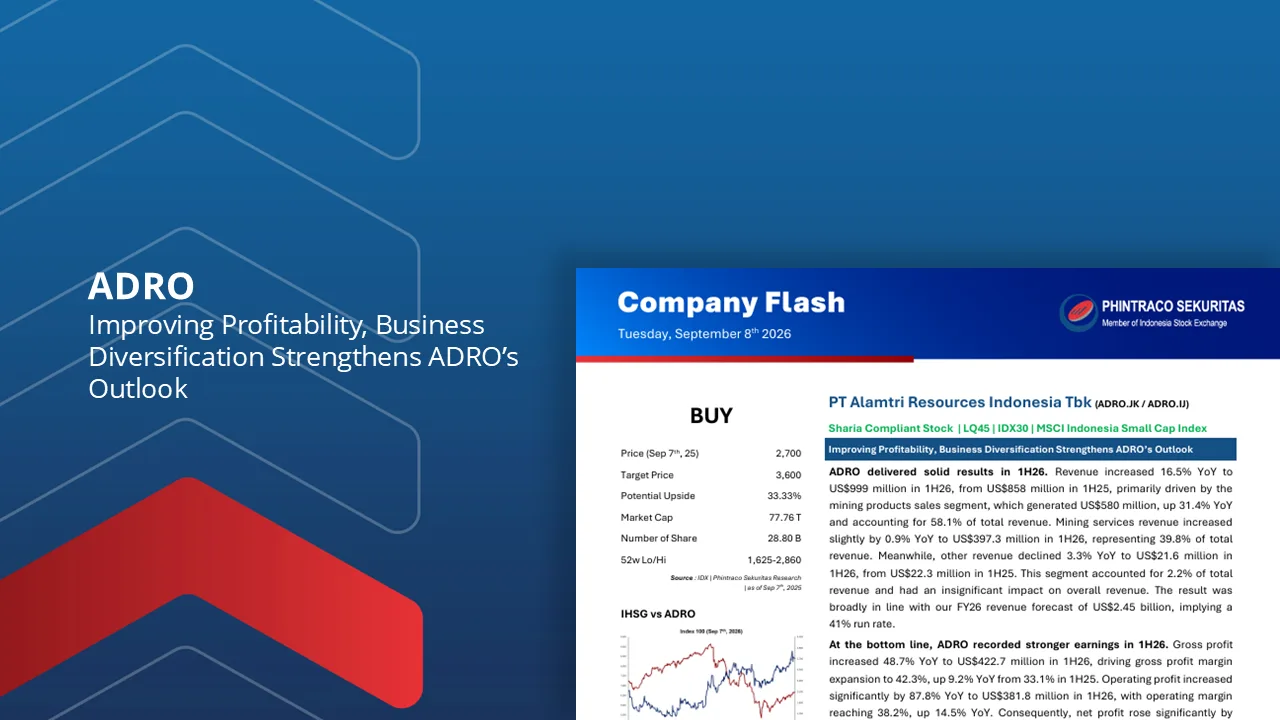
ADRO : Improving Profitability, Business Diversification Strengthens ADRO’s Outlook
ADRO delivered solid top-line growth in 1H26, with revenue increasing 16.5% YoY to US$999 million, reaching 41% of our FY26 forecast. Growth was primarily driven by mining products sales, which rose 31.4% YoY to US$580 million and accounted for 58.1% of total revenue.
ADRO’s profitability strengthened significantly in 1H26. Gross profit rose 48.7% YoY to US$422.7 million, driving GPM expansion to 42.3%, while operating profit increased 87.8% YoY to US$381.8 million. Net profit grew 76.8% YoY to US$309.4 million, achieving 54% of our FY26 forecast.
Earnings growth was supported by a 24% YoY increase in ASP to US$185.9/ton in 1H26. The stronger ASP was underpinned by resilient coal prices throughout 2026, driven by higher energy prices, particularly oil, amid ongoing geopolitical tensions in the Middle East.
ADRO’s future growth will increasingly be supported by AADI and ADMR, further strengthening the Group’s revenue diversification. AADI is expected to contribute US$804.23 million in FY26 net profit, while ADMR could enter a new growth phase as its aluminium smelter targets first-phase full capacity of 500 thousand tons by end-2026.
Key risks include weaker global steel demand, commodity price volatility, and potential operational disruptions from prolonged drought conditions around rivers in Kalimantan.
By PHINTRACO SEKURITAS | Research
-Disclaimer On -
Baca Laporan
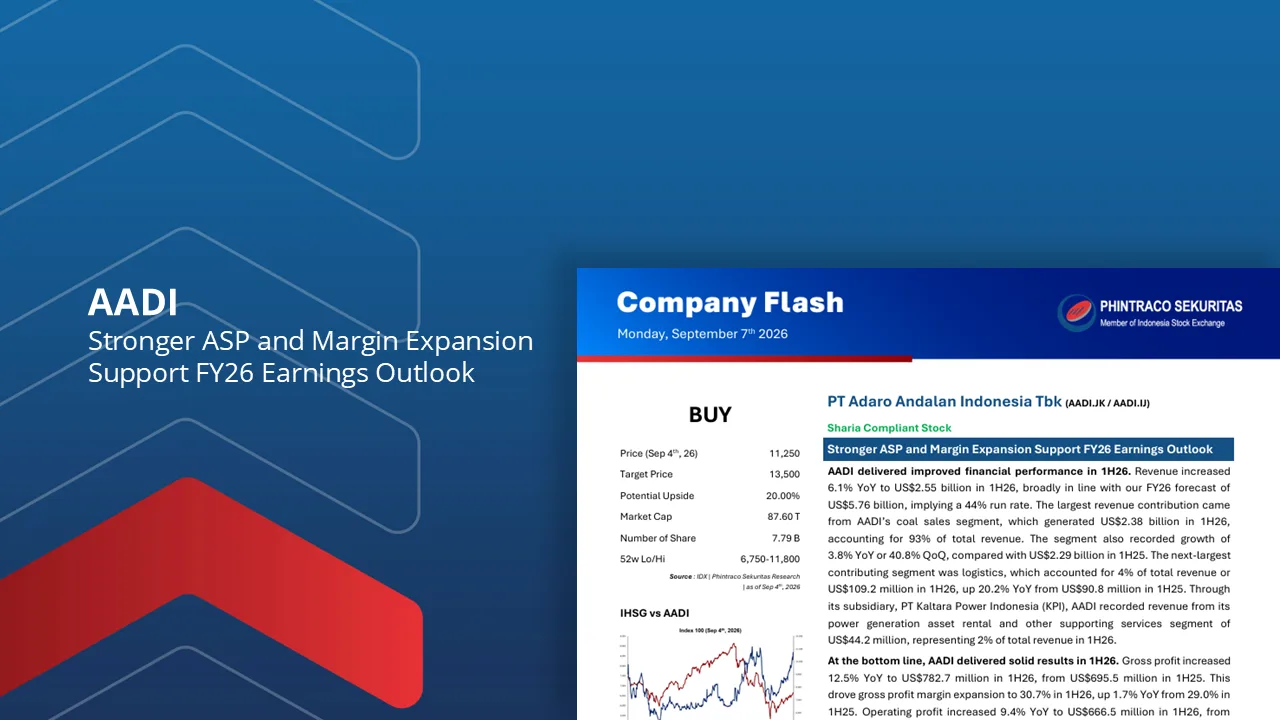
AADI : Stronger ASP and Margin Expansion Support FY26 Earnings Outlook
AADI delivered solid top-line growth in 1H26. Revenue increased 6.1% YoY to US$2.55 billion, reaching 44% of our FY26 forecast. Coal sales remained the key contributor at US$2.38 billion, or 93% of total revenue, while logistics revenue grew 20.2% YoY to US$109.2 million.
AADI’s profitability strengthened in 1H26. Gross profit rose 12.5% YoY to US$782.7 million, driving GPM expansion to 30.7%, while operating profit increased 9.4% YoY to US$666.5 million. Net profit grew 10.5% YoY to US$473.8 million, achieving 59% of our FY26 estimate.
AADI’s operational performance improved sequentially despite a slight YoY decline. Production and sales volumes declined 1% YoY, but increased 17% QoQ and 22% QoQ, respectively, in 2Q26. Meanwhile, ASP rose 5% YoY to US$71.1/ton, supported by stronger coal prices amid Middle East geopolitical tensions.
Our FY26 earnings outlook remains supported by stronger coal prices and potential additional proceeds from the Kestrel divestment. Key risks include commodity price volatility, regulatory uncertainty, and prolonged drought-related operational disruptions.
By PHINTRACO SEKURITAS | Research
-Disclaimer On -
Baca Laporan
Company Update
Read More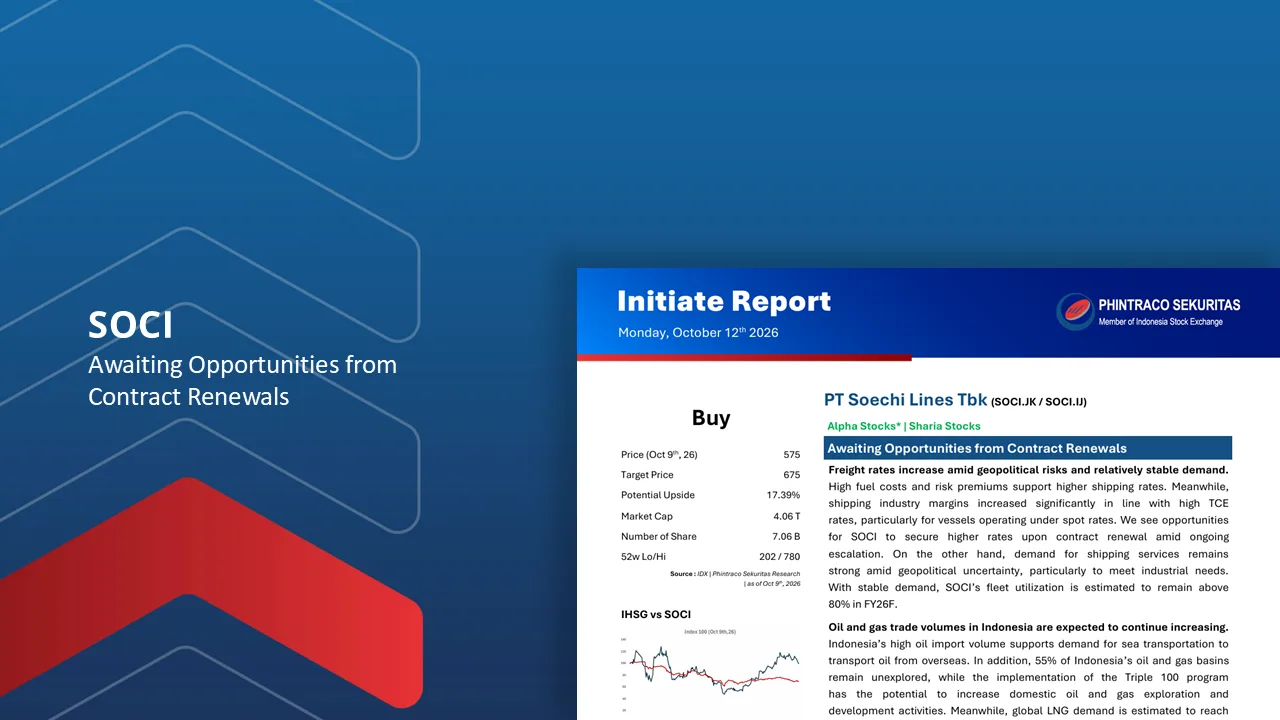
SOCI: Awaiting Opportunities from Contract Renewals
Freight rates increase amid geopolitical risks and relatively stable demand. VLCC TCE rates remain above US$500 thousand/day, supported by higher fuel costs and risk premiums. SOCI’s fleet utilization is targeted to remain above 80% in FY26F, with opportunities to secure higher rates upon contract renewal.
Indonesia’s oil and gas transportation demand is supported by high oil imports, while around 55% of its 128 oil and gas basins remain unexplored. The government’s Triple 100 program may further support exploration and development activities, creating opportunities for tanker transportation and FSO services.
Global LNG demand is estimated at 406 million tonnes in FY26F, with 63% coming from Asia, and is projected to increase to 466 million tonnes in FY27F (+14.7% YoY). Indonesia’s LNG exports reached 14 million tonnes in FY25, providing opportunities for LNG shipping services.
Baca Laporan
SOCI continues to expand its international operations and tanker fleet, particularly MR and Aframax vessels. The Sustainable Sukuk Ijarah program targets up to IDR 3 trillion, while the shipyard served 37 vessels in 2025, providing additional growth opportunities.
We estimate FY26F revenue at US$163.3 million (+5% YoY), with gross profit of US$52 million (+25% YoY), EBITDA of US$71 million (+76% YoY), and net profit of US$34 million (+341% YoY). Lower docking and vessel repair costs are expected to support profitability, with cost of revenue estimated at US$111.7 million (-2% YoY). By PHINTRACO SEKURITAS | Research – Disclaimer On –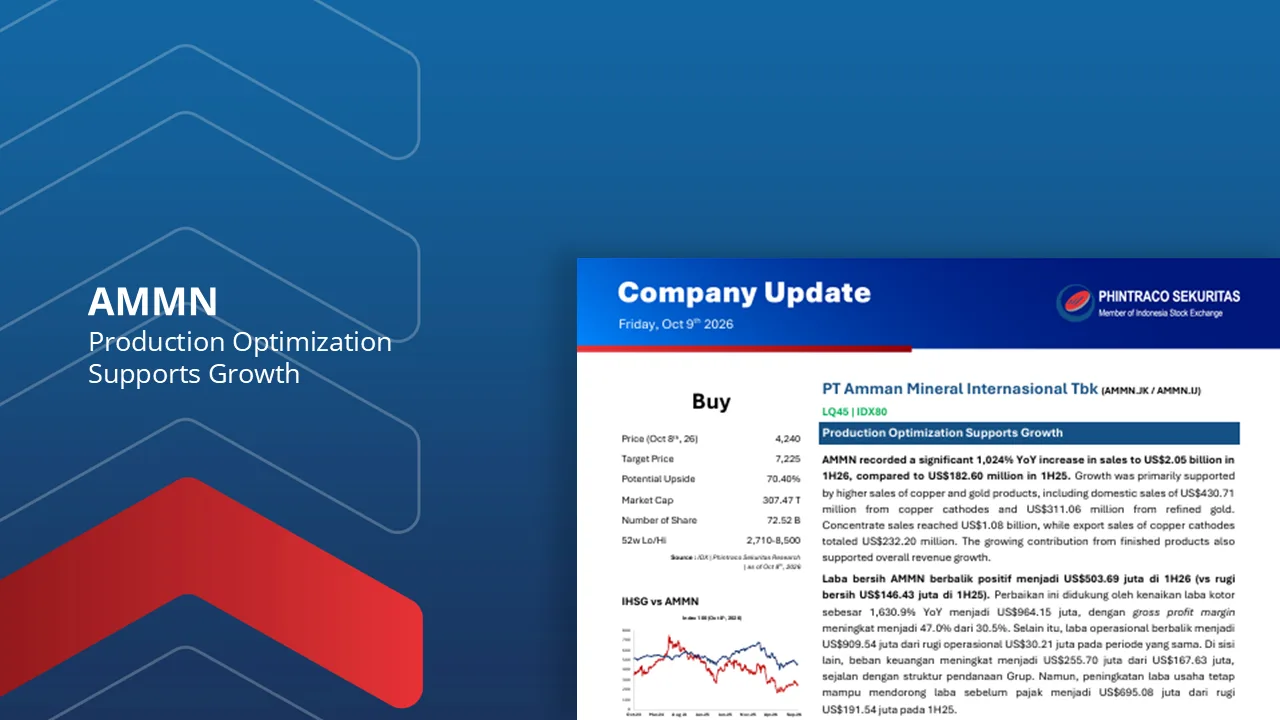
AMMN: Production Optimization Supports Growth
Sales surged by 1,024% YoY to US$2.05 billion in 1H26, compared to US$182.60 million in 1H25, supported by higher sales of copper and gold products. Concentrate sales contributed US$1.08 billion, while domestic sales of copper cathodes and refined gold reached US$430.71 million and US$311.06 million, respectively.
AMMN turned profitable in 1H26, recording a net profit of US$503.69 million, compared to a net loss of US$146.43 million in 1H25, supported by stronger revenue and improved operational performance.
Gross profit surged by 1,630.9% YoY to US$964.15 million, with the gross profit margin expanding to 47.0% from 30.5%. Operating profit also turned positive at US$909.54 million, compared to an operating loss of US$30.21 million in 1H25.
Finance costs increased to US$255.70 million from US$167.63 million, reflecting the Group's funding structure. Nevertheless, stronger operating profit lifted pre-tax profit to US$695.08 million, reversing a pre-tax loss of US$191.54 million in 1H25.
FY26F performance is expected to strengthen, supported by optimized production at Batu Hijau and downstream contributions from the AMIN smelter. Copper and gold production are forecast at 485 Mlbs and 775 koz, respectively, while revenue and net profit are projected to rise by 117.17% YoY to US$4.20 billion and reach US$967 million, respectively.
By PHINTRACO SEKURITAS | Research
-Disclaimer On -
Baca Laporan
DSSA: Diversification Towards an Integrated Energy and Technology Ecosystem
DSSA recorded solid 1H26 performance, with revenue increasing 33.98% YoY to US$1,772 million and net profit rising 67.3% YoY to US$286 million, supported by higher coal sales volumes, stronger technology contribution, and operational efficiencies.
Coal mining and trading remained the main revenue contributor, growing 29.8% YoY to US$1,531 million, equivalent to 86% of total revenue. The cable TV and internet segment also grew strongly by 95.6% YoY to US$170.5 million, supported by the MORA business combination.
The MORA merger strengthens DSSA’s technology and telecommunications portfolio, expanding its capabilities in telecommunications infrastructure, cable TV and internet services, and data centers. The merger was effective on April 22, 2026, with MORA as the surviving entity.
DSSA continues to diversify beyond coal, with investments across digital platforms, satellites, power generation, and renewable energy. These initiatives support greater vertical integration across the energy and technology value chain and provide potential long term growth opportunities.
DSSA trades at a premium valuation despite being Not Rated, with a PER of 35.27x and PBV of 5.86x, above the oil, gas, and coal subsector averages of 13.01x and 3.03x, respectively. Key catalysts include further expansion in technology, telecommunications, renewable energy, and digital businesses, while key risks include coal price volatility and regulatory developments.
Full report :
By PHINTRACO SEKURITAS | Research
-Disclaimer On -
Baca Laporan
Sectoral Update
Read More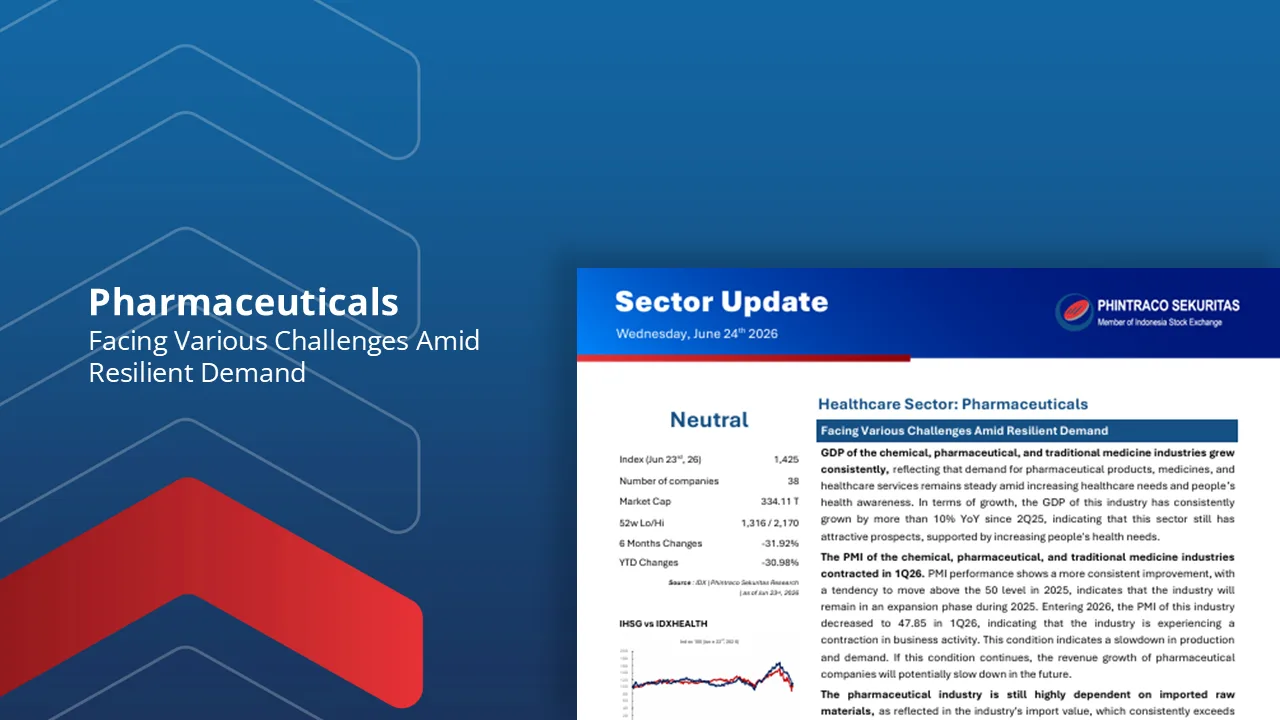
Pharmaceuticals Sector: Facing Various Challenges Amid Resilient Demand
GDP of the chemical, pharmaceutical, and traditional medicine industries grew consistently, reflecting that demand for pharmaceutical products, medicines, and healthcare services remains steady amid increasing healthcare needs and people’s health awareness.
The PMI of the chemical, pharmaceutical, and traditional medicine industries contracted in 1Q26. This condition indicates a slowdown in production and demand. If this condition continues, the revenue growth of pharmaceutical companies will potentially slow down in the future.
The pharmaceutical industry is still highly dependent on imported raw materials, as reflected in the industry's import value, which consistently exceeds its export value. This condition has caused the sector’s trade balance to consistently experience a deficit.
The performance of the pharmaceutical companies in our coverage
is mixed. KLBF booked revenue growth of 10.13% YoY in 1Q26. This growth was driven by increased sales across all business segments.
Downside risks in this sector include a more-than-expected weakening of purchasing power, restrictions on expansion, and intense competition with e-commerce platforms. Meanwhile, SIDO booked a revenue decrease of 18.83% YoY in 1Q26, primarily due to SIDO’s inventory normalization efforts in its distribution channels.
Downside risks in this sector include dependence on imported raw materials, the risk of changes in pharmaceutical regulations, and intense competition between industry players.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Plantation: Demand Takes the Lead
**Phintraco Sekuritas Sector Update**
**Plantation Sector**
**Aditya Prayoga**
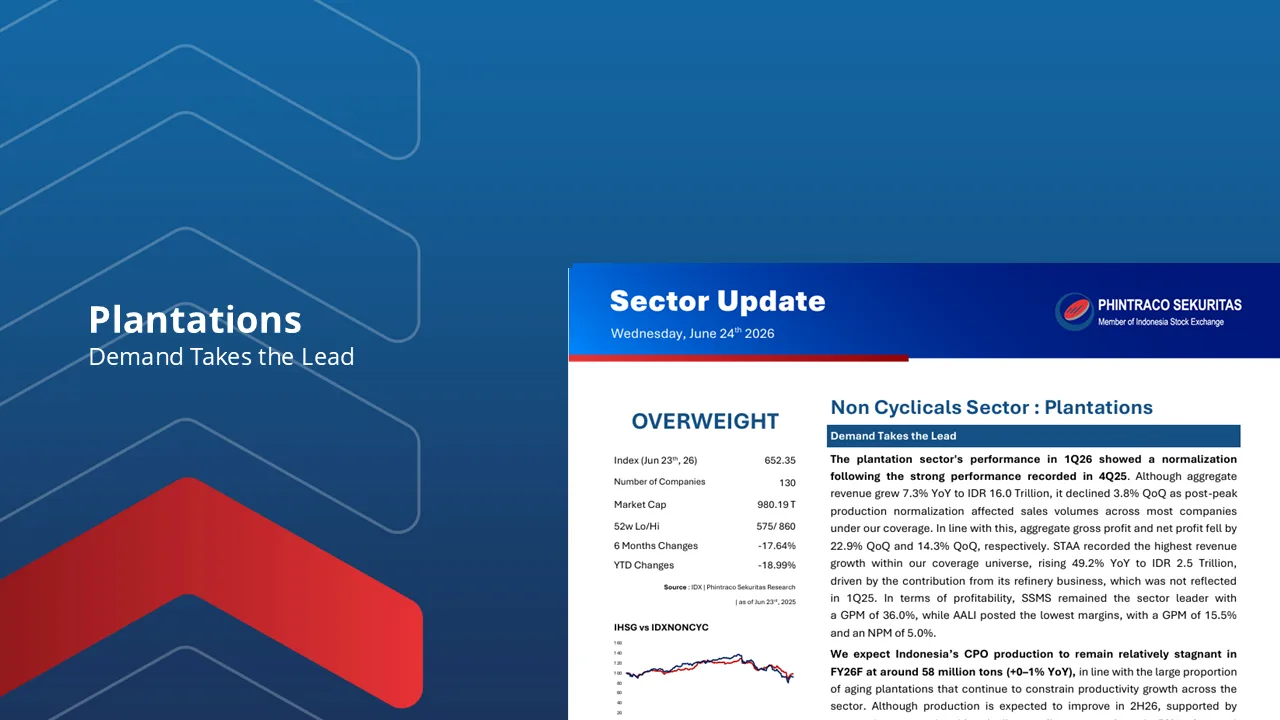
> The plantation sector's performance in 1Q26 showed a quarterly normalization following the strong performance recorded in 4Q25. Aggregate revenue grew 7.3% YoY to IDR 16.0 Trillion, but declined 3.8% QoQ as the peak production and harvesting season came to an end, resulting in lower sales volumes across most companies under our coverage. A similar trend was reflected in aggregate gross profit and net profit, which declined by 22.9% QoQ and 14.3% QoQ, respectively.
> STAA recorded the strongest growth within our coverage universe, with revenue rising 49.2% YoY to IDR 2.5 Trillion, driven by the contribution from its refinery business, which was not reflected in 1Q25. However, its quarterly performance also normalized, with revenue and net profit declining by 20.0% QoQ and 31.6% QoQ, respectively. In terms of profitability, SSMS remained the sector leader with a GPM of 36.0%, while AALI posted the lowest margins, with a GPM of 15.5% and an NPM of 5.0%.
>We expect Indonesia’s CPO production to remain relatively stagnant in FY26F at around 58 million tons (+0–1% YoY) While 2H26 production is likely to be slightly stronger than 1H26, supported by seasonal patterns where approximately 53% of annual output is generated in the second half, we believe the improvement will be largely seasonal in nature.
>Looking ahead, the potential emergence of El Niño in 2H26 remains a factor worth monitoring. Nevertheless, we believe the risk to FY26F production remains relatively limited, given that weather-related impacts on palm oil productivity typically materialize with a lag of 9–12 months. As a result, any stronger-than-expected El Niño event is more likely to affect the FY27F production outlook rather than FY26F.
> On the demand side, the implementation of the mandatory B50 biodiesel program, effective from 1 July 2026, is expected to significantly increase domestic CPO consumption. Based on the government’s simulation, CPO demand for biodiesel could rise to approximately 17.9 million tons (+33.4%), creating additional demand of around 4.35 million tons compared to the current B40 scheme. As domestic demand growth is expected to outpace supply growth, market balances could tighten further and support CPO prices.
> External demand is also expected to remain supportive. India's seasonal restocking cycle ahead of the Diwali festival is likely to strengthen imports during 2H26, while recent data suggest that China's palm oil imports are beginning to recover after several years of decline. We believe these factors should help absorb additional supply entering the market during the second half of the year.
>Downside risks to our view include: (1) volatility in CPO and other vegetable oil prices, (2) changes in biodiesel or export policies, and (3) higher-than-expected fertilizer and operating costs resulting from geopolitical tensions and global supply chain disruptions.
Full Report : https://phintracosekuritas.com/
By PHINTRACO SEKURITAS | Research
– Disclaimer On –
Baca Laporan
Telco : Monetization Remains the Key Earnings Driver
**Phintraco Sekuritas Sector Update**
**Telecommunication Sector**
**Aditya Prayoga**
**Telecommunication: **Monetization Remains the Key Earnings Driver**
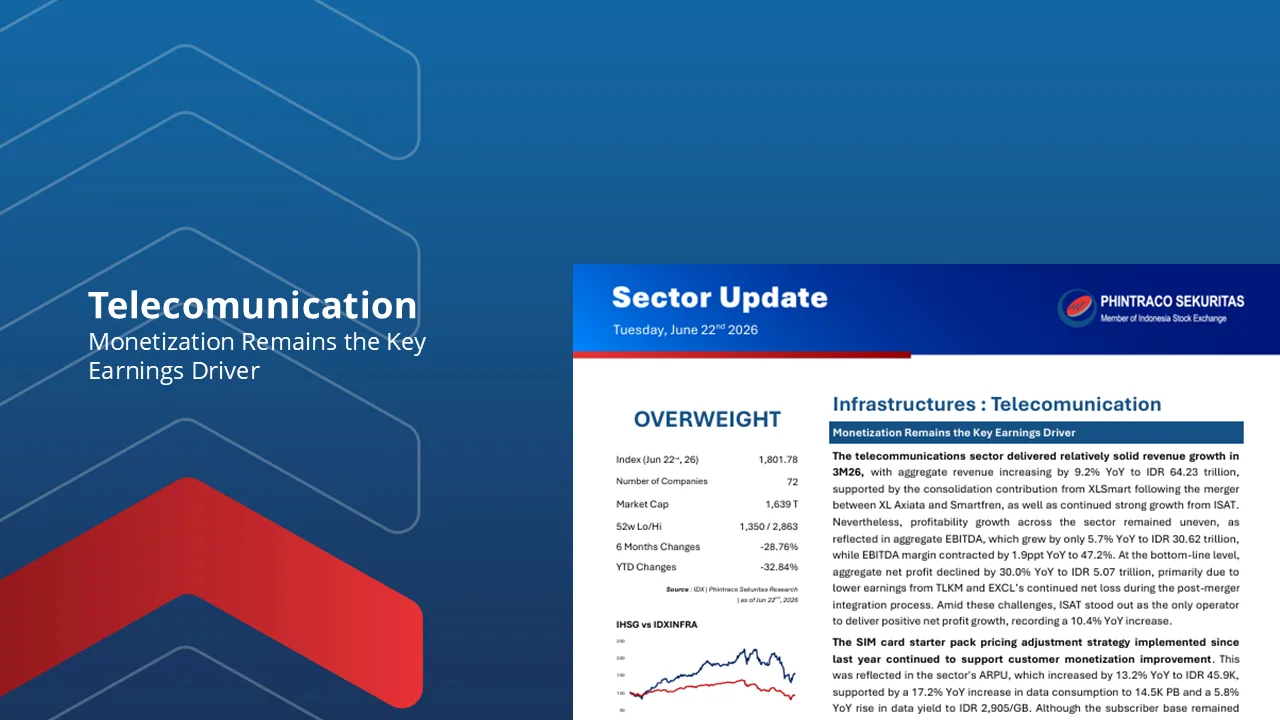
> The telecommunications sector delivered relatively solid earnings growth in 3M26, with aggregate revenue increasing 9.2% YoY to IDR 64.23 Trillion. The growth was primarily driven by the consolidation impact at EXCL following the merger of XL Axiata and Smartfren into XLSmart, which lifted EXCL's revenue by 37.4% YoY to IDR 11.82 Trillion. Excluding the merger impact, sector growth was more moderate, as reflected in revenue growth of 12.1% YoY at ISAT and 1.5% YoY at TLKM.
> On the profitability front, sector EBITDA increased 5.7% YoY to IDR 30.62 Trillion. However, EBITDA margin contracted to 47.2% (-1.9ppt YoY), indicating that revenue growth has yet to be fully accompanied by operating efficiency improvements. At the bottom-line level, aggregate net profit declined 30.0% YoY to IDR 5.07 Trillion, primarily due to weaker earnings from TLKM and the ongoing post-merger integration process at EXCL.
> The SIM card starter pack repricing strategy implemented since last year continued to support customer monetization improvement. This was reflected in sector ARPU, which increased 13.2% YoY to IDR 45.9K, supported by a 17.2% YoY increase in data consumption to 14.5K PB and higher average data usage per subscriber, reaching 48.3 GB (+15.7% YoY). As a result, sector data yield improved by 5.8% YoY to IDR 2,905/GB.
> Despite the strong improvement in monetization, the aggregate subscriber base remained relatively stable at 320.1 million subscribers (+2.3% YoY; -0.8% QoQ), suggesting that industry growth is increasingly being driven by improving revenue quality rather than subscriber expansion. Among operators, TLKM recorded the strongest data yield growth (+25.9% YoY), while ISAT continued to deliver robust data traffic growth (+25.1% YoY).
> Looking ahead, we see two key catalysts that could shape the sector in FY26, namely the upcoming 700 MHz and 2.6 GHz spectrum auctions and the implementation of facial verification-based SIM registration starting in July 2026. We believe both initiatives have the potential to improve network capacity while enhancing the quality of the industry's subscriber base.
> While facial verification-based SIM registration could lead to a c.5–10% decline in subscriber numbers in the near term due to customer base cleansing, we view the impact positively as it should improve subscriber quality and support stronger monetization. At the same time, additional spectrum allocation is expected to strengthen network quality and support future data traffic growth.
> Downside risks to our view include: (1) weaker-than-expected ARPU growth due to softer consumer purchasing power, (2) a larger-than-expected decline in subscriber numbers following customer base cleansing, and (3) higher-than-expected spectrum acquisition costs and capex requirements.
Full Report : https://phintracosekuritas.com
By PHINTRACO SEKURITAS | Research
– Disclaimer On –
Baca Laporan
Macro Flash
Read More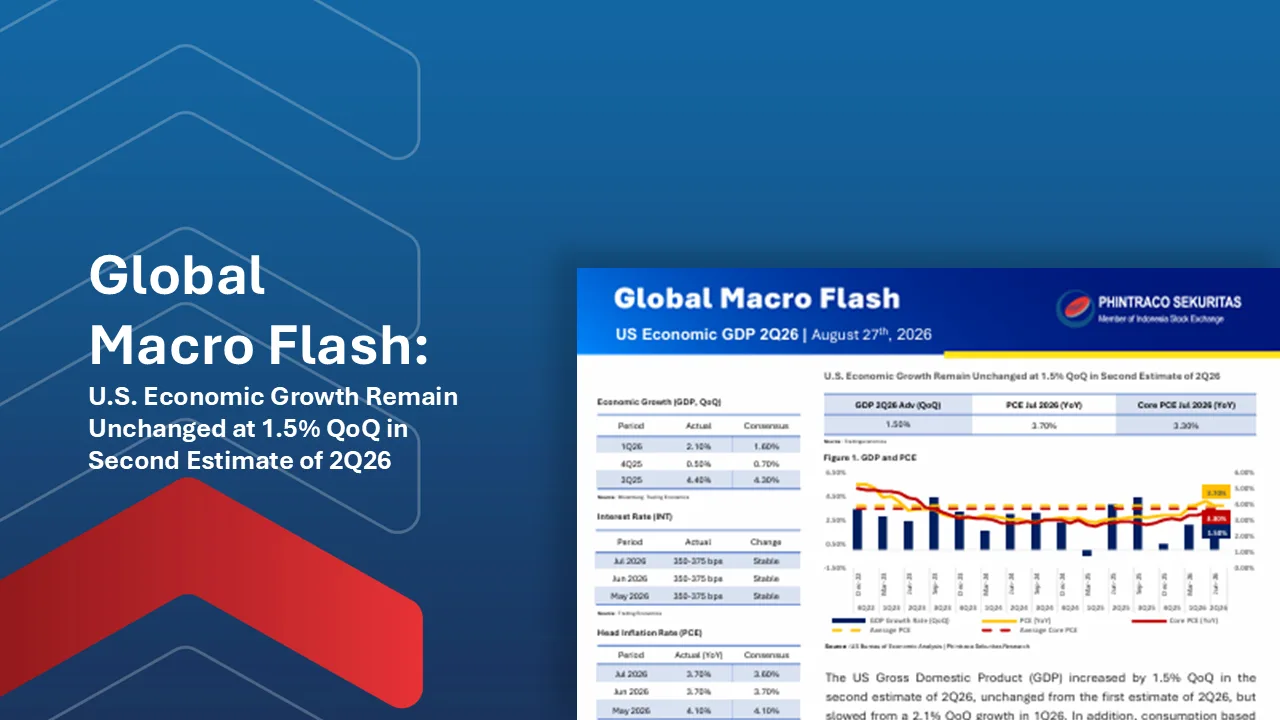
U.S. Economic Growth Remain Unchanged at 1.5% QoQ in Second Estimate of 2Q26
GDP Growth Rate 2Q26 Adv. Est: 1.50% QoQ
PCE July 2026: 3.70% YoY
Core PCE July 2026: 3.30% YoY
The US Gross Domestic Product (GDP) rose by 1.5% QoQ in the second estimate of 2Q26, unchanged from the first estimate of 2Q26, but slowed from a 2.1% QoQ growth in 1Q26. Consumption-based inflation indicators were recorded stable as shown by Personal Consumption Expenditure (PCE) of 3.7% YoY and Core PCE of 3.3% YoY in July 2026, but still well above the Fed’s 2% inflation target. In addition, the US personal income rose for nine consecutive months to US$27.11 trillion or grew by 0.4% MoM in July 2026 from a 0.2% MoM growth in June 2026, reflected the resilience of the US economy amid energy disruption and high borrowing costs.
By PHINTRACO SEKURITAS | Research
-Disclaimer On-
Baca Laporan
Indonesia’s M2 Grew 8.3% YoY in July 2026, Driven by Growth in M1 and Quasi-Money
Broad money supply (M2) was recorded at IDR 10,371.1 trillion, growing by 8.3% YoY in July 2026, slowing from 8.7% YoY growth in June 2026. By component, the growth was driven by both narrow money supply (M1) and quasi-money. M1 was recorded at IDR 5,908.7 trillion, growing by 10.0% YoY in July 2026, while quasi-money stood at IDR 4,375.9 trillion, growing by 5.6% YoY. In addition, M2 growth in July 2026 was primarily supported by loan growth of 13.0% YoY and a 4.6% YoY increase in net claims on the central government.
Baca Laporan
Bank Indonesia Keeps BI Rate at 5.75% in August 2026
BI Rate: 5.75%
Deposit Facility: 4.75%
Lending Facility: 6.50%
BI maintained the BI Rate at 5.75% while prioritizing Rupiah stability and inflation control, and continued to support sustainable economic growth through monetary and macroprudential measures. The unchanged 200 bps BI Rate–FFR spread, together with foreign fund flows shifting from equities toward SBN and SRBI, indicates investors’ preference for relatively lower-risk domestic assets amid global uncertainty. Going forward, BI is expected to remain focused on exchange rate stability, liquidity management, and maintaining the attractiveness of Indonesian assets to support sustainable economic growth.
Baca Laporan
Market Outlook
Read More
Higher for Longer: The New Market Reality
Middle East geopolitical tensions disrupted global energy supply, pushing up oil prices and increasing pressure on inflation, exchange rates, and global monetary policy.
The US–Iran peace agreement and the planned reopening of the Strait of Hormuz improved market sentiment and eased oil prices, although geopolitical risks remain.
Global growth is expected to moderate in 2026, with persistent market volatility driven by energy prices, inflation, and higher-for-longer interest rates.
Indonesia targets 5.4% GDP growth in 2026, supported by fiscal stimulus, while inflation is expected to remain within Bank Indonesia's target range in 2H26.
Bank Indonesia is expected to maintain a tight monetary stance amid Rupiah depreciation, global rate pressures, and inflation risks.
Fiscal conditions remain manageable, with the 2026 budget deficit reaching 0.7% of GDP by May, still well below the full-year target despite widening from last year.
Foreign investors are likely to remain cautious, as the market awaits MSCI's market accessibility review and S&P's sovereign credit rating assessment.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Global Economic Research : Embracing the Economic Dynamics of 2026
Global economic growth is expected to keep slowing amid high global uncertainty. This situation continues to weigh on trade, investment, and overall economic performance.
U.S. President Donald Trump’s import tariff policies have created uncertainty, though recent negotiations indicate potential progress. Efforts toward a U.S.–China trade deal, including partial tariff cuts and delayed export restrictions, are offset by new risks from stricter transshipment monitoring.
Artificial Intelligence (AI) is transforming the global economy by automating production and addressing labor shortages. The integration of AI and robotics enhances industrial efficiency and supports productivity through adaptive labor and migration policies.
Global inflation pressures have eased except in the U.S., Europe, and the U.K., driven by import tariffs and strong demand. Several major central banks have started to cut interest rates, while others remain cautious to maintain stability.
Global fiscal conditions are becoming more fragile due to geopolitical tensions, U.S. tariff policies, and high public debt. Expansionary fiscal policies and rising interest rates are increasing debt costs and limiting fiscal space.
Geopolitical tensions continue to disrupt supply chains, raising energy and food prices. However, global commodity prices in 2025 show mixed trends, influenced by weaker demand, supply disruptions, and climate change.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Indonesia Economic Research: Embracing the Economic Dynamics of 2026
Indonesia's economy is projected to grow 5.0%-5.2% YoY in 2026. Indonesia's economic growth is expected to accelerate in 2026, in line with expectations of improving global conditions and increased domestic investment activity.
Consumer confidence index and retail sales are expected to remain positive in 2026. Supported by the government's stimulus program, assuming controlled inflation and consumption incentive.
Inflation in 2026 is expected to remain within BI's target range of 2.5% ± 1%. This projection is based on relatively stable inflation expectations at low levels, the stability of the Rupiah exchange rate, and synergistic efforts by Bank Indonesia and the Government.
The opportunity for further cuts by Bank Indonesia (BI) Rate remains possible in 2026. This projection is based on relatively stable inflation expectations at low levels, the stability of the Rupiah exchange rate, and synergistic efforts by Bank Indonesia and the Government.
The allocation of government funds in banks has positively influenced national liquidity. By September 2025, the adjusted base money rose to Rp2,152.4 trillion, up from Rp1,961.34 trillion in August 2025.
The 2026 APBN deficit is targeted at 2.68% of GDP. The 2026 APBN targets state revenue at IDR 3,153.6 trillion, comprising IDR 2,357.7 trillion in tax revenue and IDR 336 trillion in customs and excise revenue.
IHSG's conservative level for 2026 is estimated at 9,255 and its aggressive level at 9,883.
Sectoral Coverage: Banks, Properties & Real estate, F&B and Poultry, Retails, Telecommunication, Tower, Coal, Pharmaceuticals, Plantations, Construction, Metals & Mining, Industrial, and Cement.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Monthly Strategy
Read More
Equity : Balancing Uncertainty, Gradual Recovery Ahead
-October 2026-
Global Highlight: The Fed raised its policy rate by 25 bps to 3.75%–4.00% in September 2026 amid persistent inflation and higher oil prices. The Fed signaled one potential additional hike in 2026, while the U.S. labor market remained solid with nonfarm payrolls rising by 162k, despite wage growth slowing to 3.1% YoY. Global monetary tightening could further tighten financial conditions and keep bond yields elevated.
Indonesia Highlight: Bank Indonesia kept its policy rate at 5.75% in September 2026 despite the Fed’s rate hike, narrowing the BI Rate–Fed Rate spread to 1.75%, but still above the five-year average. Inflation rose to 3.28% YoY, while manufacturing PMI returned to expansion at 52.4 and the trade surplus widened to US$3.55 billion in August. The 2027 state budget remains expansionary, targeting a 2.4% of GDP deficit and 6.0% economic growth, although high global rates and bond yields could constrain fiscal space.
IHSG View: Global equity markets remain highly volatile amid rising bond yields, oil prices, and geopolitical uncertainty. The IHSG’s direction will be influenced by U.S. inflation and labor data, Fed policy, UST yields, oil prices, and the 3Q26 earnings season. While a rebound remains possible, investors will also monitor the potential Fed rate hike in October and MSCI’s announcement in November. We maintain our IHSG target at 7,000 by end-2026.
Sector Allocation:
Banks, Coal, Metals Mining, Oil & Gas, Retailers, and Industrial. Read more for the Stock pick.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Equity Monthly Strategy : Global Rates Remain Key to Market Direction
-September 2026-
Global Highlight: Global growth remained resilient despite a moderation in the U.S. economy, with real GDP growth slowing to 1.5% in 2Q26 from 2.1% in 1Q26. Meanwhile, U.S. inflation eased to 3.4% YoY in July, although PCE and core PCE remained elevated at 3.7% and 3.3%, respectively, keeping inflation well above the Fed’s 2% target. Persistent inflation alongside moderating growth could reinforce a higher-for-longer Fed policy stance, while keeping the possibility of further rate hikes open.
Indonesia Highlight: Bank Indonesia maintained the BI Rate at 5.75% while strengthening policy measures to support Rupiah stability and sustainable economic growth. Indonesia’s economy grew 5.29% YoY in 2Q26, moderating from 5.61% in 1Q26 amid slower household consumption and government spending, while loan growth remained strong at 13.58% YoY in July. Meanwhile, inflation accelerated to 3.19% YoY in August and manufacturing PMI fell into contraction territory, highlighting moderating domestic activity and downside risks to the 2026 growth outlook.
IHSG View: Global equity markets remained volatile in August 2026 amid rising U.S. Treasury yields, shifting expectations for the Fed’s September decision, and elevated energy prices due to ongoing Middle East tensions. Domestically, the JCI rebounded 4.64% MoM, supported by improving Rupiah performance, easing concerns over the domestic outlook, and reduced foreign selling pressure, although it remained down 24.53% YTD. Going forward, tighter global financial conditions and narrower Indonesia–U.S. yield spreads could continue to pressure capital flows and the Rupiah, favoring a more selective and short term trading approach amid elevated market volatility.
Sector Allocation: Telecommunication, Poultry, Retailers, Coal, Metal Mining, and Oil & Gas. Read more for the Stock pick.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan
Equity Monthly Strategy : Road to Recovery amid Persistent Uncertainty
-August 2026-
Global Highlight: Global growth remained resilient despite severe shipping disruptions in the Strait of Hormuz, although prolonged supply constraints continue to pose upside risks to energy prices and inflation. Meanwhile, the U.S. economy expanded by 1.5% QoQ in 2Q26, while easing inflation and a resilient labor market reinforced expectations of a higher for longer Fed policy stance. A sustained reopening of the Strait of Hormuz would help ease energy market risks, support disinflation, and improve the global economic outlook.
Indonesia Highlight: Bank Indonesia maintained the BI Rate at 5.75% while strengthening macroprudential and liquidity measures to support domestic demand and preserve Rupiah stability amid persistent external pressures. Inflation eased to 2.88% YoY in July 2026, supported by lower volatile food prices, although the Rupiah remained under pressure, consumer spending softened, and Indonesia recorded a trade deficit as imports outpaced exports. Meanwhile, manufacturing activity returned to expansion territory, but downside risks from El Nino, weaker household consumption, and global uncertainty continue to weigh on the domestic economic outlook.
IHSG View: Global equity markets remained volatile in July 2026 amid AI valuation concerns, escalating U.S.–Iran geopolitical tensions, higher crude oil prices, and uncertainty over the Fed's policy outlook. Domestically, the JCI rebounded 10.51% MoM, supported by Indonesia's sovereign rating reaffirmation, improving market sentiment, easing oil prices, and attractive valuations following the prolonged correction. Going forward, investors will focus on the Bank Indonesia leadership transition, upcoming U.S. economic data, the Fed's September decision, and APBN 2027 discussions, while we maintain our 2026 JCI target across all scenarios.
Sector Allocation:
Banks, Metal Mining, Plantations, Industrial, Oil & Gas, and Properties & Real estate. Read more for the Stock pick.
By PHINTRACO SEKURITAS | Research
- Disclaimer On -
Baca Laporan